
EMC Filtration Market Report Scope and Overview
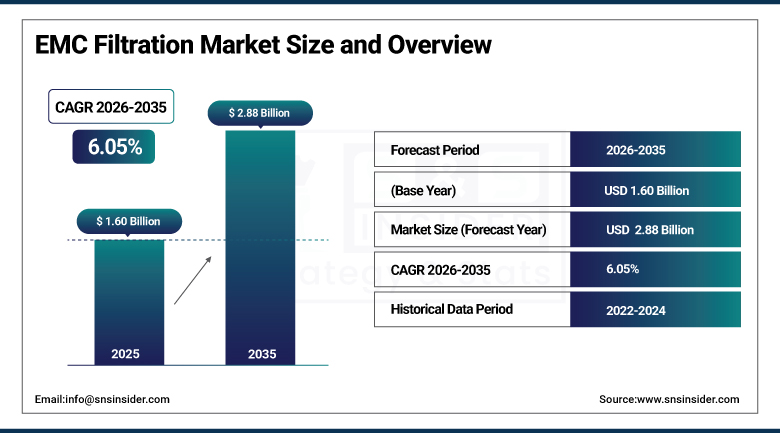
The EMC Filtration Market was valued at USD 1.60 Billion in 2025 and is estimated at USD 1.70 Billion in 2026. The market is forecast to reach USD 2.88 Billion by 2035, registering a CAGR of 6.05% from 2026 to 2035. Growth reflects tighter electromagnetic compatibility rules, rising use of fast-switching power electronics in motor drives, electric vehicle chargers, solar inverters, and data centers, and the need to curb harmonics and conducted noise on the grid. Asia Pacific accounted for the largest regional share at 36.60% in 2025 and is also expected to expand fastest.
To Get more information On EMC Filtration Market - Request Free Sample Report
Key Market Trends & Insights
-
By product type: EMC filters held the largest market share of 64.20% in 2025.
-
By insertion loss: Common-mode filters held the largest market share of 58.20% in 2025.
-
By application: Industrial automation held the largest market share of 26.40% in 2025.
-
Asia Pacific accounted for the largest regional share of 36.60% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 7.55% from 2026 to 2035.
-
Power quality filters are expanding at the fastest pace among product types, while differential-mode filters are the fastest growing insertion loss class and EV charging the fastest growing application.
Growth Outlook
Compliance is the first pillar of growth. Electrical and electronic equipment sold in most large economies must meet limits on conducted and radiated emissions and must tolerate interference from other devices, and filters placed at the power entry are the most direct way to meet those limits. Every new product that uses a switching power stage, from a drive to a charger, adds filter content, and regulators are extending limits to lower frequency ranges that call for new designs. Sales are especially strong in equipment that must be certified before shipment, and retrofit work adds steady replacement orders.
Electrification is the second pillar. Variable speed drives, electric vehicle chargers, solar inverters, battery storage, and data center power systems all use silicon carbide and gallium nitride switches that operate at high frequencies and create more noise. These systems need common-mode and differential-mode filters, harmonic filters, and output filters, and the growth of installed capacity in each of these uses supports the forecast expansion through 2035. Utility rules on harmonics and power factor add demand for harmonic filters and reactors at industrial sites, and grid operators increasingly check compliance at the point of connection.
Market Dynamics
Driver: Stricter Compliance Rules, Fast-Switching Power Electronics, and Electrification Expand Filter Demand
Manufacturers cannot place most electrical equipment on the market without proof that it meets electromagnetic compatibility requirements, and failing a test means redesign, delay, and lost sales. Filters give engineers a reliable and standard route to pass emission tests, so purchases are often written into product designs from the start. Extensions of emission limits to lower frequency bands, including ranges down to 9 kHz in some standards, call for new filter designs and create replacement demand for existing product families. Notified testing laboratories also report that failure rates at first submission remain high for new power products, which pushes manufacturers to add or upgrade filters late in development and favors suppliers with ready samples and design support.
Electrification reinforces this trend. Wide bandgap semiconductors switch faster than silicon, improving efficiency but producing sharper voltage edges and more high-frequency noise, and electric vehicle chargers, solar inverters, motor drives, and energy storage systems all depend on them. Data centers add further demand through large power supplies and uninterruptible power systems that must limit harmonics, and utilities and grid operators tighten rules on power quality, which supports sales of passive and active harmonic filters. Rapid construction of data centers for artificial intelligence workloads raises the number of power conversion stages per site, and each stage adds filtering and harmonic mitigation needs. Government incentives for charging networks and renewable capacity widen the installed base.
Restraint: Integration of Filtering Functions, Material Cost Swings, and Fragmented Certification Regimes Limit Margins
Chip makers and module suppliers are moving some filtering functions onto boards and into integrated circuits, and designers of compact electronics try to reduce the number of discrete parts. This trend limits the size of the market for small line filters in low-power products, and it pressures suppliers to cut size and cost. Customers in consumer electronics also push for lower prices, which compresses margins on standard catalog filters. Larger customers sometimes design their own filters in house to reduce cost, and semiconductor makers promote devices with spread spectrum and soft switching that lower emissions at the source. Both trends reduce the need for added filtering in some designs and make price negotiations tougher for catalog suppliers.
Material costs add uncertainty. Ferrite and nanocrystalline cores, copper, and capacitor materials are exposed to supply swings, and shortages can delay deliveries of chokes and filters. Certification rules also vary by country and product group, so suppliers must test and document the same filter for several regimes, which raises cost and slows launches. Counterfeit or poorly rated filters sold online further disturb pricing in some regions. Engineers also face space and weight limits in compact products, and high-performance filters can be bulky and costly. Small and medium sized makers may lack testing facilities and rely on trial and error, which can lead to repeated redesign and slower adoption of premium filters.
Opportunity: EV Charging, Data Centers, and Power Quality Solutions Open New Revenue Pools
EV charging offers the clearest opportunity. Fast chargers need filters for both alternating current inputs and direct current links, and ratings are rising toward high currents and voltages, which calls for larger and more valuable products. Public charging networks, depot charging, and vehicle onboard chargers each form separate demand pools, and suppliers that offer tested, application-specific filters can win design positions that last for years. Utility scale solar plants and battery storage sites raise the demand for high-voltage direct current filters, and manufacturers that offer ratings up to 1,500 V can address these projects. Vehicle makers and tier one suppliers also seek filters for onboard chargers and traction inverters with tight size limits.
Data centers, renewable energy, and industrial upgrades offer a second opportunity. Operators of large computing sites must limit harmonics and noise on the supply, and solar and storage installations use inverters that need filtering at both ends. Power quality filters, including active harmonic filters and output filters for drives, are growing faster than basic line filters, and suppliers can add testing, consulting, and design services to lift revenue per customer. Medical equipment makers and defense contractors pay premiums for filters with low leakage current and strict reliability records, and these uses are less sensitive to price. Suppliers can also sell pre-compliance testing and consulting to shorten customer development time.
Market Characteristics & Concentration
The EMC Filtration Market is Moderately Fragmented. A group of large electronic component and connectivity companies competes with specialist filter makers and regional suppliers, and no single company controls the market. Competition centers on insertion loss performance, current ratings, size, safety approvals, delivery time, and the ability to support customers with testing and design advice. Distribution partners play a large role in reaching small and medium customers, and regional makers hold strong positions in local supply chains.
The level of merger and acquisition activity is moderate. Large component groups acquire specialist filter makers to broaden portfolios and gain access to industrial and automotive customers, and smaller firms often focus on custom designs for drives, medical equipment, and military systems. Entry barriers include expertise in magnetics, safety certifications, and long customer qualification periods. Partnerships with semiconductor and charger developers help suppliers co-design filters for new switching devices, and these ties often lead to repeated orders.
Customers include drive and inverter makers, power supply producers, charger manufacturers, medical device makers, building systems suppliers, and original equipment makers in many sectors, and most sales run through direct contracts and electronic component distributors. Buyers weigh performance, certification, availability, and price, and large customers value suppliers that offer design support and local stock. Product approvals from safety agencies and long qualification cycles in medical and military uses create loyal customer relationships that are hard for new entrants to break.
Analyst Perspective
EMC filtration has moved from a compliance afterthought to a design choice that influences product cost, size, and reliability. Buyers no longer ask only whether a filter passes a test. They ask how it behaves with silicon carbide and gallium nitride switches, how large it is, how it performs over temperature, and how quickly the supplier can support redesign. Suppliers that combine broad catalogs, application-specific designs for chargers, drives, and data centers, and strong testing support will capture the largest share of new demand through 2035. Power quality products add upside beyond classic line filters. An SNS Insider Analyst, Santosh Bhul, commented, "EMC filter suppliers will win by matching designs to fast-switching power electronics and by supporting customers through compliance testing."
Segment Analysis
Product Type Insights
EMC filters accounted for the largest share of 64.20% in 2025. The group covers single-phase and three-phase line filters, direct current filters, IEC inlet filters, and chokes, and these parts are fitted at the power entry of almost every drive, power supply, medical device, and appliance. Demand is broad and steady because every new product that must pass emission tests needs a filter. Standardized catalog parts also make these products easy to source through distributors, which suits small and medium equipment makers that lack in-house design capacity. Suppliers add application notes and sample programs to speed selection.
Power quality filters are anticipated to grow at the fastest CAGR of 9.46% from 2026 to 2035. Passive and active harmonic filters, output filters, and reactors help sites meet grid rules, protect motors, and cut losses, and demand rises with drives, data centers, and renewable energy. Buyers also value these products for lower energy cost and longer equipment life. Utilities and plant operators are also moving to meet limits on total harmonic distortion at the point of connection, and reactors and output filters protect motors and cables from voltage spikes. Suppliers bundle products with sizing tools to ease selection.
Insertion Loss Insights
Common-mode filters held the largest share of 58.20% in 2025. Common-mode noise travels on both conductors in the same direction and is the main cause of emission test failures in drives, chargers, and inverters, so these filters are the standard choice. Suppliers offer wide ranges of current ratings and attenuation levels, which makes selection simple for design engineers. Three-phase and single-phase versions come in many current ratings, and designers often select standard parts and adjust only for leakage current limits. Medical and household products require low leakage designs, which keeps this segment diverse.
Differential-mode filters are projected to expand at the fastest CAGR of 7.46% from 2026 to 2035. Differential-mode noise appears between conductors and rises with the high switching frequencies of wide bandgap devices and compact power supplies. Designers increasingly combine both filter types in a single package, which supports value growth in this part of the market. Newer silicon carbide inverters and gallium nitride chargers switch at very high speeds, which makes differential-mode attenuation more critical, and suppliers develop compact chokes and capacitors tuned for these uses. Growth is also supported by designs that integrate both filter types in one housing, shortening qualification.
Application Insights
Industrial automation represented the largest share of 26.40% in 2025. Motor drives, machinery, and robots use switching power stages that produce strong noise, and factories need filters to protect nearby control systems and meet standards. Building technologies, including heating and cooling systems, elevators, and lighting, form a steady second group, while energy and utilities, medical, data centers, and power supplies add further demand. Rising factory automation, robotics adoption, and plant upgrades in Asia and North America sustain purchases, and drive makers often buy filters along with their drive components. Service and replacement sales add steady revenue.
EV charging is projected to expand at the fastest CAGR of 9.12% from 2026 to 2035. Chargers use high-power converters and are installed in public spaces and homes, so they must pass strict emission tests and protect the grid. Data centers, energy storage, and smart infrastructure also grow quickly, while oil and gas, military, and home appliance uses hold smaller shares. Utilities and grid operators adopt power quality equipment as distributed generation rises, and large server farms add uninterruptible power systems with built-in filtering needs. Medical equipment requires low leakage designs that command higher prices.
Regional Insights
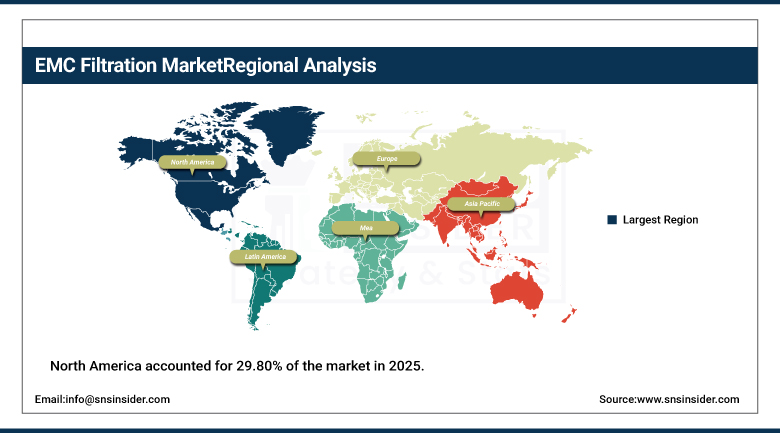
North America accounted for 29.80% of the market in 2025. Demand in the region follows strong industrial automation, data center construction, defense and aerospace programs, and rapid build-out of EV charging, together with the presence of leading filter makers and component distributors. Canada adds smaller demand through industrial equipment and energy projects, while Mexico is reported within Latin America. Distribution networks in the region support fast delivery to small and medium buyers, and defense and aerospace programs require filters with tight reliability records.
Get Customized Report as per Your Business Requirement - Enquiry Now
U.S. EMC Filtration Market
The U.S. EMC Filtration Market was valued at USD 383.82 Million in 2025 and is projected to expand at a CAGR of 5.62% from 2026 to 2035. The country has a large industrial base, the largest concentration of data centers in the world, and fast growth in charging networks and solar and storage projects, while emission limits set under Part 15 of the Federal Communications Commission rules apply to most electronic products. Defense and medical buyers add demand for specialized filters.
Europe EMC Filtration Market
Europe accounted for 23.90% of the market in 2025, led by Germany, the United Kingdom, France, Italy, and Switzerland. The region is home to major filter makers and drive and automation firms, and its compliance rules are among the strictest. The European Commission decision of 14 May 2025 updated the list of harmonised standards under the Radio Equipment Directive, including EMC standards in the EN 301 489 series, which keeps compliance work active. Industrial automation firms in Germany and Switzerland use large volumes.
Asia Pacific EMC Filtration Market
Asia Pacific is projected to register the fastest regional CAGR of 7.55% from 2026 to 2035, and the region held 36.60% of the market in 2025. China hosts the largest electronics and power equipment manufacturing base and the largest EV charging and solar installations, while Japan and South Korea add strong component makers and demanding quality requirements. Large power supply, drive, and charger producers in the region buy filters in volume, and local suppliers have grown quickly through competitive pricing.
India, Taiwan, Vietnam, and Southeast Asian countries add growing demand through electronics assembly, industrial expansion, and infrastructure projects. Local filter makers compete on price, and large power supply and drive producers buy locally, which supports volume growth across the region. Government programs that promote EV adoption, solar capacity, and data center construction in India and Southeast Asia add new installations, and international suppliers expand local stock and technical teams to meet rising demand. Quality standards are tightening, which shifts buyers toward certified products.
Latin America EMC Filtration Market
Latin America held 3.30% of the market in 2025. Brazil and Mexico lead demand through industrial plants, automotive and electronics assembly, and energy projects, and Mexico also supplies equipment to North American buyers. Most filters are imported or supplied through distributors, and growth follows industrial investment and renewable energy installation. Compliance rules in Brazil and Mexico align increasingly with international standards, and distributors hold stock of leading brands to serve industrial and building projects. Local assembly of drives and power supplies adds volume.
Middle East & Africa EMC Filtration Market
The Middle East and Africa accounted for 6.40% of the market in 2025. Saudi Arabia, the United Arab Emirates, and South Africa lead demand through utilities, oil and gas, data center projects, and large building developments. Investments in renewable energy and smart infrastructure add demand, while most products are imported. Large infrastructure projects and utility upgrades in the Gulf specify certified power quality equipment, and data center campuses under development add orders for high-rated filters. Africa has smaller but growing demand linked to mining and solar projects.
Key EMC Filtration Market Company Insights
Participants in the EMC filtration market include large electronic component and connectivity groups, specialist filter makers, and regional suppliers serving industrial and automotive customers. Leading firms compete on insertion loss performance, rating range, and design support, while smaller firms compete on custom designs and delivery speed.
Key EMC Filtration Companies:
-
TE Connectivity Ltd. (Schaffner)
-
SCHURTER Holding AG
-
TDK Corporation
-
Murata Manufacturing Co., Ltd.
-
Würth Elektronik GmbH & Co. KG
-
Delta Electronics, Inc.
-
Astrodyne TDI
-
Littelfuse, Inc.
-
YAGEO Corporation
-
Panasonic Holdings Corporation
Recent Developments
-
In December 2023, TE Connectivity completed the acquisition of a 98.7% stake in Schaffner Holding AG in a cash tender offer worth about CHF 320 million, adding Schaffner EMC filters and power quality products to its industrial and transportation portfolio.
-
In October 2025, TTI Europe and Schaffner, part of TE Connectivity, announced support for engineers preparing for emission rules that extend down to 9 kHz, supported by AC filters for EV charging and DC filters rated up to 1,500 V.
Scope and Research Methodology
The study defines the EMC Filtration Market as the revenue generated by passive filters and related components that suppress conducted electromagnetic interference and improve power quality, including single-phase, three-phase, and direct current filters, IEC inlet filters, chokes, harmonic filters, output filters, and reactors, sold to equipment makers, installers, and end users. Shielding materials, absorbers, test chambers, and board-level ferrite beads and capacitors sold as discrete components are outside the scope. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. The segmentation covers product type, insertion loss, application, and region, along with leading countries in each region. Mexico is reported within Latin America. Revenue is counted at the point of sale to the first buyer.
The research program combines secondary and primary research. Secondary research draws on company annual reports and filings, standards body publications, regulatory notices, customs and trade statistics, distributor data, patent filings, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with filter makers, distributors, drive and charger producers, test laboratories, and design engineers. These discussions validate assumptions on unit shipments, selling prices, rating mix, and design wins, and responses are weighted by the seniority and relevance of each respondent.
Market engineering follows a bottom-up build from filter shipments by type and rating, selling prices, and application mix, cross-checked top-down against electronic component and power equipment spending. Triangulation across both approaches narrows differences before values are finalized. Forecasts reflect drivers such as emission rules, wide bandgap adoption, and EV charging build-out, and every estimate passes through an analyst quality review that tests consistency across segments, regions, and years. Sensitivity checks test the effect of changes in industrial output, charger installations, and material costs, and regional estimates are aligned so that country values add to regional totals and regional totals add to the global value.
EMC Filtration Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.60 Billion |
| Market Size by 2035 | USD 2.88 Billion |
| CAGR | CAGR of 6.05% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (EMC Filters and Power Quality Filters) • By Insertion Loss (Common-Mode and Differential-Mode) • By Application (Industrial Automation, Building Technologies, Energy and Utilities, EV Charging, Medical, Data Centers, SMPS and Power Supplies, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | TE Connectivity Ltd. (Schaffner), SCHURTER Holding AG, TDK Corporation, Murata Manufacturing Co., Ltd., Würth Elektronik GmbH & Co. KG, Delta Electronics, Inc., Astrodyne TDI, Littelfuse, Inc., YAGEO Corporation, Panasonic Holdings Corporation |

Frequently Asked Questions
The market was valued at USD 1.60 Billion in 2025 and is projected to reach USD 2.88 Billion by 2035.
The market is expected to register a CAGR of 6.05% from 2026 to 2035.
Asia Pacific led the market with a 36.60% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 7.55% from 2026 to 2035.
EMC filters led the product type segment with a 64.20% share in 2025, and common-mode filters led the insertion loss segment.
