
Packaging Printing Market Report Scope & Overview:
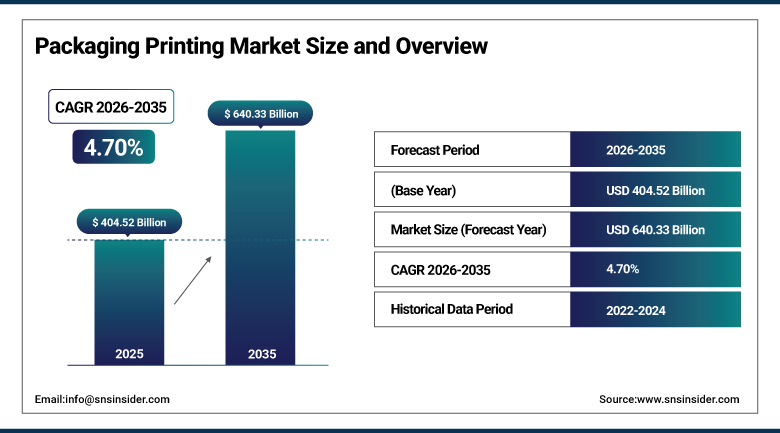
The Packaging Printing Market was valued at USD 404.52 Billion in 2025 and is expected to reach USD 640.33 Billion by 2035, growing at a CAGR of 4.70% from 2026 to 2035.
Differentiation and shelf visibility continue to be the key factors influencing the purchasing decision of consumers on a domestic level, since consumer packaged goods companies are competing for attention in an ever more crowded retail environment, where printed packaging quality really does affect purchasing decisions. Food and beverage producers make up a sizable portion of the demand for printing services in the domestic market, due to both the need for precise labeling and the sheer size of the food manufacturing industry in the country. The rise of e-commerce is also affecting print specifications through the need for a product that not only looks good on camera but in its package when delivered to the customer's door.
In January 2025, Pactiv Evergreen Inc. launched a new line of molded fiber packaging products, made from wood pulp and recycled paper, offering a compostable and recyclable alternative to traditional plastic fresh food packaging.
To Get more information Packaging Printing Market - Request Free Sample Report
Packaging Printing Market Trends
-
Digital printing adoption is accelerating as brands demand shorter runs and faster turnaround for SKU-heavy product lines.
-
UV-curable inks are gaining share for their faster curing times and reduced volatile organic compound emissions.
-
Track-and-trace printing incorporating serialized codes is expanding across pharmaceutical and premium consumer goods packaging.
-
Sustainable ink formulations and recyclable substrate compatibility are becoming standard requirements rather than premium features.
-
AI-assisted color matching and quality inspection are reducing waste and improving consistency across high-volume print runs.
U.S. Packaging Printing Market Outlook
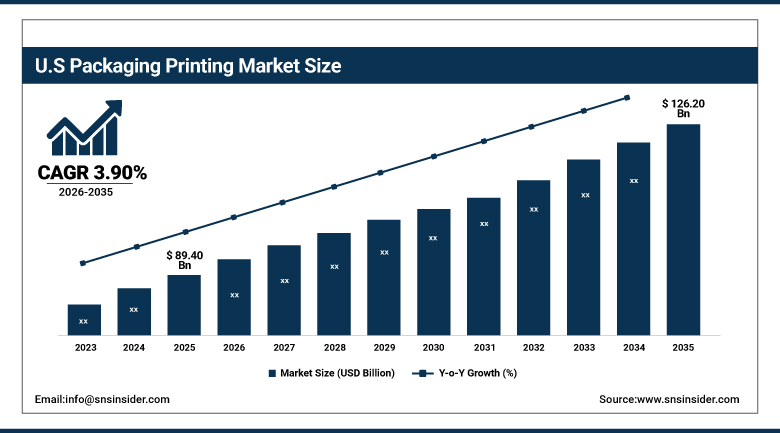
The U.S. Packaging Printing Market was valued at USD 89.40 Billion in 2025 and is projected to reach USD 126.20 Billion by 2035, growing at a CAGR of 3.90% during 2026-2035.
Brand differentiation and shelf visibility remain the dominant purchasing considerations domestically, as consumer packaged goods companies compete for attention in increasingly crowded retail categories where printed packaging quality genuinely influences purchase decisions. Food and beverage manufacturers account for a substantial share of domestic printing demand, driven by both stringent labeling requirements and the sheer scale of the country's packaged food industry. E-commerce growth continues reshaping print specifications too, as direct-to-consumer brands increasingly need packaging that photographs well for online listings while also standing out in a shipped box rather than a traditional retail shelf setting. Sustainability commitments among major retailers are pushing converters toward recyclable substrates and lower-impact ink formulations faster than in past years.
In August 2024, Pactiv Evergreen Inc. launched Recycleware Reduced-Density Polypropylene meat trays, recognized by the Association of Plastic Recyclers as meeting its highest design guidance criteria for recyclability.
Packaging Printing Market Segment Analysis
-
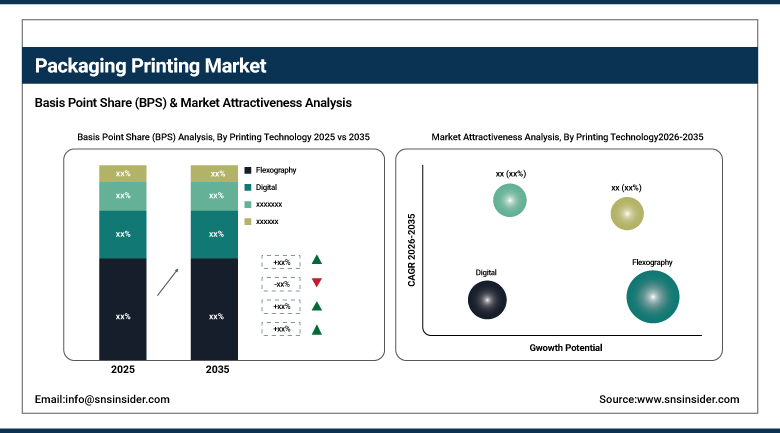
By Printing Technology, Flexography segment dominated the Packaging Printing Market in 2025 with 34% share; Digital segment is the fastest-growing segment, registering a CAGR of 9.20% from 2026 to 2035.
-
By Packaging Type, Paper segment dominated the market in 2025 with 42% share; Plastic segment is the fastest-growing segment, registering a CAGR of 6.40% from 2026 to 2035.
-
By End-Use Industry, Food & Beverage segment dominated the market in 2025 with 23.40% share; Pharmaceutical segment is the fastest-growing segment, registering a CAGR of 7.20% from 2026 to 2035.
-
By Application, Labels segment dominated the market in 2025 with 35% share; Product Information & Traceability segment is the fastest-growing segment, registering a CAGR of 8.40% from 2026 to 2035.
By Printing Technology, Flexography Leads the Packaging Printing Market While Digital Gains Ground Fastest
Flexography holds 34% of the Packaging Printing Market, remaining the standard technology for high-volume packaging production thanks to its compatibility with a wide range of substrates and its cost efficiency at the long print runs most packaged goods manufacturers still require. Established flexographic press infrastructure across the converting industry also keeps this technology the default choice for manufacturers prioritizing per-unit cost over the flexibility newer digital methods offer.
The digital segment is expanding at the rate of 9.20% CAGR, which is the highest rate of all printing techniques, since more converters have been needing flexible production to cater for small run volumes, quicker turnaround and increased customization without having to bear the high costs and longer lead time that traditional printing requires. The explosion of SKUs within consumer products has made such flexibility a competitive necessity.
By Packaging Type, Paper Dominates While Plastic Registers the Fastest Growth
Paper holds 42% of the market by packaging type, the largest single category, benefiting from its compatibility with high-speed printing processes and growing brand preference for recyclable, fiber-based substrates over plastic alternatives. Corrugated boxes, folding cartons, and paper-based labels together account for a substantial share of overall packaging printing volume across food, e-commerce, and general consumer goods categories.
Plastic is growing fastest by packaging type, at a 6.40% CAGR, as flexible plastic packaging continues expanding across food, personal care, and pharmaceutical applications where its barrier performance and lightweight shipping profile offer genuine advantages over paper alternatives. Advances in printable, recyclable mono-material plastic films are helping this category maintain growth even as sustainability regulation increasingly favors paper-based substrates in other packaging categories.
By End-Use Industry, Food & Beverage Dominates While Pharmaceutical Registers the Fastest Growth
Food & Beverage accounts for 23.40% of end-use demand, the largest single category, reflecting both the sheer volume of packaged food and beverage products moving through global retail and the stringent labeling requirements that make accurate, compliant printing a genuine regulatory necessity rather than a discretionary design choice. Cost-efficient printed packaging remains essential to this category, given how thin margins typically run across mainstream packaged food manufacturing.
Pharmaceutical is the fastest-growing end-use industry, expanding at a 7.20% CAGR, as tightening serialization and anti-counterfeiting regulation pushes drug manufacturers toward printing technology capable of encoding unique, verifiable identifiers on individual packages. Growing global pharmaceutical production, combined with stricter track-and-trace compliance requirements across major markets, continues reinforcing this segment's above-average growth trajectory.
By Application, Labels Dominates While Product Information & Traceability Registers the Fastest Growth
Labels hold 35% of the market by application, the largest single category, reflecting how central labeling remains to virtually every packaged product category, from basic ingredient and nutrition information to the brand identity elements that influence purchase decisions at the shelf. Established label printing infrastructure across the converting industry keeps this application the most economically accessible entry point for brand owners across every product category and price tier.
Product Information & Traceability is the fastest-growing application, expanding at an 8.40% CAGR, as regulatory requirements and brand protection concerns increasingly push manufacturers toward printed codes and serialized identifiers that support supply chain visibility well beyond basic label information. Growing consumer expectation for verifiable sourcing and authenticity information is reinforcing this trend across premium and pharmaceutical product categories in particular.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.00% |
|
Asia Pacific |
China |
38.00% |
|
Europe |
Germany |
25.40% |
|
Middle East & Africa |
UAE |
17.30% |
|
Latin America |
Brazil |
26.60% |
North America Packaging Printing Market Insights
North America's packaging printing market is mature and steady, supported by robust consumer demand, advanced manufacturing capabilities, and a well-established converting industry serving the region's large packaged goods manufacturing base. Growth here comes mostly from digital printing adoption and sustainable substrate transitions rather than first-time category adoption, since packaging printing has been standard practice across North American consumer goods manufacturing for decades.
The United States accounts for approximately 85.00% of the North American market, reflecting its large packaged goods manufacturing base and advanced printing technology infrastructure. Canada contributes a smaller but steady share, tied to its own consumer goods manufacturing sector and comparable printing industry standards.
Asia Pacific Packaging Printing Market Insights
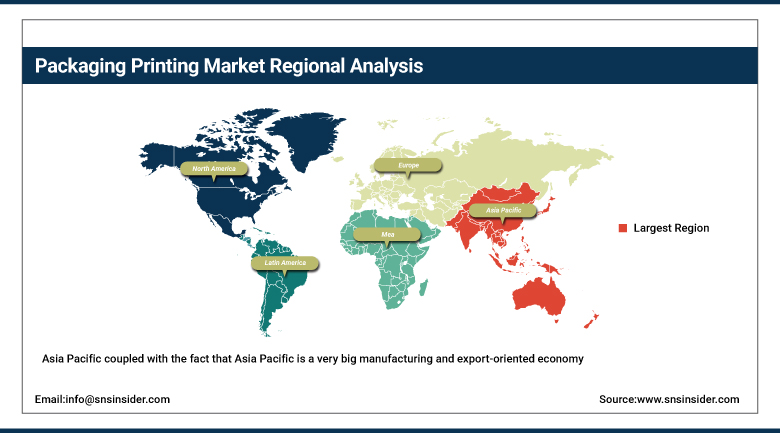
Asia Pacific is not only the biggest segment but also the fastest growing one among the various segments of the global Packaging Printing Market. Factors that have contributed to this include growing urbanization and increasing disposable income levels in Asia Pacific coupled with the fact that Asia Pacific is a very big manufacturing and export-oriented economy. The huge production and exports of packaged goods from China contribute to the leadership role of Asia Pacific, while in India consumer goods manufacturing is becoming increasingly important.
China makes up approximately 38.00% of the total market share in the region due to the huge manufacturing and export oriented packaged goods production from China.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Packaging Printing Market Insights
Europe's packaging printing market is mature and shaped heavily by sustainability regulation, which is pushing converters toward recyclable substrates and lower-impact ink formulations faster than in most other regions. Strong brand design traditions across the region continue supporting demand for premium printing finishes even as overall growth remains more measured than in Asia Pacific.
Germany leads the European market with a 25.40% share, supported by its large consumer goods manufacturing base and advanced printing technology industry. France and the United Kingdom follow, with demand in both countries tied to established packaged goods retail sectors and growing sustainability-driven substrate transitions.
Middle East & Africa and Latin America Packaging Printing Market Insights
The Middle East and Africa region shows promising growth due to increased demand for packaged goods in the Gulf countries, owing to increased retail penetration and regional investments in manufacturing. Similarly, Latin America also shows promising growth trends due to the increase in consumer goods manufacturing in Brazil and demand for printed packaging materials in food, beverages, and personal care categories.
UAE holds a 17.30% market share in the Middle East and Africa region due to its status as a distribution center of consumer goods. Brazil contributes 26.60% to the Latin American market on account of its consumer goods manufacturing facilities, while Mexico makes its contribution via packaging conversion.
Market Dynamics
Growth Drivers: SKU Proliferation and E-Commerce Expansion Fueling Market Growth
Rising SKU proliferation across nearly every consumer category is the clearest driver behind this market's growth, as brands increasingly need printing technology capable of supporting shorter, more customized runs without the cost penalty traditional long-run methods impose. Rapid e-commerce expansion is reinforcing this demand, as direct-to-consumer brands need packaging that performs well both online and in physical retail, often requiring different print specifications than traditional shelf-only products.
Growing demand for sustainable and premium packaging solutions is adding a meaningful additional demand line, as brand owners increasingly view printed packaging quality as a genuine differentiator in categories where product formulation alone no longer guarantees shelf standout.
Restraints: Raw Material Cost Volatility and Substrate Transition Complexity Limiting Market Expansion
The volatility of ink and substrates due to the petrochemical and pulp commodities markets makes it hard for converters to maintain stable pricing relationships with brand customers in their long-term supply arrangements. Shifting to recyclable substrates and reduced impact ink formulations may entail the need for new equipment investments and process requalification, which may be a costly undertaking for smaller converters without guaranteed customer demand. Labeling and ink safety regulations differ significantly from one market to another, making it difficult for converters to sell their standard packaging designs.
Opportunities: Digital Printing Investment and Traceability Technology Creating New Growth Avenues
The digital printing technology investment is one huge opportunity, especially for the printers who will be able to provide speed and quality at the same time for smaller orders because the customers are becoming more dissatisfied with the conventional plate-based printing because of its high costs and long processing time. The companies that will embrace this technology early will definitely be leading the competition that is using mostly long-run technology.
Secondly, there is a track-and-trace printing technology opportunity because many of the pharmaceutical and premium consumer products require not only labeling but also serial coding and brand protection features as well.
Recent Developments:
-
2025: Pactiv Evergreen Inc. became part of Novolex Holdings, LLC, combining fresh food and beverage packaging manufacturing capabilities across North America.
-
2025: Amcor plc launched a recycle-ready frozen and fresh food packaging format in Latin America featuring a 38% reduced carbon footprint compared with prior multilayer structures.
-
2025: Sonoco Products Company introduced a recyclable paperboard tray system for fresh and frozen retail packs, designed to replace multilayer plastic trays across major U.S. grocery chains.
-
2025: Huhtamaki Oyj launched compostable and recyclable packaging made from certified paperboard with a bio-based coating, keeping plastic content below 10%, for fresh and frozen food applications.
Packaging Printing Market key players are:
-
Amcor plc
-
Avery Dennison Corporation
-
CCL Industries Inc.
-
Smurfit Westrock plc
-
International Paper Company
-
Quad/Graphics, Inc.
-
HP Inc.
-
Eastman Kodak Company
-
Mondi Group
-
Sonoco Products Company
-
Huhtamaki Oyj
-
Constantia Flexibles Group GmbH
-
Tetra Pak International S.A.
-
Sealed Air Corporation
-
RR Donnelley & Sons Company
-
Toppan Holdings Inc.
-
Dai Nippon Printing Co., Ltd.
-
Cimpress plc
-
Fusion
-
WS Packaging Group, Inc.
Packaging Printing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 404.52 Billion |
| Market Size by 2035 | USD 640.33 Billion |
| CAGR | CAGR of 14.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Printing Technology (Flexography, Digital, Gravure, Offset) • By Packaging Type (Paper, Plastic, Metal, Glass) • By End-Use Industry (Food & Beverage, Pharmaceutical, Personal Care & Cosmetics, Electronics) • By Application (Labels, Branding & Marketing, Product Information & Traceability) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Avery Dennison Corporation, CCL Industries Inc., Smurfit Westrock plc, International Paper Company, Quad/Graphics, Inc., HP Inc., Eastman Kodak Company, Mondi Group, Sonoco Products Company, Huhtamaki Oyj, Constantia Flexibles Group GmbH, Tetra Pak International S.A., Sealed Air Corporation, RR Donnelley & Sons Company, Toppan Holdings Inc., Dai Nippon Printing Co., Ltd., Cimpress plc, Fusion, WS Packaging Group, Inc. |
Frequently Asked Questions
Key players include Amcor plc, Avery Dennison Corporation, CCL Industries Inc., Smurfit Westrock plc, International Paper Company, Quad/Graphics, Inc., HP Inc., and Eastman Kodak Company, alongside other established packaging printing manufacturers.
Key opportunities include digital printing investment for shorter, customized production runs, track-and-trace printing technology for pharmaceutical and brand protection applications, and sustainable substrate and ink formulation innovation.
The market is driven by rising SKU proliferation across consumer categories, rapid e-commerce expansion, and growing demand for sustainable and premium packaging solutions.
The Flexography segment dominated the Packaging Printing Market in 2025.
The Asia Pacific region dominated the Packaging Printing Market in 2025, driven by urbanization, rising disposable incomes, and the region's massive manufacturing base.
