
Portable Medical Devices Market Report Scope & Overview:
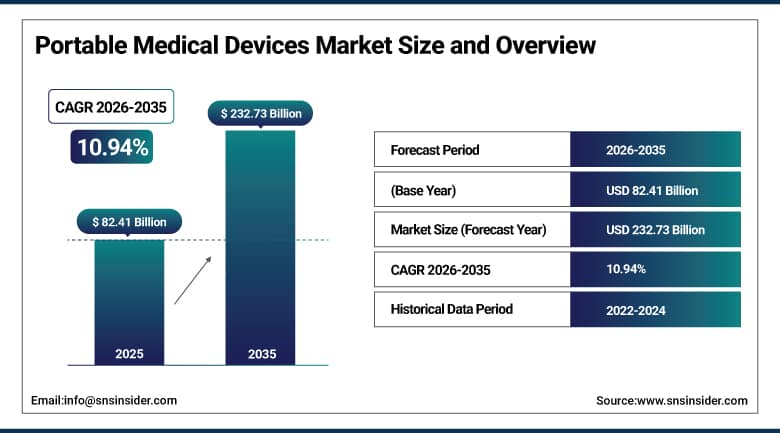
The Portable Medical Devices Market was valued at USD 82.41 Billion in 2025 and is estimated at USD 91.43 Billion in 2026. The market is projected to reach USD 232.73 Billion by 2035, expanding at a CAGR of 10.94% from 2026 to 2035. Growth reflects the shift of monitoring, diagnosis, and therapy from hospital wards to homes, ambulances, and community clinics. Rising chronic disease, an older population, smaller and more accurate sensors, and wireless connection to smartphones and cloud platforms are encouraging providers and patients to adopt compact devices. These factors support steady demand.
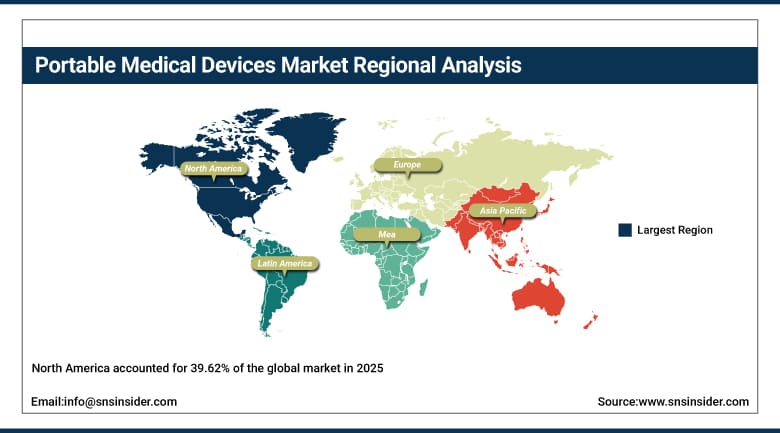
North America was the biggest regional segment in 2025, accounting for 39.62%. North America is aided by its high prevalence of heart diseases and diabetes, good health insurance for remote monitoring, and an established base of medical device manufacturers who regularly bring out new products. The hospitals in the U.S. have expanded their virtual clinics with the help of portable monitors, while consumers have purchased blood pressure monitors, glucose sensors, and electrocardiogram wearables from their pharmacies and e-stores. The manufacturers of medical devices in the region spend significantly on their sensors and cloud software.
To Get More Information On Portable Medical Devices Market - Request Free Sample Report
Key Report Takeaways
-
By product, monitoring devices held a 47.26% share in 2025, while smart wearable medical devices are the fastest growing.
-
By application, cardiology held a 28.47% share in 2025, while gynecology is the fastest growing.
-
By end user, hospitals held a 38.64% share in 2025, while homecare settings are the fastest growing.
-
By portability, hand-held devices held a 43.17% share in 2025, while wearable devices are the fastest growing.
-
By region, North America held a 39.62% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Continuous glucose monitors, wearable cardiac monitors, and connected blood pressure devices are moving from specialist use into routine primary care, supported by simpler sensors and longer wear times.
Hand-held ultrasound and pocket-sized imaging tools are becoming standard in emergency, critical care, and primary care settings, because clinicians can scan at the bedside and share images immediately.
Artificial intelligence is being built into portable devices for rhythm detection, image guidance, and alerts, which allows nurses and general practitioners to act on results without a specialist present.
Hospitals are adopting hospital-at-home and virtual ward models, which depend on portable monitors that send vital signs to a central team and reduce the number of inpatient days.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising Chronic Disease Burden |
+3.12% |
Global |
Short term (2 years or less) |
|
Shift to Home Healthcare and Remote Monitoring |
+2.61% |
North America, Europe |
Medium term (2 to 4 years) |
|
Wearables, Wireless Connectivity, and IoMT |
+2.38% |
Global |
Medium term (2 to 4 years) |
|
Aging Population |
+2.24% |
Global |
Long term (4 years or more) |
|
Technology Gains in Accuracy and AI |
+1.97% |
North America, Europe, Asia Pacific |
Medium term (2 to 4 years) |
|
Government Programs and Reimbursement Support |
+1.60% |
Asia Pacific, North America |
Long term (4 years or more) |
Rising Chronic Disease Burden
Cardiovascular disease, diabetes, hypertension, and respiratory illness require frequent measurement of blood pressure, glucose, heart rhythm, and oxygen levels, and portable devices make this possible outside hospitals. Patients with long-term conditions are advised to monitor themselves at home, which creates repeat demand for sensors, strips, and replacement units. In July 2025, the World Health Organization stated that an estimated 19.8 million people died from cardiovascular diseases in 2022, which keeps cardiac and blood pressure monitors high on the agenda of health systems.
Shift to Home Healthcare and Remote Monitoring
Health systems are trying to shorten hospital stays and reduce readmissions, so more patients are discharged with portable monitors and connected devices. Remote patient monitoring programs, virtual wards, and hospital-at-home services allow clinicians to follow vital signs from a distance and intervene before a condition worsens. Payers also see these programs as a way to lower cost per episode of care. Demand is especially strong in North America and Europe, where staff shortages make remote monitoring an attractive option. This supports steady demand.
Wearables, Wireless Connectivity, and IoMT
Smaller sensors, low-power chips, and reliable wireless links have made it possible to build clinical-grade devices that are worn on the body or carried in a pocket. Data can be sent through smartphones to cloud platforms, where software reviews trends and alerts the care team. Manufacturers are also adding interfaces to electronic health records, which makes portable data more useful to physicians. As an illustration, continuous glucose sensors and wearable heart monitors now sync automatically with mobile applications used by patients and clinicians.
Aging Population
Older adults have a higher rate of heart disease, diabetes, sleep disorders, and mobility problems, and they often prefer to receive care at home. Portable devices help them stay independent by tracking symptoms, detecting falls or abnormal rhythms, and supporting medication routines. Many countries in Europe and East Asia have a rapidly growing share of residents above age 65, and this trend will lift demand for monitors, oxygen concentrators, and wearable alert devices throughout the forecast period. Caregivers also benefit from simple alerts.
Technology Gains in Accuracy and AI
In terms of sensor precision and signal processing, the difference between portable and hospital grade equipment has been narrowed. Artificial intelligence is currently employed to identify arrhythmias, guide the ultrasonic probe, and categorize images, thus making it possible for non-experts to operate on these devices without hesitation. Moreover, increased battery capacity, durability of design, and quick charging capabilities allow their application in the field of emergency medicine, military service, and rural clinics. All of these advancements will make hospitals consider replacing their bulky and expensive machines with smaller, cheaper, and more transportable ones.
Government Programs and Reimbursement Support
Public programs that strengthen primary care, rural health, and digital health are widening access to portable devices. In September 2025, China's National Medical Products Administration reported that 13,133 medical device registrations were approved in 2024, which shows the pace of product entry in one of the largest markets. Reimbursement for remote monitoring in the United States and national insurance coverage in parts of Asia Pacific are also making it easier for providers to purchase and prescribe these devices. These steps encourage steady purchasing.
Restraints Impact Analysis
| Restraints |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Device Cost and Reimbursement Gaps |
-0.96% |
Global |
Short term (2 years or less) |
|
Data Security and Privacy Risk |
-0.88% |
Global |
Medium term (2 to 4 years) |
|
Complex Regulatory Approval Requirements |
-0.71% |
Europe, Global |
Medium term (2 to 4 years) |
|
Battery Safety and Limited Rural Infrastructure |
-0.43% |
Asia Pacific, Africa |
Long term (4 years or more) |
High Device Cost and Reimbursement Gaps
Advanced portable devices such as wearable defibrillators, continuous glucose sensors, and hand-held ultrasound systems carry high purchase prices, and consumables add to the cost of ownership. Patients in low-income countries often cannot afford them, and insurance coverage varies widely. Payment rules also create uncertainty. For example, the Centers for Medicare & Medicaid Services applied a negative 2.50% efficiency adjustment to physician fee schedule payments from January 2026, which adds pressure on provider budgets for equipment and monitoring services. Buyers therefore delay upgrades.
Data Security and Privacy Risk
Portable devices collect sensitive health information and transmit it through smartphones, home networks, and cloud platforms, which creates many points where data can be intercepted or misused. Manufacturers must build encryption, authentication, and software update systems into products that often have small processors. Hospitals and consumers are cautious about devices that cannot show clear safeguards, and privacy rules in North America and Europe require detailed compliance work that increases development cost and slows launches. These obligations are a recurring burden for smaller suppliers.
Complex Regulatory Approval Requirements
Approval must be acquired separately in every market, and there are different requirements for software, sensors, and combination devices. Clinical data, quality systems, and post-market surveillance all contribute to increased costs of entry, especially for small businesses. In May 2026, the European Commission adopted the Implementing Regulation (EU) 2026/977 on conformity assessment and notified bodies, which is one more step towards reforms of European device legislation and necessity of changing documentation and approval process for companies. It affects smaller manufacturers to the greatest extent because maintenance of the compliance department costs much money.
Battery Safety and Limited Rural Infrastructure
Portable devices rely on rechargeable batteries, and overheating, power loss, or poor charging practices can cause malfunction or injury. Devices that need frequent charging are harder to use for older patients and in areas with unreliable electricity. Rural regions in Asia Pacific and Africa also have limited broadband, few trained technicians, and weak service networks, so devices that depend on constant connectivity or specialist support are adopted more slowly than in urban centers. Service gaps therefore limit the installed base in these regions.
Portable Medical Devices Market Segment Analysis
By Product, Monitoring Devices Dominate Portable Medical Devices Market; Smart Wearable Medical Devices to Register Fastest Growth.
Monitoring devices hold the leading position because blood pressure, glucose, cardiac, respiratory, and vital sign monitoring are needed by the largest number of patients. They accounted for 47.26% of the market in 2025. Hospitals use portable monitors for transport and bedside care, while patients use them at home to follow chronic conditions. Frequent replacement of sensors and the steady launch of connected models keep this segment ahead of diagnostic and therapeutic categories. Replacement sensors and cuffs create recurring sales.
Smart wearable medical devices are projected to expand at a CAGR of 17.88% from 2026 to 2035. Patches, watches, rings, and chest straps now record heart rhythm, oxygen saturation, temperature, and glucose data continuously, and clinicians can review results remotely. Declining sensor cost, regulatory clearance of clinical features, and consumer comfort with wearable technology are encouraging providers to prescribe these devices for cardiac, diabetes, and sleep care. Manufacturers are also adding artificial intelligence features to improve alert quality for patients.
By Application, Cardiology Dominates Portable Medical Devices Market; Gynecology to Register Fastest Growth.
Cardiology leads the application axis, with 28.47% of the market in 2025, because heart disease is the most common reason for long-term monitoring and emergency intervention. Portable electrocardiogram recorders, blood pressure monitors, wearable defibrillators, and hand-held cardiac ultrasound are used across hospitals, ambulances, and homes. Early detection of arrhythmia and heart failure is a priority for health systems, which keeps cardiology ahead of other clinical areas. Wearable and hand-held cardiac tools also reach rural communities that lack specialist clinics.
Gynecology is expected to register the fastest growth, at a CAGR of 13.21% over 2026 to 2035. Portable ultrasound, fetal monitors, and wearable pregnancy tracking tools allow prenatal checks to be done in clinics and homes. Maternal health programs in developing countries, attention to high-risk pregnancy, and growing interest in remote antenatal care are increasing the use of compact devices in women's health. Public awareness campaigns on pregnancy complications, together with falling prices for compact scanners, support this expansion.
By End User, Hospitals Dominate Portable Medical Devices Market; Homecare Settings to Register Fastest Growth.
The hospitals segment holds the largest share, contributing 38.64% in 2025, due to purchasing of portable monitors, ultrasound devices, and defibrillators in emergency departments, intensive care, operating theatres, and patient transfer units. Large procurement budgets and ease of transferring medical devices between wards drive the demand for compact and portable devices. Hospitals also establish clinical guidelines that affect prescribing practices in outpatient and ambulatory settings, supporting regular renewal cycles of medical devices. Procurement teams also prefer vendors offering after-sales services, including maintenance and staff training.
The homecare segment is expected to record the fastest growth with a CAGR of 12.58% during 2026-2035. Patients prefer recovering at home, as well as managing their chronic conditions. Payors are keen on promoting solutions for reducing hospitalization rates. Home use medical devices include monitors, wireless glucose monitoring devices, and oxygen concentrators that can be monitored remotely, as well as sold online. Telehealth platforms, nurse visitation services, and insurer-supported home care programs for heart failure and diabetes patients further promote their adoption.
By Portability, Hand-Held Devices Dominate Portable Medical Devices Market; Wearable Devices to Register Fastest Growth.
Handheld devices take the lead in this axis, accounting for 43.17% in 2025, since they are lightweight, inexpensive and easy-to-use in different environments. The devices include pulse oximeters, thermometers, blood pressure cuffs, glucose meters, and pocket ultrasounds. The devices can be transported easily among patients and even used by consumers without any learning process; hence volumes are high in general practice, emergency services and at home. Rugged construction and low-cost nature make it possible for the users to use them repeatedly over a long period.
Wearable devices are forecast to have a CAGR of 16.43% during the period of 2026 to 2035. Continuous monitoring generates a higher volume of valuable information compared to spot checking and increased battery life and sensor size increase comfort. Healthcare organizations have incorporated wearable devices in post-discharge monitoring, rhythm detection, and chronic disease management programs, while payers are experimenting with coverage policies supporting continuous remote data collection. Additionally, companies are also trying to develop wearable devices with longer battery life and light construction.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
89.37% |
|
Europe |
Germany |
24.72% |
|
Asia Pacific |
China |
36.84% |
|
Middle East & Africa |
Saudi Arabia |
31.56% |
|
Latin America |
Brazil |
44.93% |
North America Portable Medical Devices Market
North America accounted for 39.62% of the global market in 2025, supported by a high burden of chronic disease, wide adoption of remote patient monitoring, and the presence of many leading manufacturers. The United States market was valued at USD 29.18 Billion in 2025 and is projected to grow at a CAGR of 11.06% from 2026 to 2035. Health systems are expanding virtual care programs, and consumers are buying connected devices directly. Strong clinical networks further speed adoption of new devices.
Regulatory policy shapes product design in the region. In January 2026, the U.S. Food and Drug Administration updated its General Wellness guidance for low-risk devices, which clarifies how some sensing products can be marketed to consumers. Canada adds demand through provincial virtual care programs, and its remote communities rely on portable ultrasound and monitoring devices to extend specialist services. Both countries have large home care and primary care networks, and pharmacy chains and online retailers make monitors available to consumers without delay.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Portable Medical Devices Market
Europe takes the second-biggest share in the market. It is led by Germany, then comes the UK, France, and Italy. An aging population, good public health insurance, and digital health solutions at the national level ensure regular demand for portable diagnostic tools. The hospitals in Europe are embracing the virtual ward model, which relies on connected devices; this is especially prevalent in the UK and the Nordic countries. Italy and Spain are also introducing capacity for home-based monitoring in their national healthcare programs.
Due to the introduction of the Medical Device Regulation, manufacturers have been faced with high documentation and clinical evidence requirements. This places smaller companies at a disadvantage since they lack quality systems. The UK and France are reimbursing some of the selected digital health solutions and connected devices, making it easier to adopt them in out-patient settings. In Eastern European countries, there is capacity being introduced for the purchase of emergency and primary care equipment due to the modernization of hospitals.
Asia Pacific Portable Medical Devices Market
The fastest-growing region is Asia Pacific, with a forecasted CAGR of 12.47% during 2026-2035. Aging population, increasing cases of diabetes and cardiovascular diseases, increased middle-class income, and government expenditure on the development of primary care facilities drive the demand in the region. China is the leader of the region owing to the presence of monitor and ultrasound system manufacturers in the region, while Japan and South Korea are established markets for sophisticated wearables. The rapid urbanization along with increased health consciousness of young population further fuels device ownership. Government screening camps and corporate wellness programs are also sources of consistent volume for basic monitors.
Public screening program and private clinics in India and Southeast Asia add new customers. Devices like portable ultrasound, glucose meters, and blood pressure monitors find their application in rural healthcare facilities that do not have bulky equipment. The manufacture of devices by local companies and affordable prices from regional players have helped improve availability, while e-commerce has enabled consumers to purchase devices in secondary cities. Post-pandemic telemedicine adoption continues to fuel the demand for connected devices in urban households and clinic network across the whole region.
Latin America Portable Medical Devices Market
Latin America is the smaller region consisting of Brazil, followed by Mexico, Argentina, and Colombia. Increased cases of diabetes and hypertension, growing private insurance sector, and telehealth services drive demand for portable devices. According to the national health surveillance agency ANVISA in Brazil, 91,707 medical device authorizations were active in the region at the end of 2024, indicating the wide variety of products in the biggest regional market. Local manufacturers provide thermometers and glucose meters at an affordable price to public programs and retail customers. Pharmacy chains serve as effective distribution channels.
Mexico is a part of this region and drives demand due to the developed private hospitals sector, pharmacy chains, and numerous manufacturing facilities that produce devices for export to the USA. The governments of several countries purchase portable ultrasound and monitoring devices for their primary care clinics, although the volatility of the currency and dependency on imports affect buying decisions. Local distributors become key partners in importing and maintaining the devices, as manufacturers cooperating with them have easier access to hospital and private clinic tenders.
Middle East & Africa Portable Medical Devices Market
The Middle East & Africa region holds the smallest share of the market, but government health transformation programs in the Gulf are lifting demand. Saudi Arabia and the United Arab Emirates are the main buyers, while Qatar and Kuwait follow. In July 2025, the Saudi Food and Drug Authority reported that about 149 medical device clinical trials had been approved by the end of 2024, indicating growing regulatory activity. Younger populations and rapid urban growth support long-term demand for basic devices.
High rates of diabetes and hypertension in the Gulf encourage use of glucose sensors and blood pressure monitors, and private hospital groups are adding portable ultrasound and emergency devices. In Africa, South Africa, Egypt, and Kenya lead adoption, but limited funding and weak distribution networks restrict wider use. Donor-supported programs and mobile health initiatives are the main routes for portable device deployment. Medical tourism and expanding emergency services in the Gulf also raise purchases of compact diagnostic and life-support equipment.
Competitive Landscape
The Portable Medical Devices Market has a moderate level of concentration. Large global companies such as Abbott, Medtronic, Philips, Dexcom, Omron, and Siemens Healthineers lead in diabetes, cardiac, and monitoring products, while many regional manufacturers compete on price in basic monitors, thermometers, and ultrasound systems. Competition rests on accuracy, wear time, connectivity, regulatory clearance, and the ability to integrate with clinical software.
Vendors follow several strategic lines. Product launches focus on longer-wear sensors, smaller imaging probes, and AI-enabled alerts, while acquisitions and divestitures are used to focus portfolios on high-growth areas. Partnerships with software companies, wearable makers, and health systems extend the reach of portable devices into remote monitoring programs and consumer channels.
Portable Medical Devices Market Industry Leaders
1. Abbott: FreeStyle Libre continuous glucose monitoring systems, including the Libre Duo dual sensor.
2. Medtronic: MiniMed insulin delivery and Simplera Sync continuous glucose monitoring.
3. Philips: Patient monitoring ecosystem and mobile cardiac telemetry.
4. Dexcom: Dexcom G7 continuous glucose monitoring systems.
5. Omron: Home blood pressure monitors and connected cardiac devices.
Companies Covered in this Report
-
Abbott
-
Medtronic
-
Philips
-
Dexcom
-
Omron Healthcare
-
Masimo
-
ZOLL Medical
-
FUJIFILM Sonosite
-
Mindray
-
Siemens Healthineers
Recent Industry Developments
-
April 2025: Dexcom received U.S. Food and Drug Administration clearance for its Dexcom G7 15 Day continuous glucose monitoring system.
-
May 2025: Mindray launched its BeneVision V Series patient monitors with a wireless MRV Pod module at Euroanaesthesia.
-
October 2025: Omron Healthcare announced that cumulative sales of its blood pressure monitors had passed 400 million units.
-
November 2025: FUJIFILM Sonosite launched the Sonosite MT, a clamshell portable ultrasound system built for durability.
-
January 2026: ZOLL Medical launched its next-generation LifeVest wearable cardioverter defibrillator in the United States.
-
May 2026: Masimo stockholders approved the company's merger agreement with Danaher.
-
August 2026: Philips added six partners to its open patient-monitoring ecosystem to extend monitoring beyond the bedside.
-
August 2026: Abbott received U.S. Food and Drug Administration authorization for the Libre Duo 10 Day dual glucose and ketone sensor.
Portable Medical Devices Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 82.41 Billion |
| Market Size by 2035 | USD 232.73 Billion |
| CAGR | CAGR of 10.94% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Diagnostic Imaging, Monitoring Devices, Therapeutic Devices, and Smart Wearable Medical Devices) • By Application (Gynecology, Cardiology, Gastrointestinal, Urology, Neurology, Respiratory, Orthopedics, and Others) • By End User (Hospitals, Physician Offices, Ambulatory Surgical Centers, and Homecare Settings) • By Portability (Hand-Held, Wearable, and Trolley-Mounted) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Abbott, Medtronic, Philips, Dexcom, Omron Healthcare, Masimo, ZOLL Medical, FUJIFILM Sonosite, Mindray, Siemens Healthineers |

Frequently Asked Questions
The market was valued at USD 82.41 Billion in 2025 and is estimated at USD 91.43 Billion in 2026. It is projected to reach USD 232.73 Billion by 2035.
The market is projected to grow at a CAGR of 10.94% from 2026 to 2035, supported by chronic disease, home care, and wearable technology.
North America leads, with a 39.62% share in 2025, owing to a high disease burden and wide adoption of remote monitoring.
Asia Pacific is the fastest-growing region, with a CAGR of 12.47% from 2026 to 2035, driven by aging populations and primary care investment.
Monitoring devices, cardiology, hospitals, and hand-held devices lead their axes. Smart wearable medical devices, gynecology, homecare settings, and wearable devices are the fastest growing.
Abbott, Medtronic, Philips, Dexcom, and Omron are among the major players, with Masimo, ZOLL Medical, FUJIFILM Sonosite, Mindray, and Siemens Healthineers also active.
High device cost, data security, complex regulatory approvals, and limited rural infrastructure restrain faster adoption.
