
Smart Retail Market Report Scope & Overview:
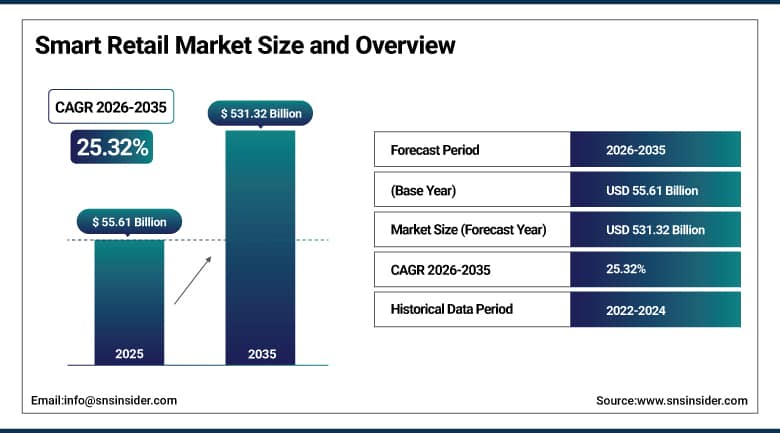
The Smart Retail Market size was valued at USD 55.61 Billion in 2025 and is expected to reach USD 531.32 Billion by 2035, growing at a CAGR of 25.32% from 2026-2035.
The Smart Retail Market covers connected hardware, software and services that digitize the shopping floor, such as electronic shelf labels, smart shelves, self-checkout, checkout-free stores, RFID tracking of products, shelf cameras, digital signs, and AI-enabled analytics. Retailers are applying them to automate tasks, enhance pricing accuracy, minimize out-of-stock situations, and offer personalized discounts when competing with digital competitors. Grocery retail is progressing from pilot projects to company-wide implementations of label projects, and computer vision is becoming a part of self-checkout to prevent shrinkage. Cloud technologies connect the data generated by stores to ecommerce and logistics. Reduced prices for sensors and labels expand usage beyond big chains. This all paves the way for rapid development until 2035. Attention of the public to pricing policies and data use affects communication of innovations.
⮞The National Retail Federation forecast on 18 March 2026 that U.S. retail sales would grow by 4.4% in 2026 to USD 5.6 trillion. Healthy spending gives retailers the headroom to invest in store technology.
To Get More Information On Smart Retail Market - Request Free Sample Report
Smart Retail Market Trends
-
Electronic shelf labels are being deployed chain-wide in grocery, often bundled with sensor rails and shelf-camera analytics.
-
Checkout-free technology is concentrating in high-throughput venues such as stadiums, campuses and airports.
-
Self-checkout lanes are adding computer vision and AI to reduce theft and speed up transactions.
-
RFID tagging is expanding from apparel into grocery, general merchandise and logistics for accurate inventory counts.
-
Retail media on in-store screens and shelf labels is emerging as a new revenue source for retailers.
U.S. Smart Retail Market Outlook
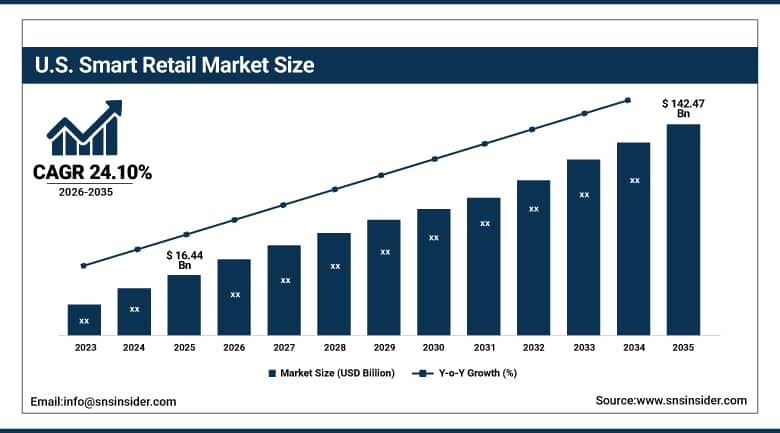
The U.S. Smart Retail Market was valued at USD 16.44 Billion in 2025 and is expected to reach USD 142.47 Billion by 2035, growing at a CAGR of 24.10% from 2026-2035.
The U.S. Smart Retail Market is the largest domestic market due to the presence of major retail chains, developed e-commerce market, and early adoption of checkout-free and self-service solutions. Grocers are implementing electronic shelf labels in order to improve pricing precision and reduce employees' workload, enabling them to provide better customer support and pick orders for online purchases. Major retailers use RFID and computer vision technologies to have better visibility into their inventories. Convenience chains are implementing app-based checkout solutions. Labor and shrink are among key drivers for implementation of the technology. The ongoing policy debate regarding dynamic pricing and privacy issues defines the way that new features will be used.
⮞The U.S. Census Bureau reported on 18 May 2026 that first quarter 2026 e-commerce sales reached USD 326.7 billion, or 16.9% of total retail sales, up 9.8% from a year earlier. Competition from online channels keeps pressure on stores to modernize.
Smart Retail Market Segment Analysis
-
By Offering, the Hardware segment dominated the Smart Retail Market with approximately 58.32% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 28.32%.
-
By Technology, the Artificial Intelligence and Machine Learning segment dominated the Smart Retail Market with approximately 27.64% share in 2025, while the Robotics and Automation segment is the fastest growing with a CAGR of approximately 29.85%.
-
By Application, the Inventory and Merchandise Management segment dominated the Smart Retail Market with approximately 23.70% share in 2025, while the Customer Experience and Personalization segment is the fastest growing with a CAGR of approximately 27.46%.
-
By Store Type, the Convenience Stores segment dominated the Smart Retail Market with approximately 24.35% share in 2025, while the E-Commerce Fulfillment Centers segment is the fastest growing with a CAGR of approximately 27.18%.
By Offering, Hardware Dominates the Smart Retail Market and Services Grows Fastest
Hardware leads because smart retail begins with physical devices installed in stores, including electronic shelf labels, cameras, sensors, RFID readers, self-checkout kiosks, point-of-sale terminals and digital displays. Large deployments across hundreds or thousands of stores generate substantial equipment orders. Retailers prefer to buy hardware up front, while software licenses follow. Competition among label and kiosk makers keeps technology advancing and prices falling, which makes it easier for more chains to start rollouts. Vendors also invest in pilots, training and managed services to help retailers move from trial to chain-wide rollout.
Services are growing fastest as retailers need help with integration, installation, managed operations and analytics. Deploying thousands of labels or camera systems requires planning, network setup and staff training. Vendors are moving to subscription and as-a-service models that bundle hardware, software and support. Cloud management platforms create recurring revenue. System integrators and retail technology consultants see strong demand for store design, data management and change management. Long procurement cycles mean that early engagement with store operations and IT teams is important. Competition among global groups and regional specialists continues to shape pricing and feature sets.
⮞Diebold Nixdorf reported on 29 July 2026 that second quarter retail segment revenue was USD 292.7 million compared with USD 236.0 million a year earlier, and said retail grew by more than 20% for a second consecutive quarter.
By Technology, Artificial Intelligence and Machine Learning Dominates the Smart Retail Market and Robotics and Automation Grows Fastest
Artificial intelligence and machine learning lead because they power the analytics behind demand forecasting, personalization, shelf monitoring, loss prevention and dynamic staffing. Computer vision turns store cameras into tools for tracking stock, queues and shopper behavior. Retailers are also using AI to automate pricing, planogram compliance and replenishment. Cloud services make advanced models accessible to mid-sized chains. As data from labels, sensors and checkouts grows, AI becomes the layer that converts it into decisions. System integrators and distributors extend reach to smaller chains and speed up installation.
Robotics and automation are becoming the most rapidly adopted technologies due to the usage of shelf scanning robots, automated micro-fulfillment centers, autonomous carts, and unmanned cabinets. The shortage of labor force and high salaries create an attractive business case for using robotics in operations that require repetitiveness like inventory management and picking orders. Unattended stores and vending machines are increasing their presence in Asia. Reduction of cost of robots and development of navigation software are contributing to higher payback periods. Connecting these technologies with the inventory and order management system creates additional value. CFOs demand a return on investment proof for these projects.
⮞Amazon said in September 2026 that its Just Walk Out technology had surpassed 400 stores globally, with many in sports and entertainment venues. The scale shows that checkout-free computer vision is finding commercial uses.
By Application, Inventory and Merchandise Management Dominates the Smart Retail Market and Customer Experience and Personalization Grows Fastest
Inventory and merchandise management leads because inaccurate stock records cause lost sales, excess markdowns and high labor costs. RFID, shelf cameras, smart shelves and electronic labels give retailers near-real-time visibility of products. Accurate inventory supports click-and-collect, ship-from-store and same-day delivery. Price changes done automatically minimize errors and labor. Chain stores get rapid return on investment through minimizing out-of-stock situations and more efficient replenishment, hence this is the initial application of choice by buyers. Buyers will consider how well the technology integrates into their existing POS and inventory system before choosing a vendor.
Customer experience and personalization are expanding at the fastest rate by leveraging app data, loyalty data, and in-store sensors to deliver personalized offers, shopper guidance, and quick check-out times. In-store technology such as interactive screens, smart mirrors, app-guided navigation, and mobile check-out seek to provide consumers with the same level of convenience that is provided through e-commerce sites. Retail media networks are using screen and label displays for promoting relevant products. Privacy policies necessitate careful designs, and the emphasis is being laid on opt-in programs by retailers.
⮞Impinj reported on 29 July 2026 that second quarter revenue reached a record USD 108.4 million, up about 10.7%, with guidance of USD 105.5 million to USD 108.5 million for the third quarter. RFID demand supports inventory accuracy.
By Store Type, Convenience Stores Dominates the Smart Retail Market and E-Commerce Fulfillment Centers Grows Fastest
Convenience stores lead because their small formats, long opening hours and high labor costs make automation attractive. Self-checkout, app-based payment, smart cabinets and unmanned stores can extend hours without more staff. Chains operate large networks that allow standardized rollouts once a model is proven. Fresh food, tobacco and age-restricted items add compliance tasks that technology can support. Convenience operators are also early users of retail media and digital menu boards. Warranty terms and long-term availability of spare devices matter for assets deployed across thousands of stores.
E-commerce fulfillment centers are growing fastest as online retailers invest in automated sorting, robotic picking, RFID tracking and smart inventory systems. Rising online order volumes and customer expectations for fast delivery increase pressure for accuracy. Dark stores and micro-fulfillment sites linked to supermarkets use the same tools. Supermarkets and hypermarkets also remain major buyers, particularly for electronic shelf labels. Department and specialty stores are adopting RFID and smart fitting rooms. Standardized interfaces and open application programming interfaces help retailers avoid vendor lock-in. Cloud platforms let retailers view store data alongside online sales and supply chain information.
⮞Pricer reported on 16 July 2026 that second quarter order intake was SEK 568.1 million, up 13.4%, with net sales of SEK 486.4 million. The rise in orders points to continued label demand from grocers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
88.40% |
|
Asia Pacific |
China |
38.24% |
|
Europe |
Germany |
31.07% |
|
Latin America |
Brazil |
42.35% |
|
Middle East & Africa |
United Arab Emirates |
33.18% |
North America Smart Retail Market Insights
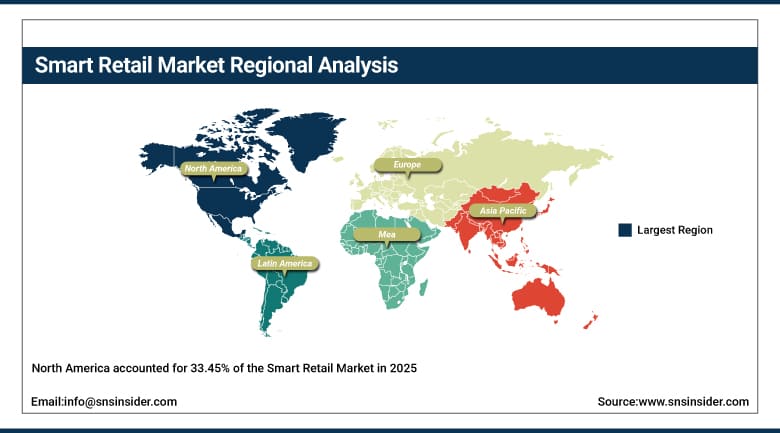
North America accounted for 33.45% of the Smart Retail Market in 2025, which made it the largest region. The United States dominates, with Canada contributing a smaller share. Large grocery, general merchandise and convenience chains operate thousands of stores and have the scale to justify technology investment. Early adopters include major grocers rolling out electronic shelf labels and big-box retailers using RFID. The region also hosts leading technology vendors and a deep venture ecosystem. Cybersecurity expectations for connected devices are now part of most retail technology tenders.
Labor costs, shrink and competition from e-commerce are the main reasons for adoption. Stadiums, campuses and airports are strong markets for checkout-free technology. Retailers are cautious about privacy and dynamic pricing concerns, which shape how features are used. Cloud and AI platforms from large technology firms are widely available. Growth is strong but slower than in Asia Pacific because many large chains have already begun deployment. Retail media is a growing source of income. Local service presence strengthens supplier relationships and shortens repair times.
⮞Zebra Technologies reported on 4 August 2026 that second quarter net sales were USD 1,557 million, up 20.4%, including organic growth of 9.2%. The company supplies scanners, mobile computers and retail workflow tools.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Smart Retail Market Insights
Asia Pacific is the fastest-growing region at a CAGR of 28.41% during 2026-2035 and holds the second-largest share. China leads with unmanned convenience cabinets, mobile payments, large supermarket chains and a strong electronics base. Japan has an advanced convenience store sector and a labor shortage that favors automation. South Korea, India and Southeast Asia are expanding organized retail and digital payments. Australia is an early adopter of self-checkout. Compact and low-power designs appeal to operators of small-format and remote stores. Pilot results in a few stores often decide the scale of later chain-wide orders.
Regional players like Hanshow and SoluM offer electronic shelf labels across the world, and there is also an extensive network of retail AI companies in China. Governments incentivize digital and cashless payment solutions. Increasing labor costs and urbanization make the shift towards automation more urgent for retailers. The super-app phenomenon creates an opportunity for the integration of online and offline retail, which creates value for technology that uses data. Growth opportunities are further fueled by the opening of many new stores and innovative formats. Shopping traffic is seasonal and affects the installation schedules.
⮞China's National Bureau of Statistics reported on 16 September 2026 that online retail sales of goods in January to August 2026 were CNY 8,419.5 billion, up 4.3%, compared with 1.1% growth for total retail sales of consumer goods.
Europe Smart Retail Market Insights
Europe holds a large share and has led the world in electronic shelf label adoption. Germany, France, the United Kingdom, the Netherlands and Nordic countries are major markets, with big grocers deploying labels, sensor rails and shelf cameras. Several vendors, including VusionGroup and Pricer, are headquartered in the region. High labor costs, strict price display rules and competition from discounters drive technology spending. Vendors also invest in pilots, training and managed services to help retailers move from trial to chain-wide rollout. Long procurement cycles mean that early engagement with store operations and IT teams is important.
self-checkout is popularly utilized in the UK and Nordic countries, where computer vision is implemented to minimize losses. The objectives of sustainability encourage retailers to go for paperless pricing systems and minimize food losses. The data protection regulations of GDPR affect the implementation of the camera-based analysis and personalization. Trials without checkout have not been successful and, therefore, terminated by some retailers. Eastern and Southern Europe are beginning to catch up with recent launches from the help of regional providers and system integrators.
⮞Colruyt Group said on 15 October 2026 that 454 Toshiba ELERA self-checkouts were installed in 150 of its stores, with 51 more stores to follow by the end of 2026. The rollout illustrates steady self-service adoption in Europe.
MEA & Latin America Smart Retail Market Insights
Latin America is advancing as large chains in Mexico and Brazil modernize stores and use technology to improve pricing and inventory control. Mexico benefits from large convenience and discount networks and close links to U.S. retailers. Brazil has a strong digital payments environment. Electronic labels, RFID and self-checkout pilots are expanding from large supermarkets to smaller formats. Adoption remains early compared with other regions, and import costs and currency swings affect project budgets. Pilot results in a few stores often decide the scale of later chain-wide orders.
The Middle East and Africa have less mature infrastructures to build upon, with the UAE and Saudi Arabia leading in terms of national vision behind retail modernization, tourism, and e-commerce. The Gulf has been an early adopter of smart retailing concepts like smart signage, cashierless shopping, and mobile payment systems in malls and hypermarkets. South Africa boasts a mature grocery retail sector. Informal retail forms a major part of many African countries, hence smart retailing is only possible in big urban chains.
⮞FEMSA reported on 28 July 2026 that second quarter revenues were up 9.3% and that OXXO Mexico same-store sales rose 9.5%. The growth of large convenience networks supports investment in store technology.
Market Dynamics
Growth Drivers: Labor Efficiency and Price Accuracy Drive Growth in the Smart Retail Market
Labor efficiency is the strongest driver. Retailers face high wages and staff shortages, and technology can automate price changes, inventory counts and checkout. Electronic labels remove the need to print and replace paper tags, which large grocers do on a very large scale. Employees freed from manual tasks can serve customers and pick online orders. Automation also supports longer opening hours with the same staff. Payback is often achieved within a few years. Documented return on investment is increasingly requested by finance teams before projects are approved.
Price accuracy and omnichannel demand become other motivators for adopting smart shelves. Legal problems and consumer dissatisfaction may arise if there is a difference between shelf price and system price; therefore, adoption of digital tags becomes appealing. Consumers nowadays demand current inventory data and delivery options such as same-day delivery and same-day pickup. Data from connected stores supports better planning and personalization. These pressures push retailers toward broad technology programs. Vendors continue to refine accuracy, battery life and wireless performance of in-store devices. Buyers weigh integration with existing point-of-sale and inventory systems before selecting a supplier.
⮞Kroger said on 17 June 2026 that electronic shelf labels were in 20 stores in the Columbus region, with 60 more planned by the end of 2026 and all stores in the region by the end of 2027, replacing about 1.3 billion paper tags a year.
Restraints: High Upfront Costs and Privacy Concerns Restrain Growth in the Smart Retail Market
Projects involving smart retail solutions need significant investment in terms of hardware and networking costs, and they can be difficult to justify in small or mid-sized stores. Profitability will depend on size and integration with legacy systems, and some pilots have not become profitable. Checkout-free solutions have been expensive and difficult to implement, and there have been failures of a number of companies offering them. The pressure is on vendors to keep their prices low because of stiff competition in the market. Training of store employees has helped adoption.
There are additional constraints posed by privacy and public acceptance. Consumer worries and legal problems related to cameras and personalized pricing, along with the costs of complying with regulations like GDPR and state privacy laws, are issues. There are worries about the potential for dynamic pricing from the use of electronic labels, and those concerns have attracted the interest of politicians. There are cybersecurity threats that arise because of connectivity. Old technologies, staffing issues, and new hardware supply chains could hinder implementation. Warranty issues and availability of spare devices over time are important for assets installed in thousands of locations.
⮞NCR Voyix reported on 4 August 2026 that second quarter revenue was USD 523 million, down 21% as reported but up 1% pro forma after its hardware business transition. The change shows how vendor models are shifting.
Opportunities: Retail Media and Network-Wide Label Rollouts Create Opportunities in the Smart Retail Market
Retail media networks provide new sources of income to retailers through the sale of advertising in screens, labels, and applications. Intelligent shelf edges, shopping carts, and display screens in retail stores will be able to promote products via targeted ads at the moment of truth. Technology vendors may provide ad networks as well as hardware, and the brands will get closed-loop measurement capabilities. All of that increases the value proposition for installing screens and labels in retail stores. Retailers may use cloud platforms for looking at their store, online sales, and supply chain data together.
Network-wide rollouts represent a second opportunity. Chains that complete pilots are moving to full deployment, which creates large orders and services contracts over several years. Smaller regional chains in Europe, Latin America and Asia are starting programs, and venues such as campuses, hospitals and airports are new markets for checkout-free technology. Falling costs of cameras and sensors, and as-a-service pricing, lower entry barriers. Local service presence strengthens supplier relationships and shortens repair times. Compact and low-power designs appeal to operators of small-format and remote stores.
⮞Fortenova Group's Kenty Adria said in October 2026 that Hanshow electronic labels were in more than 200 of 600 Konzum stores and 50 Mercator stores, with both networks targeted by the end of 2027 for about 3.1 million labels in total.
Recent Developments:
- In March 2026, Walmart de México y Centroamérica and VusionGroup expanded their partnership to a connected store platform covering more than 1.7 million electronic shelf labels and more than 180,000 EdgeSense smart rails. The rollout starts with 1,548 Walmart Express stores by the end of 2026, followed by 338 Supercenters and a Bodega pilot.
- In February 2026, Carrefour signed a strategic agreement with VusionGroup to digitize all of its French hypermarkets and supermarkets by 2030, following pilots that began in June 2025. The scope covers electronic labels, EdgeSense rails and Captana AI micro-cameras, and includes a joint Next Retail Experience Center.
- In February 2026, 7-Eleven expanded its AiFi-powered checkout-free pilot to select U.S. locations. Shoppers scan items in the phone app, pay by wallet or card, and scan a QR code at a station to finish, which supports 7-Eleven's push into frictionless convenience formats.
- In March 2026, Aldi UK ended its only Shop & Go checkout-free store in Greenwich, which used AiFi technology, saying the trial had come to an end as planned. The store continues to operate as a standard Aldi Local, highlighting the limits of checkout-free formats outside high-traffic venues
Smart Retail Companies are:
-
NCR Voyix
-
Diebold Nixdorf
-
VusionGroup
-
Hanshow
-
Pricer
-
Toshiba Global Commerce Solutions
-
Impinj
-
Amazon Just Walk Out
-
AiFi
-
Zippin
-
Mashgin
-
SoluM
Smart Retail Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 55.61 Billion |
| Market Size by 2035 | USD 531.32 Billion |
| CAGR | CAGR of 25.32% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Offering (Hardware, Software, and Services) • By Technology (Artificial Intelligence and Machine Learning, Robotics and Automation, Internet of Things, RFID and Sensors, and Others) • By Application (Inventory and Merchandise Management, Customer Experience and Personalization, Smart Payment and Checkout, Visual Marketing, and Others) • By Store Type (Convenience Stores, Supermarkets and Hypermarkets, Specialty Stores, Department Stores, and E-Commerce Fulfillment Centers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Zebra Technologies, NCR Voyix, Diebold Nixdorf, VusionGroup, Hanshow, Pricer, Toshiba Global Commerce Solutions, Impinj, Avery Dennison, Amazon Just Walk Out, AiFi, Zippin, Mashgin, SoluM |

Frequently Asked Questions
Key opportunities include retail media on screens and shelf labels, network-wide electronic label rollouts and checkout-free technology in venues such as campuses, hospitals and airports.
The major growth factor is the need for labor efficiency and price accuracy, which pushes retailers to adopt electronic shelf labels, automated inventory tracking and self-service checkout.
The Hardware segment dominated the Smart Retail Market with approximately 58.32% share in 2025, supported by large orders for labels, sensors, cameras and checkout devices.
North America dominated the Smart Retail Market with a 33.45% share in 2025, driven by large retail chains, early technology adoption and strong e-commerce competition in the United States.
