
Ultra High Purity Metal Tubing for Semiconductor Market Report Scope & Overview:
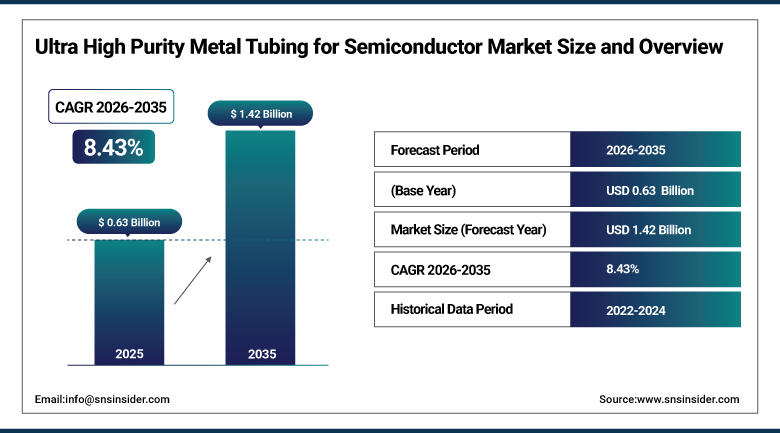
The Ultra High Purity Metal Tubing for Semiconductor Market was valued at USD 0.63 Billion in 2025 and is expected to reach USD 1.42 Billion by 2035, growing at a CAGR of 8.43% from 2026-2035.
The Ultra High Purity Metal Tubing for Semiconductor Market covers precision stainless steel and nickel alloy tubes, usually electropolished or bright annealed, that carry process gases, chemicals and ultrapure water inside wafer fabrication plants. These tubes must meet extreme cleanliness, surface finish and dimensional standards because even trace particles or moisture can ruin chips. Fab construction, higher gas purity requirements at advanced nodes and the spread of new fabs in the United States, Asia and Europe are driving demand through 2035. Suppliers include specialty steel mills, tube finishers, fitting and valve makers and gas system integrators, and qualification by equipment makers and fabs is a major barrier to entry. Pricing reflects the high level of cleanliness and documentation required.
⮞SEMI reported on 14 October 2026 that global 300mm fab equipment spending was expected to rise 31% to USD 149 Billion in 2026.
To Get more information Ultra High Purity Metal Tubing for Semiconductor Market - Request Free Sample Report
Ultra High Purity Metal Tubing for Semiconductor Market Trends
-
Electropolished 316L tubes with tighter surface roughness limits and lower particle counts are being specified for gas lines serving advanced logic and memory nodes. Suppliers publish roughness and particle data to win approval.
-
Fab builders are ordering tubing together with welding services, orbital weld inspection and cleaning to deliver ready-to-install gas panels. This shortens installation schedules at new fabs.
-
Nickel alloys and higher-grade stainless steels are gaining ground in lines that carry corrosive specialty gases and aggressive etch chemistries. Premium pricing supports supplier margins.
-
Local production and finishing capacity is being added near new fab clusters in the United States, Japan and Europe to shorten supply lines. Close proximity lowers logistics risk.
-
Digital traceability, including laser-marked heat numbers and cleanliness certificates, is becoming standard for tubing supplied to semiconductor fabs. Buyers use these records during audits.
U.S. Ultra High Purity Metal Tubing for Semiconductor Market Outlook
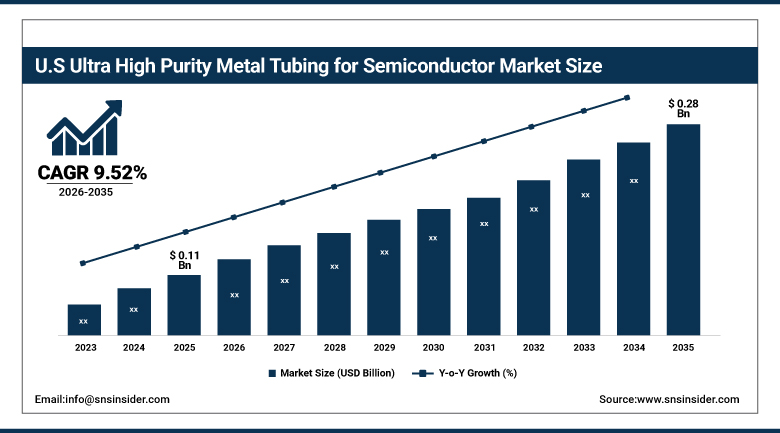
The U.S. Ultra High Purity Metal Tubing for Semiconductor Market was valued at USD 0.11 Billion in 2025 and is expected to reach USD 0.28 Billion by 2035, growing at a CAGR of 9.52% from 2026-2035.
The U.S. Ultra High Purity Metal Tubing for Semiconductor Market is the largest national market in North America, supported by large fab projects in Arizona, Texas, Ohio and New York and by the nation’s base of gas panel builders and tube finishers. Fab construction programs funded by federal incentives require thousands of meters of gas and chemical tubing per site, and equipment makers need tubing for tool gas panels. Demand rises as new fabs ramp production through 2035. Local tube finishers, welding contractors and gas panel builders are expanding capacity, and customers prefer suppliers able to deliver certified, cleaned and traceable products on short notice.
⮞The Congressional Research Service reported on 14 July 2026 that the U.S. Department of Commerce had awarded up to USD 30.7 Billion in direct CHIPS Act funding to 19 companies for 40 fab projects.
Ultra High Purity Metal Tubing for Semiconductor Market Segment Analysis
-
By Material Grade, the 316L Stainless Steel segment dominated the Ultra High Purity Metal Tubing for Semiconductor Market with approximately 62.18% share in 2025, while the Nickel Alloys segment is the fastest growing with a CAGR of approximately 10.24%.
-
By Finish, the Electropolished (EP) segment dominated the Ultra High Purity Metal Tubing for Semiconductor Market with approximately 57.46% share in 2025, while the Bright Annealed (BA) segment is the fastest growing with a CAGR of approximately 9.12%.
-
By Application, the Gas Delivery segment dominated the Ultra High Purity Metal Tubing for Semiconductor Market with approximately 39.40% share in 2025, while the Chemical and Slurry Delivery segment is the fastest growing with a CAGR of approximately 10.63%.
-
By End User, the Foundries segment dominated the Ultra High Purity Metal Tubing for Semiconductor Market with approximately 46.27% share in 2025, while the Memory Manufacturers segment is the fastest growing with a CAGR of approximately 11.02%.
By Material Grade, 316L Stainless Steel Dominates the Ultra High Purity Metal Tubing for Semiconductor Market and Nickel Alloys Grow Fastest
316L stainless steel holds approximately 62.18% of the Ultra High Purity Metal Tubing for Semiconductor Market in 2025. Its low carbon content resists corrosion, welds cleanly and takes a very smooth electropolished surface, which makes it the standard material for fab gas lines. Semiconductor equipment standards and decades of qualification data keep specifiers loyal to the grade. Mills supply it in seamless form with tight dimensional tolerances, and certificates tie each lot to its melt and processing history. Specifiers rarely deviate from it without lengthy testing. Their dominance is unlikely to fade during the forecast period.
Nickel alloys are the fastest growing material grade, with a CAGR of approximately 10.24% during 2026-2035. They resist the harsh halogen gases and acids used in etch and clean steps, where stainless steel can corrode and shed particles. Higher-grade stainless steels such as 316LN and 904L serve intermediate needs, offering added strength or corrosion resistance for chemical lines at moderate premiums. Their higher price is justified where a single corrosion event could contaminate a gas line and halt production. Specialty gas suppliers recommend them for the most aggressive halogen mixtures.
⮞The World Semiconductor Trade Statistics organization reported in August 2026 that global semiconductor sales reached USD 702 Billion in the first half of 2026, up 102% year on year.
By Finish, Electropolished Tubing Dominates the Ultra High Purity Metal Tubing for Semiconductor Market and Bright Annealed Tubing Grows Fastest
Electropolished tubing accounts for approximately 57.46% of the market in 2025. The process removes surface material and leaves a smooth, passive layer that sheds fewer particles and resists moisture retention, both critical for gas purity. Most process gas lines inside fabs call for electropolished tubes, and the finish carries a clear price premium over standard grades. Orbital welding practices and inspection standards are built around electropolished surfaces, which further locks in the specification. Inspection tools such as borescopes verify the surface after installation.
Bright annealed tubing is the fastest growing finish, with a CAGR of approximately 9.12% during 2026-2035. Annealing in a controlled atmosphere produces a clean, oxide-free surface at lower cost, and it suits utility lines, tool connections and less critical gas runs. Mechanically polished tubing serves chemical and water lines where extreme smoothness is less critical and cost control matters more. Fab operators often choose bright annealed tubes for utility lines to hold down installed cost while keeping acceptable cleanliness. Cost-conscious fabs and equipment builders adopt it widely for secondary runs.
⮞Taiwan’s Ministry of Finance reported on 8 October 2026 that September exports reached USD 87.22 Billion, up 60.9% year on year, with electronic components up 45.3%.
By Application, Gas Delivery Dominates the Ultra High Purity Metal Tubing for Semiconductor Market and Chemical and Slurry Delivery Grows Fastest
Gas delivery accounts for approximately 39.40% of the market in 2025. Fabs distribute bulk gases such as nitrogen and hydrogen and many specialty gases through miles of tubing, and each run must keep moisture and particles at parts-per-billion levels. Every new fab and every tool installation adds gas panels and lines that need certified tubing. Gas panels attached to process tools alone consume large quantities of small-diameter tubing, and replacements occur during maintenance. Maintenance and expansion projects continue even when new construction slows.
Chemical and slurry delivery is the fastest growing application, with a CAGR of approximately 10.63% during 2026-2035. Advanced nodes use more wet cleaning, planarization and deposition steps, which raises the volume of ultrapure chemicals moved through metal lines. Ultra pure water systems, vacuum and exhaust lines and other applications add steady demand, with water systems favoring corrosion-resistant grades. Corrosion resistance and low extractable metal content become critical in these lines. Slurry lines demand erosion-resistant surfaces and smooth bends. Fluoropolymer lines compete in some wet applications.
⮞Singapore’s Economic Development Board reported on 27 July 2026 that semiconductor output rose 21.1% year on year in June 2026.
By End User, Foundries Dominate the Ultra High Purity Metal Tubing for Semiconductor Market and Memory Manufacturers Grow Fastest
Foundries account for approximately 46.27% of the market in 2025. Leading contract manufacturers are building and expanding multiple large fabs at once, and each facility requires an extensive network of gas and chemical lines. Their scale, long-term capacity plans and strict contamination standards make them the biggest buyers of certified tubing. Their purchasing decisions often set the specification that smaller fabs and equipment makers later follow. Close ties with tool makers also guide material choices. Long contracts add visibility for suppliers.
Memory manufacturers are the fastest growing end user, with a CAGR of approximately 11.02% during 2026-2035. Demand for high-bandwidth memory and advanced flash is driving large capital programs in Korea, Japan, China and the United States. Logic integrated device makers and compound semiconductor and MEMS producers add further demand, with power electronics and silicon carbide fabs rising quickly. Capital intensity in memory is among the highest in the industry, so tubing orders follow closely behind construction milestones. Lead times for gas systems at these plants are shortening as suppliers add stock. Rising wafer starts add to consumable tubing needs.
⮞Korea’s Ministry of Trade, Industry and Resources reported on 1 October 2026 that September chip exports reached USD 60.3 Billion, up 263% year on year.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
31.84% |
|
North America |
United States |
84.31% |
|
Europe |
Germany |
34.27% |
|
Latin America |
Mexico |
58.93% |
|
Middle East & Africa |
Israel |
36.42% |
Asia Pacific Ultra High Purity Metal Tubing for Semiconductor Market Insights
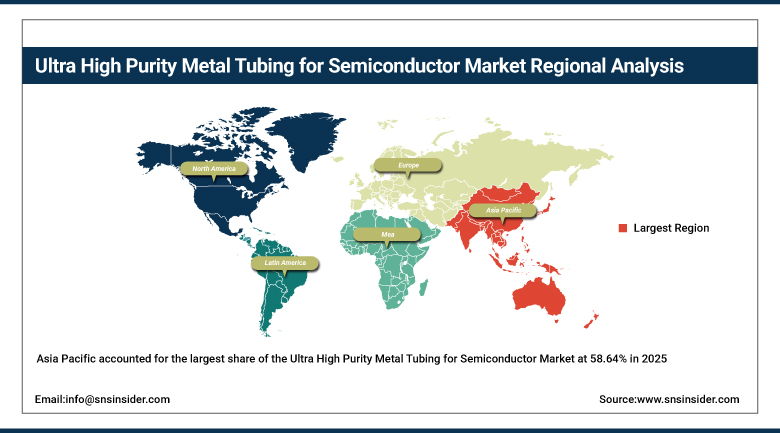
Asia Pacific accounted for the largest share of the Ultra High Purity Metal Tubing for Semiconductor Market at 58.64% in 2025. The region hosts the great majority of wafer fabs, led by Taiwan, South Korea, China and Japan, and it is also home to several large tube makers and finishers. Continuous fab expansion keeps orders strong. Government subsidies and corporate investment programs in several countries sustain a long pipeline of projects. Local steel mills provide ready access to feedstock. Fab clusters concentrate demand.
China is the largest country market, with 31.84% of regional demand, supported by aggressive capacity additions and a growing base of local tube suppliers. Taiwan and South Korea buy large volumes for leading-edge and memory fabs, Japan supplies precision tubing and fittings, and India is the fastest growing country as its first fabs and packaging plants move into construction. Local suppliers are improving quality quickly, and some have qualified with global equipment makers. Logistics hubs in Singapore and Malaysia support regional distribution. Rapid urbanization near fabs adds infrastructure demand.
⮞China’s National Bureau of Statistics reported on 15 July 2026 that integrated circuit output reached 279.8 billion units in the first half of 2026, up 23.1% year on year.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Ultra High Purity Metal Tubing for Semiconductor Market Insights
North America held approximately 21.35% of the Ultra High Purity Metal Tubing for Semiconductor Market in 2025 and is the fastest growing region, with a CAGR of 9.84% during 2026-2035. The United States contributes about 84.31% of regional demand, with Canada accounting for the balance. New leading-edge fabs, memory plants and packaging facilities are being built under federal incentives. Many projects are near large metropolitan areas where skilled labor for welding and installation is in demand. Securing skilled installers remains a focus.
Canada is a smaller market with research fabs and specialty producers. Mexico, which belongs to Latin America, hosts electronics assembly rather than wafer fabrication. Local tube makers, gas panel builders and welding specialists are expanding capacity near new fab clusters, and customers favor suppliers able to deliver certified, cleaned and traceable products quickly. Local content preferences in subsidy programs encourage buyers to qualify local sources. Close ties between fabs and universities support workforce growth. Qualified local vendors win repeat orders.
⮞The Semiconductor Industry Association reported on 6 August 2026 that June 2026 global chip sales rose 123.6% year on year, with Americas sales up 160.9%.
Europe Ultra High Purity Metal Tubing for Semiconductor Market Insights
Europe held approximately 11.48% of the Ultra High Purity Metal Tubing for Semiconductor Market in 2025, with Germany, Ireland, France, Italy and the Netherlands leading demand. The region has fabs focused on power, automotive and analog chips, along with strong makers of precision stainless tubing. New projects backed by public funds are expected to add demand. Public funding programs aim to double the region’s share of global chip output over the next decade. Local steel specialists are active in high-purity grades.
Germany is the largest market, with about 34.27% of regional demand, because of its chip manufacturing clusters in Dresden and its engineering suppliers. Ireland and the Netherlands add demand from established fabs and equipment production, and Nordic countries supply specialty steel. Tube makers in the region serve both European fabs and export customers. Sustainability rules also influence material choices and recycling of stainless scrap. Environmental rules push suppliers toward cleaner finishing chemicals. Recycling rules affect scrap handling. Specialty steel mills add to regional supply.
⮞The Statistical Office of Saxony reported on 4 February 2026 that employment in the state’s semiconductor industry reached more than 11,500 people in 2024, up 43% from 2009.
MEA & Latin America Ultra High Purity Metal Tubing for Semiconductor Market Insights
The Middle East and Africa and Latin America together account for approximately 8.53% of the Ultra High Purity Metal Tubing for Semiconductor Market in 2025, with Latin America at 4.61% and the Middle East and Africa at 3.92%. Israel hosts major fabs, and Gulf countries are launching semiconductor funds and industrial strategies that could create new demand for gas and chemical lines in future plants. Government agencies are reviewing incentives for chip design, packaging and eventually wafer fabrication. Tubing demand in these regions is small today but could grow if plans advance.
Latin America is led by Mexico and Brazil. Mexico supports electronics assembly and has seen strong export growth, while wafer fabrication remains limited. Brazil has small packaging and design activities. Demand for tubing in the region mostly comes from facility upgrades and test and assembly lines, with imports supplying nearly all products. Distributors bring in certified tubing for specialized projects. Distributors provide tubing for upgrades and small assembly lines across the region. Projects are small and irregular. Service partners are important.
⮞Mexico’s national statistics agency INEGI reported in September 2026 that exports rose 29.3% in the first eight months of 2026, with non-automotive manufacturing exports up more than 63% in August, led by computer equipment.
Market Dynamics
Growth Drivers: Fab Construction and Higher Purity Requirements Drive Growth in the Ultra High Purity Metal Tubing for Semiconductor Market
Fab construction is the strongest force behind the Ultra High Purity Metal Tubing for Semiconductor Market. Governments and chipmakers are funding new plants on every continent, and each large fab needs enormous lengths of certified tubing for gas, chemical and water systems. Equipment spending and construction schedules directly influence tubing orders, so the current investment wave brings strong volumes. A single advanced fab can cost tens of billions of dollars, and gas and chemical distribution is a measurable share of the facility build.
Higher purity requirements form the second driver. As chip features shrink, tolerance for particles, moisture and metallic contamination falls, which pushes fabs to specify better surface finishes, cleaner processing and tighter documentation. Advanced nodes use more process steps and more specialty gases, raising tubing intensity per wafer and supporting premium pricing for qualified suppliers. Fabs also demand full documentation and cleanliness certificates, which creates barriers for lower-grade suppliers. Wafer starts are expected to grow steadily, supporting consumables and replacements. Greater process complexity adds more tubing runs.
⮞Japan’s Ministry of Economy, Trade and Industry announced on 5 June 2026 an additional JPY 150 Billion of government investment in Rapidus, taking the total to JPY 250 Billion.
Restraints: Cyclical Capital Spending and Qualification Barriers Restrain Growth in the Ultra High Purity Metal Tubing for Semiconductor Market
Cyclical capital spending restrains the Ultra High Purity Metal Tubing for Semiconductor Market. Chipmakers delay or cancel fab projects when end demand softens, and tubing orders follow construction schedules closely. Sharp swings in activity make capacity planning difficult for tube makers, who must invest in drawing and finishing lines well before orders arrive. Construction delays, permit issues and shortages of electricians and welders can also push out orders. Overcapacity risk worries suppliers. Financing costs for new plants have also risen.
Qualification barriers add further friction. New suppliers must prove surface quality, cleanliness and traceability through lengthy tests, and fabs are reluctant to change vendors on running lines. Raw material costs for nickel and molybdenum fluctuate, and skilled welding labor is scarce in some regions, both of which can slow project timelines and squeeze margins. Price competition from regional mills adds pressure on margins for standard grades. Buyers therefore tend to stay with trusted vendors. Switching vendors requires new test data.
⮞India’s Ministry of Electronics and Information Technology reported on 24 June 2026 that INR 7,100 Crore of semiconductor incentives would be released in fiscal 2027.
Opportunities: Regional Fab Programs and Integrated Gas System Supply Create Opportunities in the Ultra High Purity Metal Tubing for Semiconductor Market
Regional fab programs create a major opportunity. The United States, Europe, Japan, India and Southeast Asia are all subsidizing new plants, which opens markets for local tube production, finishing and welding services. Suppliers able to establish facilities near these clusters, with certified cleaning and inspection capabilities, can win long-term supply agreements. Public funding for workforce training also helps overcome shortages of qualified installers. Joint ventures with fab builders help secure orders early. Local supply reduces freight risk. Close supplier partnerships ease planning.
Integrated gas system supply forms a second opening. Fabs and equipment makers increasingly buy pre-fabricated, pre-cleaned tube assemblies, manifolds and panels instead of raw tubing. Companies that bundle tubes, fittings, valves and installation services capture more value per project and strengthen customer relationships, while digital certification adds a further differentiator. Remote monitoring and purity analytics add services that deepen customer ties. Added services also help suppliers win share against low-cost rivals. Digital records ease audits. Warranties on cleanliness add confidence.
⮞Malaysia’s Ministry of Investment, Trade and Industry stated on 23 June 2026 that semiconductor exports rose 50% in January to April 2026.
Recent Developments:
- 2025: Swagelok unveiled its ALD7C valve with ALD Dose Control at SEMICON Taiwan, built in Alloy 22 for operation at 250°C and rated for more than 100 million cycles.
- 2026: KITZ completed its plant in Vinh Phuc, Vietnam, making ultra high purity gas valves for semiconductor equipment, with a stated investment of JPY 4.5 Billion.
- 2026: FITOK showed ALD diaphragm valves rated to 220°C, tied-diaphragm regulators and bellows valves at SEMICON Taiwan.
- 2026: BMT said its Busan Plant 2 would reach full operation by year-end, lifting capacity for ultra high purity fittings and valves from about KRW 250 Billion to KRW 350 Billion.
Ultra High Purity Metal Tubing for Semiconductor Market Key Players are:
-
Swagelok Company
-
Parker Hannifin Corporation
-
Ultra Clean Holdings, Inc. (Ham-Let)
-
Entegris, Inc.
-
Alleima AB
-
Tubacex, S.A.
-
Hy-Lok Corporation
-
Valex Korea Co., Ltd.
-
BMT Co., Ltd.
-
FITOK Group
-
KITZ Corporation
-
Kuze Bellows Kogyosho Co., Ltd.
-
King Lai Hygienic Materials Co., Ltd.
-
Dockweiler Systems GmbH
-
Fujikin Incorporated
-
CoreDux B.V.
Ultra High Purity Metal Tubing for Semiconductor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.63 Billion |
| Market Size by 2035 | USD 1.42 Billion |
| CAGR | CAGR of 8.43% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material Grade (316L Stainless Steel, 316LN Stainless Steel, 904L Stainless Steel, Nickel Alloys, and Others) • By Finish (Electropolished (EP), Bright Annealed (BA), and Mechanically Polished) • By Application (Gas Delivery, Chemical and Slurry Delivery, Ultra Pure Water Systems, Vacuum and Exhaust Systems, and Others) • By End User (Foundries, Memory Manufacturers, Logic IDMs, Compound Semiconductor and MEMS Manufacturers, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Swagelok Company, Parker Hannifin Corporation, Ultra Clean Holdings, Inc. (Ham-Let), Entegris, Inc., Alleima AB, Tubacex, S.A., Hy-Lok Corporation, Valex Korea Co., Ltd., BMT Co., Ltd., FITOK Group, KITZ Corporation, Kuze Bellows Kogyosho Co., Ltd., King Lai Hygienic Materials Co., Ltd., Dockweiler Systems GmbH, Fujikin Incorporated, CoreDux B.V. |

Frequently Asked Questions
The key players in the Ultra High Purity Metal Tubing for Semiconductor Market include Swagelok Company, Parker Hannifin Corporation, Ultra Clean Holdings, Inc. (Ham-Let), Entegris, Inc., Alleima AB, among others.
Key opportunities include regional fab programs that need local tube production and finishing, and integrated gas system supply that bundles tubes, fittings, valves and installation services.
The major growth factor is fab construction and higher purity requirements at advanced nodes, which raise the volume and quality of tubing needed per fab.
The 316L Stainless Steel segment dominated the Ultra High Purity Metal Tubing for Semiconductor Market with approximately 62.18% share in 2025, because its low carbon content resists corrosion and takes a very smooth electropolished surface.
Asia Pacific dominated the Ultra High Purity Metal Tubing for Semiconductor Market with a 58.64% share in 2025, supported by the world’s largest concentration of wafer fabs.
