
Distributed Fiber Optic Sensor Market Report Scope & Overview:
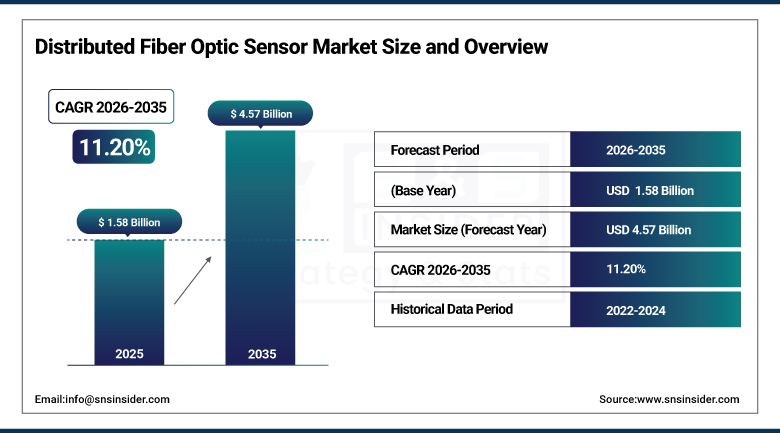
The Distributed Fiber Optic Sensor Market was valued at USD 1.58 Billion in 2025 and is estimated at USD 1.76 Billion in 2026. The market is projected to reach USD 4.57 Billion by 2035, expanding at a CAGR of 11.20% from 2026 to 2035. Distributed fiber optic sensors turn an ordinary optical cable into thousands of measurement points that detect temperature, vibration, sound, and strain along its entire length. Growth is supported by pipeline safety programs, power grid modernization, subsea cable protection, and advances in signal analytics that make long-range monitoring practical.
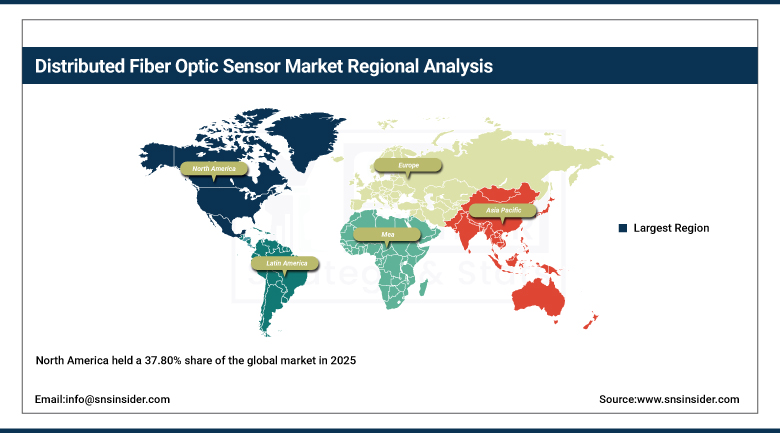
North America dominated the market in 2025 with a share of 37.80%, owing to its well-developed pipeline infrastructure, large base of utilities and high levels of oil and gas activity. This region has been quick to implement acoustic and temperature sensors. Europe has also seen significant growth due to energy transition and infrastructure protection. Asia Pacific is growing fastest as China, Japan, India and Australia are investing in pipelines, rail, power grids and offshore energy. Smaller markets include the Middle East & Africa and Latin America; however, these regions are growing as oil producers and utilities begin to implement permanent monitoring.
To Get more information Distributed Fiber Optic Sensor Market - Request Free Sample Report
Key Report Takeaways
-
By technology, distributed temperature sensing held a 44.80% share in 2025, while distributed acoustic sensing is the fastest growing.
-
By fiber type, single-mode fiber held a 71.60% share in 2025, while multimode fiber is the fastest growing.
-
By scattering principle, Raman held a 38.90% share in 2025, while Brillouin is the fastest growing.
-
By end use, oil and gas held a 38.50% share in 2025, while power and utilities is the fastest growing.
-
By region, North America held a 37.80% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Existing telecom fiber is being reused as a sensor. Interrogators connect to spare strands in buried and subsea communication cables, so operators can monitor ground movement, digging, and cable threats without laying new cable.
Artificial intelligence is changing how signals are interpreted. Machine learning models now classify vibration patterns into events such as digging, vehicles, footsteps, and leaks, which cuts false alarms and reduces the skill needed to run a system.
Power line monitoring is moving from pilots to programs. Utilities use fiber already installed in ground wires and cables to track temperature, sag, and weather loading, which supports dynamic line ratings and higher use of existing lines.
Interrogator range and channel counts are rising. New units reach tens of kilometers and serve several fibers at once, which lowers the cost per kilometer of monitored pipeline, rail, or cable.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Pipeline Integrity and Leak Detection Needs |
+3.46% |
North America, Middle East & Africa |
Long term (4 years or more) |
|
Power Grid Modernization and Cable Monitoring |
+3.02% |
Global |
Medium term (2 to 4 years) |
|
Subsea and Telecom Network Security |
+2.37% |
Europe, Asia Pacific |
Medium term (2 to 4 years) |
|
Well and Reservoir Surveillance |
+1.94% |
North America, Latin America, Middle East & Africa |
Long term (4 years or more) |
|
AI-Based Signal Analytics |
+1.58% |
Global |
Short term (2 years or less) |
|
Fire, Rail, Tunnel, and Perimeter Security |
+1.23% |
Europe, Asia Pacific |
Medium term (2 to 4 years) |
Pipeline Integrity and Leak Detection Needs
Oil, gas, and water pipelines face third-party digging, ground movement, leaks, and theft, and operators must detect incidents quickly to protect people and the environment. Distributed acoustic sensing hears excavators and leaks over many kilometers, while temperature sensing identifies cooling at leak points in liquefied gas and buried lines. Long new crude and gas pipeline programs in several regions are adding monitoring requirements at the design stage. Oil and gas remains the largest end use, and operators increasingly specify continuous monitoring in new contracts and retrofit projects.
Power Grid Modernization and Cable Monitoring
Utilities need more capacity from existing lines, early warning of cable faults, and visibility into heat and weather loading. Fiber embedded in ground wires and power cables allows continuous temperature and strain measurement along the whole route, which supports dynamic line ratings and condition-based maintenance. Offshore wind farms and interconnectors add long subsea power cables whose faults are expensive to repair. Power and utilities is the fastest-growing end use, since transmission operators treat distributed sensing as a low-cost way to raise reliability and defer new construction.
Subsea and Telecom Network Security
Damage to undersea communication and power cables has drawn attention from governments and carriers, who want earlier detection of anchors, dredging, and tampering. Distributed sensing can use spare strands in existing cables to monitor vibration and strain over long distances, so carriers add a monitoring layer without new hardware in the water. On land, telecom operators use the same technique to detect digging near buried routes and to share data with gas and water utilities. These dual-use cases widen the customer base beyond energy companies.
Well and Reservoir Surveillance
Upstream operators use fiber in wells and on the seabed to track hydraulic fracturing, flow profiles, sand production, and reservoir changes over time. Distributed acoustic and temperature measurements give continuous data that point sensors cannot provide, and the information helps engineers optimize stimulation and production. Offshore fields in Brazil, the North Sea, and the Gulf of Mexico invest in permanent reservoir monitoring systems with long cable networks. Service companies license and bundle fiber-based surveillance with their completion and stimulation offerings.
AI-Based Signal Analytics
Raw acoustic data from a long fiber can overwhelm operators, since a single interrogator produces terabytes of data per day. Machine learning models that classify events, learn site noise, and filter false alarms make systems usable by control room staff without specialist training. Edge processing reduces the data sent to central servers, and cloud platforms combine sensor outputs with maps and asset records. Better analytics raise the value of each installation and encourage operators to extend monitoring to more assets.
Fire, Rail, Tunnel, and Perimeter Security
Linear heat detection with fiber survives dust, humidity, and electromagnetic interference in road tunnels, conveyor belts, cable trays, and storage sites where point detectors struggle. Acoustic sensing detects intruders along fences, borders, and railway lines, and rail operators use it to track trains, find rockfalls, and protect infrastructure. Airports, data centers, and critical facilities adopt perimeter systems that integrate with video analytics. Safety rules for tunnels and public transport push owners to adopt continuous monitoring. Insurers often support these upgrades.
Restraints Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Installation and Deployment Costs |
-2.12% |
Global |
Medium term (2 to 4 years) |
|
Physical Range and Signal Attenuation Limits |
-1.57% |
Global |
Long term (4 years or more) |
|
Shortage of Specialist Skills and Substitution Pressure |
-1.19% |
Asia Pacific, Latin America, Middle East & Africa |
Medium term (2 to 4 years) |
|
Project Timing and Funding Constraints |
-0.84% |
North America, Middle East & Africa |
Short term (2 years or less) |
High Installation and Deployment Costs
A distributed system needs interrogator units, specialized cable, installation labor, power, and software, and costs rise further in difficult terrain, offshore sites, and hazardous areas. Retrofitting fiber along existing pipelines can require trenching, and bonding quality affects accuracy. Smaller operators compare these costs with cheaper point sensors and manual patrols, and approvals often wait for the next maintenance cycle. Long payback expectations and limited numbers of specialist component suppliers slow adoption in cost-sensitive markets. Budgets rarely stretch to full coverage.
Physical Range and Signal Attenuation Limits
Light loses strength as it travels along a fiber, and the scattered signals used for sensing are very weak. Interrogators therefore reach a limited distance, typically tens of kilometers for acoustic sensing and shorter for temperature measurement with high resolution, and longer routes need repeaters or multiple units. Bends, splices, and damaged sections add loss and noise. Customers with very long pipelines or subsea routes must plan carefully, which adds engineering effort and equipment cost to projects. Routes beyond range need extra units.
Shortage of Specialist Skills and Substitution Pressure
Installing fiber, calibrating interrogators, and interpreting data requires skills that are scarce in many emerging markets, and mistakes can reduce performance or cause false alarms. Alternative technologies, including pressure-based leak detection, satellite monitoring, drones, cameras, and point sensors, compete for the same budgets, and distributed strain sensing faces especially strong substitution. Operators often run small pilots first, and decisions drift when internal champions are missing. Training programs exist but reach few sites, and vendors must supply expert staff during commissioning.
Project Timing and Funding Constraints
Orders depend on energy company capital budgets, public safety funding, and approvals of large infrastructure projects, all of which can shift with commodity prices and regional conflicts. Projects in sensitive regions may be delayed by security concerns or permitting, and utilities wait for rate case decisions before investing. Suppliers with small order books can see uneven revenue from quarter to quarter, and customers often seek financing or service contracts to spread costs. Cancelled or postponed awards can hurt suppliers badly.
Distributed Fiber Optic Sensor Market Segment Analysis
By Technology, Distributed Temperature Sensing Dominates Distributed Fiber Optic Sensor Market; Distributed Acoustic Sensing to Register Fastest Growth.
Distributed temperature sensing led with a 44.80% share in 2025. It measures temperature along the entire length of a fiber, which suits pipelines, power cables, wells, tunnels, and industrial plants. The technology is mature, accurate, and accepted in standards for fire detection and cable rating, so operators specify it widely. Interrogators are available from many suppliers, and long product lives support steady replacement and expansion orders in oil, gas, and power systems. Replacement cycles keep sales volumes stable.
Distributed acoustic sensing is projected to expand at a CAGR of 14.30% from 2026 to 2035. It listens for vibration and sound along a fiber, detecting digging, leaks, trains, intruders, and seismic signals. Better interrogators, longer ranges, and artificial intelligence classification have widened its use in pipelines, borders, rail, subsea cables, and well monitoring. Reuse of telecom fiber lowers deployment cost, so new customers can start monitoring quickly. Telecom carriers share fiber with gas utilities, widening the customer pool.
By Fiber Type, Single-Mode Fiber Dominates Distributed Fiber Optic Sensor Market; Multimode Fiber to Register Fastest Growth.
Single-mode fiber held 71.60% of the market in 2025. It carries light with low loss over long distances, which is essential for acoustic sensing over tens of kilometers and for pipelines, rail lines, power cables, and subsea routes. The same fiber type is used in telecom networks, so operators can reuse installed cable and source components easily. Interrogators for long-range sensing are designed around single-mode fiber, which keeps it the default choice for most large projects. Costs remain low.
Multimode fiber is projected to expand at a CAGR of 13.20% from 2026 to 2035. It suits shorter links with high temperature resolution, such as wells, tunnels, buildings, industrial plants, and storage tanks, and it works with lower-cost light sources. Fire detection systems and process industries favor it for simple installation and strong signal levels. Growth in safety monitoring for tunnels and facilities, along with compact interrogators, supports wider use. Compact interrogators suit wells and building monitoring projects.
By Scattering Principle, Raman Dominates Distributed Fiber Optic Sensor Market; Brillouin to Register Fastest Growth.
Raman scattering led with a 38.90% share in 2025. It underpins most distributed temperature systems, since the strength of the scattered signal changes directly with temperature, giving reliable readings without strain interference. Oil and gas wells, power cables, fire detection, and industrial heating applications depend on it. The technology is well understood, and standards and field experience give buyers confidence when they specify systems for critical assets across many industries. Training materials also reference it widely across industry.
Brillouin scattering is projected to expand at a CAGR of 13.70% from 2026 to 2035. It allows both strain and temperature measurement over long distances, which suits pipelines, dams, bridges, subsea cables, and geotechnical monitoring. Progress in interrogators has improved spatial resolution and speed, and infrastructure owners value early warning of deformation. Growth in civil engineering and offshore energy projects supports demand, while falling equipment prices broaden access. Suppliers highlight longer ranges and strain accuracy in recent tenders.
By End Use, Oil and Gas Dominates Distributed Fiber Optic Sensor Market; Power and Utilities to Register Fastest Growth.
Oil and gas held 38.50% of the market in 2025. Operators use distributed sensing for pipeline leak and intrusion detection, well and reservoir surveillance, flow assurance, and facility safety. The assets are long, remote, and costly to inspect, and the consequences of failure are severe. Continuous monitoring fits regulatory expectations and company safety standards, and large producers renew and expand systems as new fields and pipelines come on line. Spending also follows new refinery and storage terminal builds.
Power and utilities is projected to expand at a CAGR of 14.60% from 2026 to 2035. Transmission operators use fiber in ground wires and cables to monitor temperature, sag, faults, and ground movement, and offshore wind farms rely on it for subsea cable condition. Dynamic line ratings raise capacity without new towers, and utilities value data for predictive maintenance. Grid investment programs in several regions keep project pipelines full. Utilities in Asia and Europe lead these new projects.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.00% |
|
Europe |
Germany |
31.00% |
|
Asia Pacific |
China |
26.40% |
|
Middle East & Africa |
Saudi Arabia |
43.50% |
|
Latin America |
Brazil |
51.20% |
North America Distributed Fiber Optic Sensor Market
North America held a 37.80% share of the global market in 2025. The United States market was valued at USD 489.74 Million in 2025 and is projected to grow at a CAGR of 11.80% from 2026 to 2035. In January 2025, the Pipeline and Hazardous Materials Safety Administration sent its final rule on gas pipeline leak detection and repair to the Federal Register, a measure that requires advanced leak detection programs and names continuous monitoring among eligible technologies. Canada adds demand through oil sands and long pipelines.
Utility regulation is another support. Since December 2021, the Federal Energy Regulatory Commission has required transmission providers to use ambient-adjusted line ratings and has examined dynamic line ratings, which encourages use of fiber-based temperature and sag monitoring on high-voltage lines. Oil producers in the Permian Basin and the Gulf of Mexico deploy fiber in wells, while railroads and telecom carriers test shared sensing on buried routes. Mexico is covered under Latin America in this study. Gas distributors are also expanding use.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Distributed Fiber Optic Sensor Market
Europe held a 25.20% share of the global market in 2025, with Germany as the leading country, followed by the United Kingdom, France, and Norway. In February 2025, the European Union adopted an action plan on cable security that adds about USD 560.00 Million (EUR 540.00 Million) for 2025 to 2027 under the Connecting Europe Facility, including smart subsea cables able to detect threats. The plan builds on prevention, detection, deterrence, and repair, and favors monitoring of communication and power links.
Offshore wind farms in the North Sea and the Baltic, interconnectors, and gas transmission operators are adopting distributed sensing for cable and pipeline condition. Water and gas utilities in the United Kingdom test acoustic sensing on spare telecom fiber to find leaks and digging, and French and German gas grid operators evaluate it for third-party interference detection. Tunnel and rail operators in the Alps and the Nordic countries use fiber for fire and rockfall detection. Several operators plan wider rollouts.
Asia Pacific Distributed Fiber Optic Sensor Market
Asia Pacific accounted for 27.80% of the global market in 2025 and is the fastest-growing region, with a projected CAGR of 13.40% from 2026 to 2035. China is the leading country, followed by Japan, India, South Korea, and Australia. In August 2026, Japan launched a government-backed demonstration program under the New Energy and Industrial Technology Development Organization to monitor mooring lines of floating offshore wind turbines with optical fiber, part of its Green Innovation Fund projects. Singapore adds subsea monitoring interest.
China is building long oil, gas, and water pipelines, high-voltage transmission corridors, and high-speed rail lines, and domestic suppliers of interrogators and cable compete aggressively on price. India is expanding gas grids, metro systems, and railway safety projects, which creates demand for acoustic and temperature sensing. Australia uses fiber for mining, borders, and pipelines. South Korea and Southeast Asia add subsea cable monitoring and tunnel fire detection. Japanese and Korean utilities also lead adoption of cable temperature monitoring across offshore wind.
Latin America Distributed Fiber Optic Sensor Market
Latin America is a smaller regional market, led by Brazil, followed by Mexico, Argentina, and Colombia. Brazil has deep offshore fields where operators are installing permanent reservoir monitoring systems, and a multi-partner program on the Mero field, valued at about USD 450.00 Million, is building one of the largest fiber networks on the seabed. These projects use hundreds of kilometers of cable and create demand for interrogators, installation vessels, and data analytics services. Offshore Guyana and Suriname also look promising.
Onshore, pipeline operators in Mexico, Argentina, and Colombia use acoustic sensing to guard against theft and tapping, a persistent problem on fuel lines. Utilities modernizing transmission networks and renewable connections show growing interest in cable temperature monitoring. Import costs, limited local integrators, and currency swings slow adoption, so international suppliers partner with regional engineering firms and distributors to reach customers outside the largest projects. Mining operations in Chile and Peru use fiber for tunnel and conveyor fire detection, extending the customer base.
Middle East & Africa Distributed Fiber Optic Sensor Market
The Middle East & Africa region holds a 5.60% share and is expected to grow steadily from a small base. Saudi Arabia and the United Arab Emirates are the main buyers, followed by Qatar, Kuwait, and South Africa. National oil companies in the Gulf operate long crude, gas, and water pipelines across desert terrain and use distributed acoustic and temperature sensing to detect leaks, tampering, and third-party activity, with approved systems specified in operating standards. Oman adds smaller volumes too.
Rail and border security projects add demand, as do new industrial cities, desalination plants, and power interconnectors in the Gulf. Offshore fields in West Africa and the Eastern Mediterranean are evaluating permanent fiber monitoring, and mining firms in South Africa test it for tunnel and conveyor safety. Regional conflicts and project delays create some uncertainty, but oil and gas revenue continues to support spending on asset protection. Pipeline operators in Egypt, Algeria, and Nigeria also test acoustic sensing against theft and leaks.
Competitive Landscape
The Distributed Fiber Optic Sensor Market is moderately concentrated. Luna Sensing Group, which brings together OptaSense, Silixa, and LIOS Technology, Halliburton, Yokogawa Electric, AP Sensing, and Omnisens supply a large share of interrogators, cable systems, and software, while Bandweaver, Neubrex, Prisma Photonics, Febus Optics, and FiberSense compete in specialist applications. Competition rests on range, resolution, analytics, installation expertise, and references.
Vendors are launching interrogators with longer reach and more channels, adding machine learning for event classification, and offering monitoring as a service. Consolidation is under way, since private equity and industrial groups acquire sensing businesses to build broader portfolios. Partnerships with telecom carriers, utilities, and cable makers extend reach into subsea, power, and rail projects.
Distributed Fiber Optic Sensor Market Industry Leaders
1. Luna Sensing Group: OptaSense and Silixa distributed acoustic sensing, iDAS, Carina sensing system, and LIOS temperature and strain systems.
2. Halliburton: fiber-optic well surveillance, including the globally licensed WellSense FiberLine Intervention technology for stimulation monitoring.
3. Yokogawa Electric: DTSX1 Raman temperature sensor and OpreX Subsea Power Cable Monitoring using DTSX.
4. AP Sensing: N56 and N51 acoustic sensing units, N45 and N62 temperature sensing units, and leak detection systems approved for pipelines.
5. Omnisens: fiber sensing systems for pipelines, power cables, subsea routes, reservoirs, and structures.
Companies Covered in this Report
-
Luna Sensing Group
-
OptaSense
-
Silixa
-
LIOS Technology
-
Halliburton
-
Yokogawa Electric
-
AP Sensing
-
Omnisens
-
Bandweaver
-
Neubrex
-
Prisma Photonics
-
Ava Risk Group
-
Viavi Solutions
-
Febus Optics
-
FiberSense
Recent Industry Developments
-
August 2025: FiberSense began a six-month distributed acoustic sensing trial with Openreach, Cadent, Thames Water, and Arcadis in West London to detect leaks and digging.
-
September 2025: Halliburton obtained a global license for WellSense FiberLine Intervention technology for stimulation monitoring.
-
October 2025: Prisma Photonics raised USD 30.00 Million, bringing its total funding to USD 80.00 Million.
-
April 2026: APTelecom and FiberSense expanded their partnership for acoustic monitoring of subsea cables.
-
June 2026: Febus Optics introduced the A1-NEO acoustic interrogator with a range of 5 to 100 km and up to four channels.
-
June 2026: Luna Innovations agreed to be acquired by an affiliate of TJC, L.P.
-
July 2026: Neubrex was selected for a project under the Green Innovation Fund of Japan.
-
September 2026: TJC completed its acquisition of Luna Innovations at USD 1.39 per share, and Silixa, OptaSense, and LIOS Technology began operating under the Luna Sensing Group name.
Scope and Research Methodology
This study covers the Distributed Fiber Optic Sensor Market, which includes distributed acoustic, temperature, and strain sensing systems that use optical fiber as a continuous sensing element, including interrogator units, sensing cables, installation, and analytics software. The base year is 2025, the forecast period is 2026 to 2035, and all values are expressed in USD. The market is segmented by technology, fiber type, scattering principle, end use, and region. Point sensors such as fiber Bragg gratings and discrete interferometric probes are excluded, as are optical fibers sold for telecommunications. Service revenue tied to installed systems is included. Hardware and software sold as packages, and long-term monitoring contracts, are counted at their contract value. Defense and military applications of fiber sensing are included only where commercial systems are used.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with executives, product and business heads, system integrators, pipeline and utility operators, and end-user stakeholders across the value chain. These conversations validate assumptions, adoption rates, and pricing. Project announcements and tender records are reviewed to confirm demand trends. Product datasheets and range specifications are compared across suppliers to verify performance claims and pricing.
Market engineering follows a bottom-up build from interrogator shipments, monitored kilometers, and supplier revenue, which is cross-checked top-down against pipeline, power grid, and well investment. Triangulation across these views confirms segment and regional estimates. Forecasts consider capital budgets, regulation, technology cost curves, and macroeconomic conditions, and every dataset passes an analyst quality review before it is published. Sensitivity checks cover commodity prices, project timing, and component costs. Regional estimates reflect pipeline length, grid investment, and offshore project pipelines, and are adjusted for exchange rates.
Distributed Fiber Optic Sensor Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.58 Billion |
| Market Size by 2035 | USD 4.57 Billion |
| CAGR | CAGR of 11.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Distributed Temperature Sensing, Distributed Acoustic Sensing, and Distributed Strain Sensing) • By Fiber Type (Single-Mode and Multimode) • By Scattering Principle (Raman, Rayleigh, and Brillouin) • By End Use (Oil and Gas, Power and Utilities, Safety and Security, Infrastructure and Civil Engineering, Industrial Manufacturing, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | OptaSense, Silixa, LIOS Technology, Halliburton, Yokogawa Electric, AP Sensing, Omnisens, Bandweaver, Neubrex, Prisma Photonics, Ava Risk Group, Viavi Solutions, Febus Optics, FiberSense |

Frequently Asked Questions
The market was valued at USD 1.58 Billion in 2025 and is estimated at USD 1.76 Billion in 2026. It is projected to reach USD 4.57 Billion by 2035.
The market is projected to grow at a CAGR of 11.20% from 2026 to 2035, supported by pipeline safety, grid modernization, and subsea cable protection.
North America leads, with a 37.80% share in 2025, owing to its extensive pipeline network and strong oil, gas, and utility activity.
Asia Pacific is the fastest-growing region, with a CAGR of 13.40% from 2026 to 2035, driven by pipeline, rail, grid, and offshore energy investment.
Distributed temperature sensing, single-mode fiber, Raman scattering, and oil and gas lead their axes. Distributed acoustic sensing, multimode fiber, Brillouin scattering, and power and utilities grow fastest.
