
Embedded Software Market Report Scope & Overview:
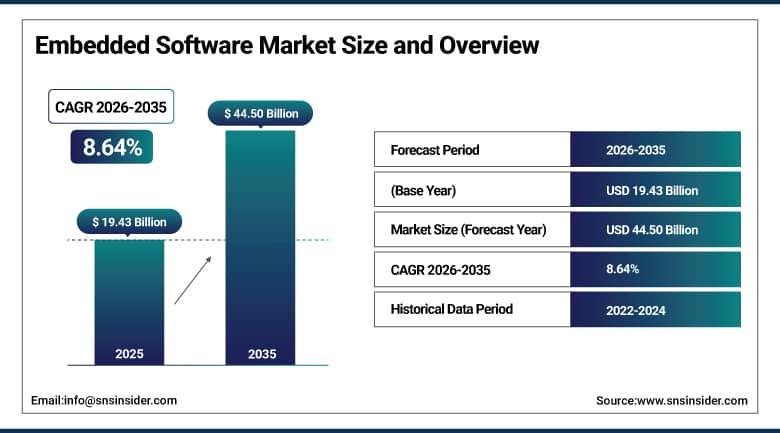
The Embedded Software Market was valued at USD 19.43 Billion in 2025 and is estimated at USD 21.11 Billion in 2026. It is projected to reach USD 44.50 Billion by 2035, advancing at a CAGR of 8.64% from 2026 to 2035. Embedded software is the code that runs inside dedicated devices, including operating systems, middleware, firmware, and development tools, and it controls products ranging from vehicles and factory machines to medical devices and consumer gadgets. Connected devices, software-defined vehicles, and edge intelligence are raising the amount of software in every product. Vendors also sell royalties and support.
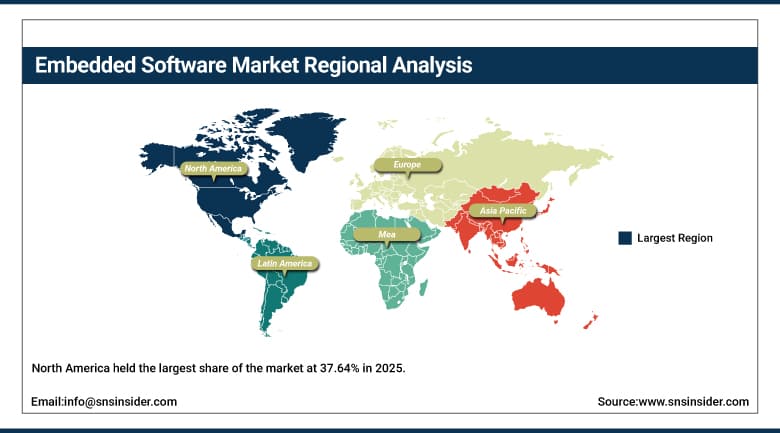
North America represented the highest regional market share of 37.64% in 2025 due to aerospace and defense applications, well-developed semiconductor and software suppliers, and early industrial automation applications. Asia-Pacific is in second place and will register the highest growth during the forecast period due to growing electronics and automotive manufacturing in China, Japan, South Korea, and India. Europe benefits from its automotive and machinery sectors, while Latin America and the Middle East & Africa are adding embedded content through telecom and industrial investment. Local electronics assembly is also expanding.
To Get More Information On Embedded Software Market - Request Free Sample Report
Key Report Takeaways
- By operating system, real-time operating systems held a 41.20% share in 2025, while general-purpose operating systems are the fastest growing.
- By functionality, real-time embedded software accounted for a 38.60% share in 2025, while mobile embedded software is the fastest growing.
- By vertical, consumer electronics represented a 24.70% share in 2025, while automotive is the fastest growing.
- By deployment, on-premise software commanded a 71.80% share in 2025, while cloud and edge deployment is the fastest growing.
- By region, North America led with a 37.64% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
Artificial intelligence is moving into embedded devices. Chip makers and software vendors are packaging inference runtimes, safety-qualified frameworks, and model deployment tools so that cameras, controllers, and vehicles can run machine learning locally.
Software-defined vehicles are changing automotive architecture. Carmakers are consolidating dozens of electronic control units into fewer high-performance computers, which raises demand for hypervisors, standardized middleware, and over-the-air update frameworks.
Open-source and Linux-based platforms are gaining ground beside commercial real-time systems. Zephyr, embedded Linux distributions, and community-maintained kernels are being hardened for certification, and vendors are selling support and compliance services around them.
Security and software supply chain transparency are becoming standard requirements. Software bills of materials, memory-safe languages such as Rust, and automated vulnerability tracking are entering development pipelines as regulators demand proof of secure design.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Growth of Connected Devices and the Internet of Things |
+4.12% |
Global |
Short term (2 years or less) |
|
Software-Defined Vehicles and Advanced Driver Assistance |
+3.18% |
Europe, Asia Pacific, and North America |
Medium term (2 to 4 years) |
|
Industrial Automation and Industry 4.0 Programs |
+2.46% |
Asia Pacific and Europe |
Medium term (2 to 4 years) |
|
Edge Computing and Embedded Artificial Intelligence |
+1.88% |
Global |
Long term (4 years or more) |
|
Cybersecurity Regulation and Standards Compliance |
+1.40% |
Europe and North America |
Medium term (2 to 4 years) |
Growth of Connected Devices and the Internet of Things
Every connected product, from smart meters to wearables and building controllers, needs firmware, an operating system, and communication stacks. Manufacturers are adding wireless connectivity to products that were once standalone, and each new feature raises the amount of code per device. Longer product lifetimes also mean that vendors must maintain and update software for years after shipment. These factors create recurring licensing, support, and tool revenue for embedded suppliers and give the market a broad, steady base of demand across consumer and commercial devices.
Software-Defined Vehicles and Advanced Driver Assistance
Vehicle makers are shifting value from mechanical parts to software that controls driving, safety, and infotainment. In December 2025, the AUTOSAR partnership made its Release R25-11 available, extending the standard architecture that many suppliers use for classic and adaptive platforms. Higher levels of driver assistance require safety-certified operating systems, hypervisors, and middleware that can mix critical and non-critical functions on one computer. These needs lift spending on both commercial real-time systems and Linux-based vehicle platforms. Suppliers also see rising demand from commercial trucks and two-wheelers.
Industrial Automation and Industry 4.0 Programs
Sensors, programmable controllers, and robotics which are being added to factories operate on deterministic embedded systems. According to the International Federation of Robotics in September 2025, 542,000 industrial robots had been installed in 2024 globally. Each robot, drive, and controller runs real-time code and increasingly connects to plant networks. Manufacturers in Asia Pacific and Europe are modernizing lines to raise productivity, which creates demand for industrial operating systems, motion control software, and tools that support long product lifecycles. Training and service contracts add further revenue.
Edge Computing and Embedded Artificial Intelligence
Processing data close to the source reduces latency and bandwidth costs, so more devices now run analytics and machine learning locally. Vendors are releasing runtimes and safety-qualified frameworks that let cameras, robots, and vehicles execute models without cloud connections. This shift enlarges the software stack inside each device and adds demand for containers, orchestration, and secure update tools. Suppliers that combine real-time determinism with artificial intelligence capability are winning design positions in defense, automotive, and industrial programs. Hardware vendors support this shift with accelerators.
Cybersecurity Regulation and Standards Compliance
Regulators are making security a legal requirement for products with digital elements. The Cyber Resilience Act of the European Union comes into effect with respect to manufacturing companies in terms of reporting on 11th September 2026; however, additional requirements will be put into effect in subsequent years. For automotive, medical, and aviation products, safety and security standards need documented development processes and tools as well. This effort results in buying of secure operating systems, vulnerability management, bill of material for software and certification service, and preference is given to companies that have proper evidence package.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Development, Testing, and Certification Costs |
-1.58% |
Global |
Short term (2 years or less) |
|
Hardware and Software Integration Complexity |
-1.24% |
Global |
Medium term (2 to 4 years) |
|
Shortage of Skilled Embedded Engineers |
-0.96% |
Global |
Medium term (2 to 4 years) |
|
Cybersecurity Risk and Open-Source Licensing Complexity |
-0.62% |
Global |
Long term (4 years or more) |
High Development, Testing, and Certification Costs
Embedded products have to undergo testing on their target hardware, and for safety-critical products, there is a need for formal verification and process documentation. The FDA in the USA revised its pre-market cybersecurity guidance for medical devices in February 2026, increasing the work for device manufacturers in terms of documentation and testing. The process of certification according to standards used in the automobile industry, aviation industry, or other industries takes months and uses qualified tools. Small manufacturers do not find it easy to bear such costs, so they either reduce scope or use less expensive open source.
Hardware and Software Integration Complexity
Embedded software is tightly coupled to processors, memory, sensors, and peripheral devices, and each hardware change can require new drivers and testing. Legacy products built on older chips and proprietary kernels are expensive to port. Mixed-criticality platforms, where safety and non-safety functions share one processor, add architectural complexity. These challenges lengthen development schedules, raise engineering effort, and make it harder for customers to switch suppliers or adopt new platforms quickly. Customers also hesitate to replace stable code, because regression testing across many device variants can take months and requires specialized equipment.
Shortage of Skilled Embedded Engineers
For embedded development to be successful, experts need people who have knowledge about low-level programming, real-time capabilities, hardware interface, and safety standards. However, there are fewer graduates at universities who possess such qualities compared to the demand of the companies, and competition with cloud and application software developers makes the salaries even higher. Training of the staff, outsourcing, and use of modeling approaches is the reaction of businesses to those challenges, but project delays may occur due to the lack of professionals in the niche. The shortage affects product launches of manufacturers as well as vendor's ability to provide customization.
Cybersecurity Risk and Open-Source Licensing Complexity
Connected devices expand the attack surface, and flaws in firmware can remain in the field for years. Cybersecurity and Infrastructure Security Agency and National Security Agency issued joint guidance in June 2025 to address security risks related to memory, thus pointing out the challenges in the security of legacy code. The open source components have licensing requirements that need to be managed, and each component has to be traced in terms of its origin. Some companies keep sensitive modules in-house to limit exposure, which increases engineering workload and reduces reuse across product lines.
Embedded Software Market Segment Analysis
By Functionality, Real-Time Embedded Dominates Embedded Software Market; Mobile Embedded to Register Fastest Growth.
Real-time embedded software accounted for a 38.60% share in 2025 because its use spans automotive control, industrial automation, aerospace, and medical equipment, where timing and reliability are essential. These applications demand rigorous testing and often require certified components, which raises the value of each software license. Customers tend to reuse validated code across product generations, so suppliers with established platforms benefit from recurring royalties, maintenance fees, and upgrade projects. Long service lives for machines add further recurring revenue.
Mobile embedded software is expected to register the fastest growth, with a CAGR of 9.86% from 2026 to 2035. Smartphones, tablets, wearables, handheld scanners, and portable medical tools require power-efficient code, rich interfaces, and frequent updates. Rising device volumes in Asia Pacific and the spread of low-power wireless links support this segment. Standalone and networked embedded software also grow steadily, as connected appliances and building systems add communication stacks and remote management features. Vendors price these products by volume.
By Operating System, Real-Time Operating System Dominates Embedded Software Market; General-Purpose Operating System to Register Fastest Growth.
Real-time operating systems held a 41.20% share in 2025 because many embedded products must respond within fixed time limits, including braking controllers, flight systems, medical devices, and industrial drives. These systems offer deterministic scheduling, small memory footprints, and safety certification evidence that general-purpose systems often lack. Long design cycles keep customers with proven suppliers, which sustains revenue from licenses, support contracts, and tools across the installed base. Defense and aerospace programs rely heavily on this category and on its suppliers.
General-purpose operating systems, including embedded Linux, are expected to register the fastest growth, with a CAGR of 9.42% from 2026 to 2035. Devices with graphical interfaces, networking, and artificial intelligence workloads need rich software ecosystems, and open-source communities supply drivers and frameworks at low cost. Vendors add certification, security patching, and long-term support to make these systems suitable for industrial and vehicle platforms. Proprietary and bare-metal software retains a base in simple, low-cost devices. Chip vendors also publish reference designs.
By Vertical, Consumer Electronics Dominates Embedded Software Market; Automotive to Register Fastest Growth.
Consumer electronics held a 24.70% share in 2025 because televisions, appliances, wearables, cameras, gaming devices, and smart speakers ship in very large volumes and each contains firmware, an operating system, and connectivity software. Short product cycles require frequent software revisions, and brands compete on features that are delivered through code. Manufacturers in Asia Pacific purchase tools and platforms at scale, which gives this vertical the largest share of spending. Retail channels also demand quick turnarounds from suppliers. Pricing is sensitive.
Automotive is expected to register the fastest growth, with a CAGR of 9.96% from 2026 to 2035. Electrification, driver assistance, connected services, and centralized vehicle computers are multiplying software content per vehicle. Suppliers sell operating systems, hypervisors, AUTOSAR stacks, and development tools to carmakers and component makers. Industrial automation, telecommunications, healthcare, and aerospace and defense also expand, but vehicles show the steepest rise in code volume and platform consolidation. Suppliers also gain from long program lives and platform reuse.
By Deployment, On-Premise Dominates Embedded Software Market; Cloud and Edge to Register Fastest Growth.
On-premise adoption had a market share of 71.80% in 2025 due to the fact that the embedded software code needs to be compiled, validated, and executed using hardware within the product, and defense, aerospace, and automotive clients tend to control where the software code and tools can be used. The licensed OS, compiler, and debugger are deployed within the same environment, and all certification evidence is linked with the particular tool version. This ensures that the majority of spending remains with the on-premise model.
Cloud and edge deployment is expected to register the fastest growth, with a CAGR of 13.22% from 2026 to 2035. Development teams are moving build, simulation, and testing workloads to hosted environments, and virtual hardware models let engineers start work before silicon arrives. Over-the-air update platforms and fleet management tools also run in the cloud. Subscription pricing is spreading among vendors, which gradually shifts revenue from perpetual licenses toward recurring service fees. Chip makers also host reference designs there.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.40% |
|
Asia Pacific |
China |
41.36% |
|
Europe |
Germany |
34.78% |
|
Middle East & Africa |
Saudi Arabia |
27.54% |
|
Latin America |
Brazil |
43.62% |
North America Embedded Software Market
North America held the largest share of the market at 37.64% in 2025, supported by aerospace and defense programs, strong semiconductor and software vendors, and early adoption of industrial automation. The United States accounted for most regional demand, with a 2025 value of USD 6.03 Billion, and is expected to grow at a CAGR of 7.44% from 2026 to 2035. Canada adds demand through its automotive, telecom, and mining equipment sectors. Demand is broad-based across industries. Innovation hubs in Texas, California, and Ontario support start-ups.
Defense and space contractors buy safety-certified operating systems and hypervisors for avionics and mission systems. Automotive suppliers in the region are investing in software-defined vehicle platforms, while medical device makers need secure, documented software. Many leading embedded vendors are headquartered here, and venture-backed firms add competition in edge artificial intelligence and open-source support services across industrial and consumer products. Leading chip makers headquartered here also fund software ecosystems that support their processors, which keeps design wins tied to vendor tools and long-term support contracts for customers.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Embedded Software Market
Asia Pacific is expected to be the fastest-growing regional market, with a CAGR of 9.78% from 2026 to 2035. China, Japan, South Korea, and India host large electronics, automotive, and machinery industries, and they are building domestic software capability alongside imported platforms. Rising vehicle output, factory automation, and smartphone and appliance production keep the demand for operating systems, firmware, and tools high. Competition among local suppliers is intense, and pricing remains an important factor in purchasing decisions for consumer products.
China is the biggest national market with high demand from electric vehicle manufacturers and consumer device brands. Japan is contributing automotive and industrial controllers to the supply chain, while South Korea is contributing memory, display, and handsets volumes. India’s electronics manufacturing and software services market segments are developing rapidly. Local operating systems and open-source projects are gaining ground, and governments support semiconductor programs that increase demand for embedded tools. Taiwan and Southeast Asian economies add contract manufacturing volume that supports demand for tools and licenses.
Europe Embedded Software Market
Europe is a mature market shaped by its automotive, machinery, and aerospace industries. Germany, France, the United Kingdom, and Sweden account for most regional spending, and the region is home to several leading automotive software suppliers. Standards bodies and consortia based in the region define widely used architectures, which keeps European vendors influential in vehicle platforms and industrial controllers across global supply chains. Scandinavian and Dutch firms also contribute through industrial automation and semiconductor equipment programs. Industry clusters in Bavaria and Baden-Württemberg anchor demand.
Regulations have an immense impact; those regarding product cybersecurity, functional safety, and data protection require documented development and security. Automotive companies are developing central computer systems and internal software divisions, whereas industries are digitizing their production facilities using smart controllers. Open source is being utilized extensively, and there is governmental funding for software that is safe and independent, although procurement by countries hampers big transnational endeavors. Several nations also fund cross-border research projects on safety-critical software and trusted computing. Pricing discipline remains a priority for buyers.
Middle East & Africa Embedded Software Market
The Middle East & Africa region holds a small share, yet Gulf countries are investing in smart infrastructure, telecom networks, energy systems, and defense programs that use embedded software. The Saudi Arabia and the UAE are the largest spenders in the region, and this is usually via major national projects that require connected devices and control systems. South Africa is still the largest market in the sub-Saharan region for mining and industrial machinery. Other small volume producers include Egypt, Turkey, and Israel that use programs for defense electronics and telecom equipment. Regional free zones become attractive for assembling over time.
Limited local manufacturing leads to the fact that the majority of the embedded software is sold into the region in imported equipment. This is why the demands are formed by the global manufacturers and system integrators. There is a continuous demand for smart city, utility metering, and oil and gas automation projects. The development will be continuous from a low base. Training programs with universities and global vendors are slowly building a local engineering base for embedded development. Pilot projects often precede large rollouts.
Latin America Embedded Software Market
Latin America is a developing market, with Brazil and Mexico accounting for most spending. Automotive assembly plants, appliance manufacturers, and agricultural equipment makers use embedded software in locally built products, and telecom and utility operators deploy connected meters and network devices. Most platform decisions are made by global parent companies, so regional demand follows the plans of multinational manufacturers operating there. Mexico also hosts large electronics and vehicle assembly sites that import software from global parents and add local testing work.
Budget limits and currency swings slow adoption, and local engineering talent is concentrated in a few cities. Argentina, Colombia, and Chile add demand through mining, energy, and consumer electronics assembly, and regional integrators partner with global vendors to supply and support tools. Government programs for digital industry and electric mobility are creating openings for firmware development and testing services across the region. Telecom operators and utilities in the region are expanding smart metering programs, which creates additional volumes of connected devices and supporting firmware.
Competitive Landscape
The competitive landscape is fragmented, with specialist real-time operating system vendors, automotive software suppliers, tool and compiler makers, semiconductor companies with software divisions, and open-source communities. Leading suppliers compete on safety certification, determinism, processor support, security, and the quality of their tools, while newer entrants compete on open-source economics and artificial intelligence enablement. No firm holds a dominant share, because customers combine software from several sources.
Strategies center on certification for new standards, partnerships with chip makers, support for RISC-V and new processor families, and offerings that combine commercial platforms with open-source components. Companies are also investing in virtual development tools, security and software bill of materials capabilities, and artificial intelligence runtimes. Smaller firms differentiate through specialized safety-critical products and responsive engineering support.
Embedded Software Market Industry Leaders
1. Wind River: Provider of the VxWorks real-time operating system, Wind River Linux, and eLxr Pro, serving aerospace, industrial, automotive, and medical customers as an Aptiv company.
2. Green Hills Software: Developer of the INTEGRITY real-time operating system and associated compilers and tools for safety and security critical systems.
3. BlackBerry QNX: Supplier of operating systems, hypervisors, middleware, and tools for software-defined vehicles and other safety-critical embedded products.
4. Elektrobit: Automotive software company offering AUTOSAR products and the EB corbos Linux platform for vehicle computers.
5. Vector Informatik: German supplier of the MICROSAR AUTOSAR basic software and the CANoe development and test tools for automotive electronics.
Companies Covered in this Report
- Wind River
- Green Hills Software
- BlackBerry QNX
- Elektrobit
- Vector Informatik
- ETAS
- SYSGO
- Lynx Software Technologies
- IAR
- Arm
- MathWorks
- Synopsys
Recent Industry Developments
- September 2025: Wind River announced an edge artificial intelligence collaboration covering VxWorks, Wind River Linux, and eLxr Pro.
- December 2025: IAR announced RISC-V toolchain support for automotive electronics.
- April 2026: Lynx Software Technologies launched MOSA.ic.AI, a platform for deterministic artificial intelligence in safety-critical systems.
- May 2026: Green Hills Software introduced a safety and security software foundation for next-generation adaptive system-on-chip devices.
- July 2026: SYSGO released ELinOS 8, an industrial Linux distribution for embedded systems.
- August 2026: Arm licensed its Keil MDK development tools to a microcontroller maker.
- September 2026: MathWorks released version R2026b of MATLAB and Simulink.
- October 2026: Elektrobit introduced pre-integrated AUTOSAR solutions for microcontroller platforms.
Scope and Research Methodology
This report defines the Embedded Software Market as the commercial value of operating systems, middleware, firmware, communication stacks, development tools, and related licensing, royalty, and support services sold for use inside dedicated electronic devices. Embedded hardware, semiconductors, and general enterprise software are excluded. Values are stated in USD at vendor selling prices, including subscription and royalty revenue. The base year is 2025 and the forecast runs from 2026 to 2035. Application software that runs on general computers and servers is excluded unless it is shipped inside a dedicated device, and the estimate covers licenses sold in all regions.
Primary research comprised interviews with embedded engineering managers, automotive software architects, industrial controls designers, procurement officers, system integrators, and executives at operating system and tool vendors. Secondary research drew on regulatory notices, standards body releases, company filings, product documentation, developer surveys, and industry association publications. Shipments were linked to vehicle, robot, and device volumes in each country, then converted to value using licensing and royalty rates. Each interview followed a structured guide covering product roadmaps, platform choices, certification effort, pricing, and adoption barriers, and responses were coded by region and vertical so that patterns could be compared across countries and company sizes.
A bottom-up build by operating system, vertical, and country was cross-checked against a top-down view based on electronics and software spending. Forecasts apply growth rates by segment that reflect product cycles, regulatory change, and pricing trends, with scenarios for automotive production and cybersecurity rules. Regional shares were validated against manufacturing output and design activity, and the five regions sum to the global figure. Findings were reviewed by internal analysts and external experts before release. Where estimates differed, analysts revisited assumptions on royalty rates and unit volumes and consulted additional experts until the figures converged on a single view. Documentation is retained for audit.
Embedded Software Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 19.43 Billion |
| Market Size by 2035 | USD 44.50 Billion |
| CAGR | CAGR of 8.64% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Operating System (Real-Time Operating System, General-Purpose Operating System, and Others) • By Functionality (Real-Time Embedded, Standalone Embedded, Networked Embedded, and Mobile Embedded) • By Vertical (Consumer Electronics, Automotive, Industrial Automation, Telecommunications, Healthcare, Aerospace and Defense, and Others) • By Deployment (On-Premise and Cloud and Edge) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Wind River, Green Hills Software, BlackBerry QNX, Elektrobit, Vector Informatik, ETAS, SYSGO, Lynx Software Technologies, IAR, Arm, MathWorks, Synopsys |

Frequently Asked Questions
The market was valued at USD 19.43 Billion in 2025 and is estimated at USD 21.11 Billion in 2026. It is forecast to reach USD 44.50 Billion by 2035.
The market is projected to expand at a CAGR of 8.64% from 2026 to 2035.
North America led with a 37.64% share in 2025, while Asia Pacific is the fastest-growing region, with a CAGR of 9.78% from 2026 to 2035.
Real-time operating systems held the largest share, at 41.20% in 2025, while general-purpose operating systems are expected to grow fastest.
Automotive is expected to record the fastest growth, with a CAGR of 9.96% from 2026 to 2035.
Connected devices, software-defined vehicles, industrial automation, edge computing with embedded artificial intelligence, and cybersecurity regulation.
High development and certification costs, integration complexity, a shortage of skilled engineers, and cybersecurity and open-source licensing risks.
