
Hedge Fund Market Report Scope & Overview:
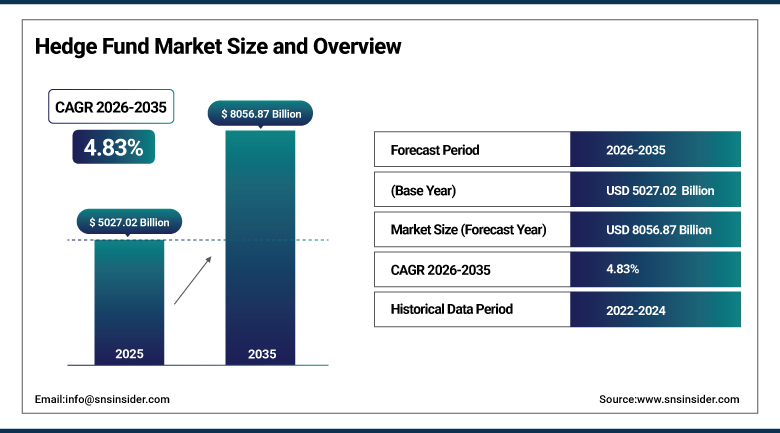
The Hedge Fund Market was valued at USD 5,027.02 Billion in 2025 and is expected to reach USD 8,056.87 Billion by 2035, growing at a CAGR of 4.83% from 2026-2035.
The Hedge Fund Market is growing as pension funds, endowments, sovereign wealth funds and family offices increase allocations to strategies that aim to deliver returns uncorrelated with traditional equity and bond markets. Industry assets have been lifted by net inflows into multi-strategy platforms, rising market values and the entry of established asset managers into liquid alternatives. Concentration is increasing, with a small number of large managers holding a growing share of assets and recruiting teams of portfolio managers. Managers are investing in data science, execution technology and private credit capabilities to widen their opportunity sets. Regulators continue to monitor leverage, liquidity and reporting. North America remains the largest center.
⮞In January 2024, the International Organization of Securities Commissions reported that 2,468 qualified hedge funds in its survey held USD 4.4 trillion in net asset value at the end of 2022, with gross leverage of 10.3 times net asset value. The data established a regulatory baseline for the scale and risk profile of the global industry.
To Get more information Hedge Fund Market - Request Free Sample Report
Hedge Fund Market Trends
-
Multi-strategy platforms are capturing a rising proportion of new institutional allocations.
-
Managers are expanding into private credit and asset-based finance alongside liquid strategies.
-
Artificial intelligence and alternative data are being embedded in research and execution workflows.
-
Regulators are focusing on leverage, repo funding and central clearing of relative value trades.
-
Dubai, Singapore and Hong Kong are competing to host new managers and fund launches.
U.S. Hedge Fund Market Outlook
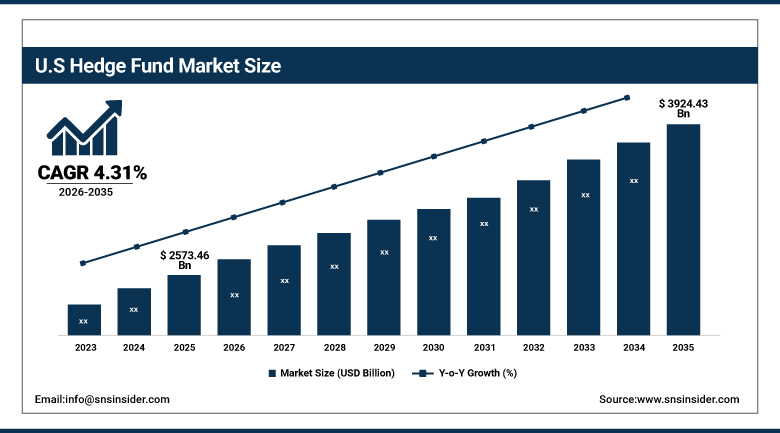
The U.S. Hedge Fund Market was valued at USD 2,573.46 Billion in 2025 and is expected to reach USD 3,924.43 Billion by 2035, growing at a CAGR of 4.31% from 2026-2035.
The U.S. Hedge Fund Market is the deepest pool of hedge fund capital and talent, supported by the concentration of prime brokerage services, institutional investors and leading managers in New York, Connecticut, Chicago and Texas. Public pension plans, endowments and foundations are the principal allocators, and many have raised targets for absolute return strategies after periods of equity and bond volatility. Multi-manager platforms compete aggressively for portfolio managers, which has pushed compensation higher and produced a steady flow of spin-outs and seeded launches. Regulators oversee the industry through Form PF reporting and private fund adviser rules, and a rising share of assets sits in credit and asset-based finance vehicles. Growth is moderate yet resilient, reflecting the scale of the base.
⮞In June 2026, the Federal Reserve Board reported in its Financial Accounts that U.S. hedge funds held USD 3.44 trillion in total financial assets at the end of 2025. The figure confirms the scale of the sector within the United States financial system.
Hedge Fund Market Segment Analysis
-
By Strategy, the Long/Short Equity segment dominated the Hedge Fund Market with approximately 40.81% share in 2025, while the Global Macro segment is the fastest growing with a CAGR of approximately 5.73%.
-
By Investor Type, the Institutional Investors segment dominated the Hedge Fund Market with approximately 51.88% share in 2025, while the Family Offices segment is the fastest growing with a CAGR of approximately 6.35%.
-
By Fund Domicile, the Offshore segment dominated the Hedge Fund Market with approximately 47.86% share in 2025, and is also the fastest growing with a CAGR of approximately 5.17%.
-
By Fund Structure, the Closed-End segment dominated the Hedge Fund Market with approximately 66.93% share in 2025, while the Open-End segment is the fastest growing with a CAGR of approximately 5.64%.
By Strategy, Long/Short Equity Dominates the Hedge Fund Market and Global Macro Grows Fastest
Long and short equity strategies remain the largest category because they are easy for investors to understand, can be run at scale with deep liquidity and have a long track record of attracting capital. Managers combine fundamental research with systematic signals to build portfolios that seek returns from stock selection rather than market direction. Large platforms have created sector-specialist pods that deploy leverage under strict risk limits, and the approach benefits from prime brokerage financing and rich data on company fundamentals. Strong equity market dispersion has supported manager performance, and new units continue to be formed by established firms and by spin-outs from large platforms.
Global macro is progressing fastest as rate volatility, shifting inflation regimes and geopolitical shocks create opportunities across currencies, commodities and sovereign debt. Macro managers trade futures, options and swaps and can adapt quickly to central bank decisions and trade policy changes. Allocators value the strategy as a diversifier when equities and bonds fall together. Derivative exposure is high in this category, so regulators watch leverage closely, which shapes how managers structure funds. Multi-strategy firms also allocate more capital to macro teams, and event-driven, relative value and managed futures strategies share in the broader rise of alternative allocations.
⮞In October 2025, Balyasny Asset Management was reported to be building an internal equities unit able to deploy up to USD 15 billion in leveraged capital, with at least 13 senior hires from competing firms. The unit illustrates continuing platform investment in equity long and short strategies.
By Investor Type, Institutional Investors Dominates the Hedge Fund Market and Family Offices Grows Fastest
Institutional investors supply the majority of capital, led by public and corporate pension plans, endowments, foundations, insurers and sovereign wealth funds. These investors use hedge funds to reduce portfolio volatility, add returns that do not depend on market direction and meet long-term liability needs. Large allocators prefer managers with established risk systems, audited track records and operational transparency, which favors big platforms and established firms. Consultants and in-house investment teams conduct detailed due diligence, and the resulting commitments tend to be large and sticky. Fee negotiations are common, with some institutions securing lower management fees and pass-through arrangements.
Family offices are growing fastest because wealth creation in technology, finance and private business has expanded the number of single and multi-family offices with the resources to access hedge fund strategies directly. They tend to be flexible about lock-up terms, interested in co-investment and open to emerging managers that institutions may avoid. Offices in Asia and the Gulf are building alternative portfolios as they professionalize. High-net-worth individuals reach hedge funds through private banks and feeder vehicles, while funds of funds and retail-oriented liquid alternatives serve smaller investors. Competition for these clients has encouraged managers to open dedicated wealth distribution teams.
By Fund Domicile, Offshore Dominates the Hedge Fund Market and Also Grows Fastest
Offshore domiciles hold the largest portion of assets because they offer tax-neutral structures that suit global investors, including pension funds and endowments that are exempt from U.S. taxes or prefer pooled vehicles with predictable treatment. The Cayman Islands, Ireland, Luxembourg, Bermuda and the British Virgin Islands provide established legal frameworks, experienced administrators, auditors and directors, and regulators that are recognized by major allocators. Master-feeder arrangements allow managers to run one portfolio for both U.S. taxable and non-U.S. investors, and the infrastructure of service providers around these centers reduces launch costs and time.
The offshore segment continues to expand as new launches use these jurisdictions to reach global capital, and as hubs update rules to remain competitive. Regulators in major centers have introduced economic substance, anti-money-laundering and reporting requirements to align with international standards, which has strengthened credibility with investors. Onshore structures remain important for U.S. taxable investors and for products sold to local retail and institutional clients, particularly in Europe through regulated fund wrappers. Competition between domiciles focuses on speed of authorization, service quality, cost and the availability of skilled professionals.
⮞In July 2026, the Cayman Islands Monetary Authority reported that 31,145 funds were registered at the end of the second quarter of 2026, up from 30,598 at the end of 2025, with 547 added in the first half. The registration data shows continued demand for the leading offshore hub.
By Fund Structure, Closed-End Dominates the Hedge Fund Market and Open-End Grows Fastest
Closed-end and limited-liquidity structures account for the larger share because they allow managers to hold less liquid positions, apply lock-up periods and limit redemptions that could force asset sales in stressed markets. These features match the needs of credit, distressed, event-driven and activist strategies that depend on patient capital. Institutional investors accept longer notice periods in return for access to differentiated opportunities and, in some cases, lower fees. Gates, side pockets and investor-level redemption limits are common tools. The structure also supports the move of hedge fund managers into private credit and asset-based finance, which require committed capital.
Open-end structures are growing faster as managers respond to demand for liquidity from smaller institutions, wealth platforms and retail-oriented channels. Regulated formats in Europe and the United States, including funds that follow liquid alternative rules, offer daily or weekly dealing and a familiar legal wrapper. Technology for investor onboarding and reporting has lowered the cost of serving smaller accounts. Regulators set limits on leverage and liquidity for these vehicles, which shapes the strategies they can run. The balance between liquidity and return is a central design question as the industry widens its client base.
⮞In April 2026, the transposition deadline for the revised Alternative Investment Fund Managers Directive passed, and alternative investment funds constituted on or after that date must fully comply with its liquidity management and loan origination rules. The directive sets the structural framework for European fund vehicles.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
89.17% |
|
Europe |
United Kingdom |
41.63% |
|
Asia Pacific |
Hong Kong |
34.58% |
|
Latin America |
Brazil |
58.37% |
|
Middle East and Africa |
United Arab Emirates |
47.92% |
North America Hedge Fund Market Insights
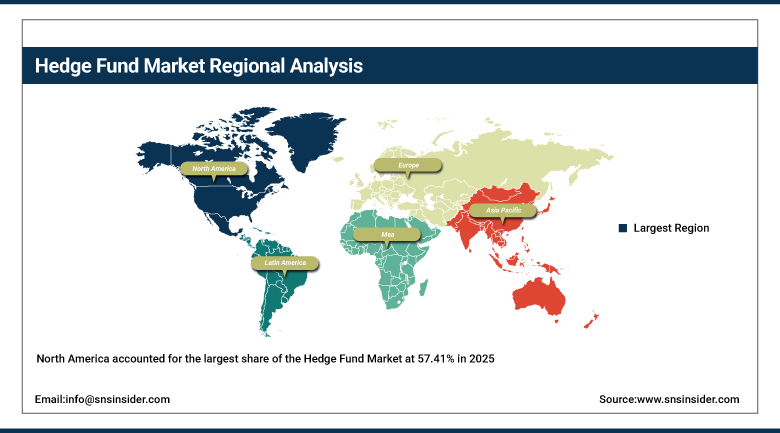
North America accounted for the largest share of the Hedge Fund Market at 57.41% in 2025, supported by the world's deepest institutional investor base, leading prime brokers and a long record of manager formation. The United States hosts most of the largest multi-strategy and quantitative firms, and Canada adds a smaller group of managers and pension allocators. Capital markets depth, access to talent from top universities and the concentration of financial technology providers make the region the natural home for new platforms. Public pension plans and endowments remain the key sources of capital.
Competition for talent shapes economics. Multi-manager firms recruit portfolio managers with guaranteed capital and aggressive compensation, and managers are building large internal teams across equities, credit and macro. Private credit and asset-based finance are growing parts of the portfolio, funded by closed-end vehicles. Regulatory oversight continues through reporting rules and adviser requirements, and political debate on private fund regulation affects compliance planning. Investors are also demanding more transparency on fees, leverage and liquidity, which influences how managers market new strategies.
⮞In November 2025, Point72 Asset Management said it would split its equities teams from 1 January 2026 into Point72 Equities and a new unit named Valist Asset Management, citing assets that had grown from about USD 11 billion after its 2018 relaunch to about USD 41.5 billion. The reorganization shows large firms reorganizing to deploy rising capital.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Hedge Fund Market Insights
Europe is a large and mature market with London as its principal center and with important hubs in Dublin, Luxembourg, Paris, Zurich and the Nordic countries. The region is a leading home of quantitative and macro managers, and many global platforms operate European offices to access local talent and investors. Regulated fund formats provide access for institutional and wealth clients, and Ireland and Luxembourg serve as distribution centers for funds sold across borders. Pension funds in the Netherlands, the Nordic region and the United Kingdom allocate to hedge funds, though many are cautious about fees.
Regulation is a defining feature. The revised alternative investment fund managers framework introduces liquidity management tools and loan origination rules, while supervisors examine leverage in government bond repo markets and the use of derivatives by funds. Brexit created separate regulatory perimeters in the United Kingdom and the European Union, and managers often maintain entities in both. Growth is moderate, supported by multi-strategy expansion and new launches, though sentiment can be affected by supervisory attention to financial stability and by competition from managers in other regions.
⮞In November 2025, the European Central Bank reported in its Financial Stability Review that UCITS hedge funds account for about 30% of the euro area hedge fund sector by assets, and that gross derivatives exposure reaches up to 12 times equity in categories such as global macro. The analysis shows how leverage and fund wrapper choices shape regulatory attention.
Asia Pacific Hedge Fund Market Insights
Asia Pacific is the fastest growing region, with a projected CAGR of 6.24% from 2026-2035, supported by wealth creation, deepening capital markets and active efforts by Hong Kong, Singapore, Japan and Australia to attract managers. Hong Kong remains the principal center for Greater China strategies, and Singapore has built a base of single-family offices and multi-strategy platforms. Japan's market has benefited from corporate governance reform, which creates opportunities for event-driven and activist approaches. Australia hosts a growing set of equity and macro managers serving superannuation funds.
Global platforms are expanding in the region to gain access to talent and local alpha, opening offices and seeding funds run by regional portfolio managers. Tax incentives, simplified fund regimes and support for family offices are improving competitiveness. Regional investors, including sovereign funds and pension plans, are raising alternatives allocations. Obstacles include market access limits in some countries, restrictions on short selling and the cost of operating across several regulatory jurisdictions. Even so, the pace of new launches and the scale of regional wealth suggest the strongest growth over the forecast horizon.
⮞In July 2026, the Hong Kong Securities and Futures Commission reported that total assets under management in Hong Kong reached a record US$5.4 trillion at the end of 2025, up 20%, with net fund inflows of US$265 billion. The record underlines the city's role as a regional asset management hub.
MEA and Latin America Hedge Fund Market Insights
The Middle East and Africa is led by the United Arab Emirates, where Dubai and Abu Dhabi have created dedicated regulators, common-law courts and incentive programs to attract global managers. Saudi Arabia, Qatar and Bahrain are developing their own frameworks, and sovereign wealth funds in the Gulf are important allocators to hedge funds. South Africa has the continent's most established manager base. Interest from global platforms is rising because of the region's wealth, favorable tax conditions and proximity to emerging market opportunities, though the market remains small compared with other regions.
⮞In July 2025, the Dubai International Financial Centre reported that the number of hedge funds in the centre rose from 50 to 85 in the first half of 2025, as the number of wealth and asset managers there rose from 370 to 440. The growth shows the pull of Gulf hubs for new launches.
Latin America is led by Brazil, with Mexico, Chile, Argentina and Colombia contributing smaller markets. Mexico forms part of this regional scope. Brazil's multimercado funds, which combine macro and multi-strategy approaches, hold a substantial share of local fund assets and have faced redemptions during periods of high interest rates. Local pension funds and wealthy families are the main investors, while international managers trade regional currencies and rates through offshore vehicles. High interest rates, currency volatility and regulatory changes create both opportunities and constraints for managers in the region.
⮞In January 2026, the Brazilian Financial and Capital Markets Association reported that net inflows to the country's investment funds fell 28.48% in 2025, while multimercado funds recorded net redemptions for the second consecutive year. The data shows pressure on the local hedge-fund-like category.
Growth Drivers: Institutional Allocations and Emerging Manager Launches Drive Growth in the Hedge Fund Market
Institutional investors continue to raise allocations to hedge funds as they search for diversification and income sources beyond traditional asset classes. Pension plans facing funding targets, endowments seeking stable returns and sovereign funds managing large reserves all view hedge funds as part of a broader alternatives allocation. Strong performance by multi-strategy and quantitative managers in volatile markets has reinforced this stance, and consultants have encouraged clients to widen their manager lists. New capital tends to flow to large firms with deep risk infrastructure, but it also supports mid-sized specialists.
A steady stream of launches adds to growth. Experienced portfolio managers leave large platforms to start their own firms with seed capital from allocators and from the platforms themselves. Technology reduces the cost of establishing operations, because administrators, prime brokers and cloud-based data services offer ready infrastructure. Industry groups track the emerging manager community as a source of innovation, and many allocators run dedicated emerging manager programs. This renewal keeps the competitive landscape active and expands the range of strategies available to investors over the forecast period.
⮞In 2026, the Alternative Investment Management Association published an emerging manager survey based on 180 hedge fund manager responses and 50 investor responses, in which 85% of manager respondents ran up to USD 500 million. The survey highlights the large population of smaller managers entering the industry.
Restraints: Leverage Scrutiny and Fee Pressure Restrain Growth in the Hedge Fund Market
Supervisors are paying closer attention to leverage in hedge funds, particularly in relative value trades funded through repurchase agreements in government bond markets. Concentration of such leverage among a small number of funds raises concerns that forced unwinds could disrupt market liquidity. Proposals for wider central clearing, minimum haircuts and enhanced reporting would raise costs and may reduce the returns available from these strategies. Prime brokers have also tightened financing terms after past episodes of stress, which affects funds that rely on high leverage.
Fee pressure is a second constraint. Investors have negotiated lower management and performance fees, and large allocators increasingly demand pass-through expense models, which compresses margins at smaller managers. Competition from private credit funds, liquid alternatives and passive strategies draws capital from traditional hedge fund approaches. Dispersion in manager performance means that weaker funds face redemptions, and operational costs for data, compliance and technology continue to rise. Together these forces concentrate assets in a smaller group of successful firms and make survival harder for sub-scale managers.
⮞In July 2025, the Bank of England reported in its Financial Stability Report that hedge fund leverage via gilt repo had reached a record of about USD 105 billion, with roughly 90% held by a small number of funds. The finding led the central bank to plan a discussion paper on repo reforms.
Opportunities: Private Credit and Data-Driven Strategies Create Opportunities in the Hedge Fund Market
Hedge fund managers are expanding into private credit, asset-based finance and structured lending as banks reduce balance sheet exposure to certain loan categories. These strategies offer contractual income, long investment horizons and returns that depend less on market direction, which appeals to institutional investors seeking yield. Managers with credit underwriting skills can raise closed-end vehicles with committed capital and earn fees that are more stable than performance fees alone. The shift also allows firms to build deeper relationships with corporate borrowers and sponsors.
Advances in artificial intelligence, alternative data and cloud computing give systematic and fundamental managers new ways to find signals, process information and manage risk. Firms that invest in data engineering and talent can widen coverage across markets and execute faster. Natural language models assist analysts in reviewing filings, earnings calls and news, while machine learning supports portfolio construction and trade execution. Emerging hubs in the Gulf and Asia also offer routes to new investors and talent. Managers able to combine data capability with disciplined risk control are expected to take the greatest advantage.
Recent Developments:
-
In October 2026, Man Group reported record assets under management of USD 270.9 billion at the end of the third quarter, up about 7% from the end of June, with net inflows of USD 8.2 billion into long-only strategies and USD 1.9 billion into alternatives. The result reflects investor demand for systematic and discretionary alternatives and strengthens its position among the largest listed managers.
-
In September 2026, Millennium Management opened a Sydney office of about 20 staff and agreed to seed a new long and short equity fund to be run by a former Perpetual portfolio manager. The expansion adds an Australian base for the multi-manager platform and reflects growing competition for regional investment talent.
-
In 2024, Point72 Asset Management continued investing in systematic and data-driven investment capabilities. The development reflects the growing use of quantitative research, alternative data, and technology in hedge fund portfolio management.
Hedge Fund Market Key Players
-
Bridgewater Associates
-
Elliott Management
-
Citadel
-
Man Group
-
D.E. Shaw Group
-
Two Sigma
-
Renaissance Technologies
-
Davidson Kempner Capital Management
-
Point72 Asset Management
-
Marshall Wace
-
Brevan Howard
-
Balyasny Asset Management
-
ExodusPoint Capital Management
-
Farallon Capital Management
-
TCI Fund Management
-
Winton
Hedge Fund Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5,027.02 Billion |
| Market Size by 2035 | USD 8,056.87 Billion |
| CAGR | CAGR of 4.83% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Strategy (Long/Short Equity, Global Macro, Event Driven, Multi-Strategy, Relative Value Arbitrage, Managed Futures, and Others) • By Investor Type (Institutional Investors, High-Net-Worth Individuals, Family Offices, Fund of Funds, Retail Investors, and Others) • By Fund Domicile (Offshore and Domestic) • By Fund Structure (Open-End and Closed-End) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Bridgewater Associates, Millennium Management, Elliott Management, Citadel, Man Group, D.E. Shaw Group, AQR Capital Management, Two Sigma, Renaissance Technologies, Davidson Kempner Capital Management, Point72 Asset Management, Marshall Wace, Brevan Howard, Balyasny Asset Management, ExodusPoint Capital Management, Farallon Capital Management, TCI Fund Management, Winton |

Frequently Asked Questions
Key opportunities include private credit and asset-based finance, artificial intelligence and alternative data in research and execution, and new hubs in the Gulf and Asia. Wealth channels and family offices also offer expanding sources of capital for managers able to meet their liquidity needs.
The major growth factor is rising institutional allocation to alternatives from pension plans, endowments and sovereign funds seeking diversification and return streams that do not depend on market direction. Strong multi-strategy performance and a steady flow of new launches support this demand.
The Long/Short Equity segment dominated the Hedge Fund Market in 2025 with approximately 40.81% share. Its lead reflects investor familiarity, deep market liquidity and the scale of equity platforms run by large multi-manager firms.
North America dominated the Hedge Fund Market in 2025 with approximately 57.41% share. The region combines the deepest institutional investor base, the leading prime brokers and a high concentration of the largest managers in the United States.
