
Semiconductor Lead Frame Market Report Scope & Overview:
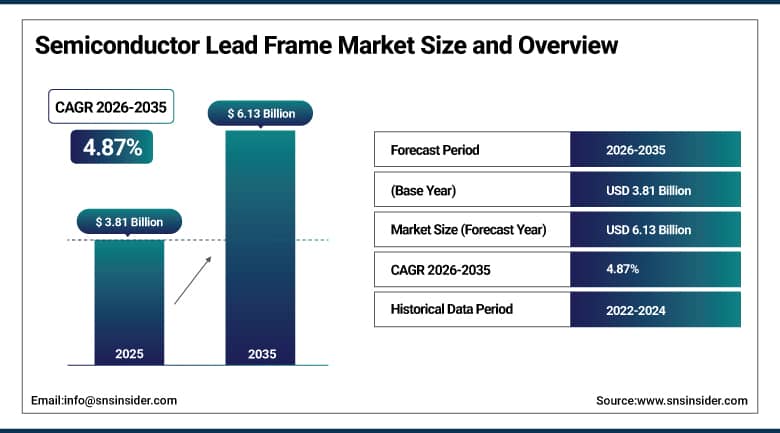
The Semiconductor Lead Frame Market was valued at USD 3.81 Billion in 2025 and is expected to reach USD 6.13 Billion by 2035, growing at a CAGR of 4.87% from 2026-2035.
Semiconductor lead frames are key mechanical and electrical components employed in various semiconductor devices. In addition to offering mechanical support for the silicon die, lead frames serve as channels for electrical connections between the die and the circuit board. Usually made of copper, copper alloy, and alloy 42, lead frames are fabricated via stamping and etching methods. Lead frames may be coated with other materials to enhance conductivity and resistance to corrosion. Their design entails a compromise between mechanical properties, electrical characteristics, thermal properties, and accurate dimensions. As semiconductor devices get smaller and thinner and their design gets more complicated, it becomes necessary for manufacturers to develop highly accurate geometries of lead frames and tighter tolerances.
Shinko Electric Industries introduced advanced copper lead frame solutions specifically engineered for high-power semiconductor devices, offering meaningfully improved thermal dissipation and electrical performance over previous generations. Copper's superior thermal conductivity compared to older alloy-42 formulations makes it an increasingly attractive choice as power semiconductor devices, particularly those destined for electric vehicles and industrial applications, generate more heat that needs to be efficiently carried away, and Shinko's continued investment in this space reflects how seriously established lead frame manufacturers are taking the shift toward higher-power, higher-heat applications across the broader electronics industry.
To Get More Information On Semiconductor Lead Frame Market - Request Free Sample Report
Semiconductor Lead Frame Market Trends
-
Rising adoption of copper lead frames offering superior thermal dissipation compared to traditional alloy-42 formulations.
-
Growing shift toward smaller lead pitches and thinner profiles supporting increasingly compact device packaging.
-
Expanding demand for automotive-grade lead frames meeting AEC-Q100 certification and zero-defect traceability requirements.
-
Increasing use of Dual Flat No-lead packages offering thinner profiles for premium smartphones and automotive sensors.
-
Rising investment in advanced packaging technologies, including glass substrates, complementing traditional lead frame approaches.
-
Growing capacity expansion among Asian manufacturers responding to sustained electric vehicle power device demand.
U.S. Semiconductor Lead Frame Market Outlook
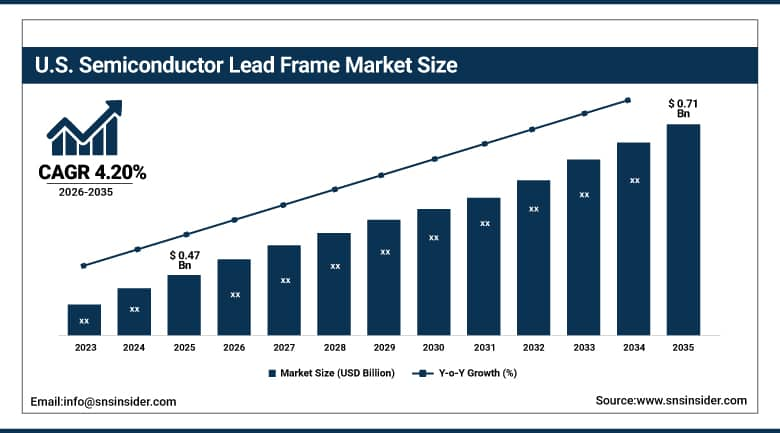
The U.S. Semiconductor Lead Frame Market was valued at USD 0.47 Billion in 2025 and is expected to reach USD 0.71 Billion by 2035, growing at a CAGR of 4.20% from 2026-2035.
Domestic lead frame demand continues tracking closely with the broader U.S. semiconductor packaging and assembly ecosystem, even as the vast majority of global lead frame manufacturing remains concentrated in East Asia. American semiconductor companies and outsourced assembly and test providers continue relying on lead frame technology across a wide range of applications, from automotive power devices to communications infrastructure, with domestic demand increasingly shaped by the broader push toward reshoring advanced packaging capability as part of the country's wider semiconductor supply chain strategy. Growing investment in domestic advanced packaging capacity, including major foundry expansion projects across multiple states, continues reinforcing the strategic importance of reliable lead frame supply chains to the broader U.S. semiconductor manufacturing base.
Amkor Technology, headquartered in Tempe, Arizona, continues serving as one of the world's leading outsourced semiconductor packaging and test providers, offering turnkey manufacturing services spanning communication, automotive, industrial, and consumer electronics applications that rely fundamentally on reliable lead frame supply. The company's operational footprint spans key electronics manufacturing regions across Asia, Europe, and the United States, illustrating how domestic packaging providers continue managing global lead frame sourcing relationships to serve both American and international semiconductor customers across an increasingly diverse range of end markets, including electric vehicles, data centers, and artificial intelligence applications.
Semiconductor Lead Frame Market Segment Analysis
-
By Material, the Copper Alloys segment dominated the Semiconductor Lead Frame Market with approximately 68.40% share in 2025 and is also expected to register the fastest growth, with a CAGR of approximately 6.85%.
-
By Type, the Stamping Process Lead Frame segment dominated the Semiconductor Lead Frame Market with approximately 62.75% share in 2025, while the Etching Process Lead Frame segment is the fastest growing with a CAGR of approximately 6.14%.
-
By Package Type, the Quad Flat No-Leads (QFN) segment dominated the Semiconductor Lead Frame Market with approximately 31.65% share in 2025 and is expected to remain one of the fastest-growing package types, with a CAGR of approximately 8.45%.
-
By Application, the Integrated Circuits segment dominated the Semiconductor Lead Frame Market with approximately 71.10% share in 2025, while the Discrete Devices segment is the fastest growing with a CAGR of approximately 5.65%.
-
By End-Use Industry, the Consumer Electronics segment dominated the Semiconductor Lead Frame Market with approximately 45.05% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 11.10%.
By Material, Copper Alloys Dominate the Semiconductor Lead Frame Market and Grow Fastest
Copper Alloys segment holds dominance on account of the excellent balance of electrical conductivity, thermal conductivity, strength, and formability. The copper alloy lead frames not only efficiently transfer heat from semiconductor devices but also provide electrical connectivity between chip and circuitry outside the package. Availability of these copper alloys in stampable, etchable, plateable, and assembled forms makes them suitable for use in semiconductor packaging applications. Widespread use in ICs, power devices, automotive electronics, and consumer electronics increases the preference of these alloys for manufacturing lead frames.
Copper Alloys also witness the fastest growth among semiconductor lead frames due to the requirement for better thermal management, electrical efficiency, and reliability at high power density for semiconductor devices. The growing production of electric vehicles, power electronics, advanced consumer electronics, data center equipment, and industrial electronics results in rising demands for high-performance copper-based lead frames. Improvements in composition, surface treatments, and plating of these copper alloys increase strength and corrosion resistance while enabling thinner lead frames for semiconductor packages.
By Type, Stamping Process Lead Frame Dominates the Semiconductor Lead Frame Market and Etching Process Lead Frame Grows Fastest
The Stamping Process Lead Frame segment dominates the market owing to its high suitability for large-scale manufacturing processes, low production cost, and fast production pace. Stamping allows producing lead frames of uniform size and excellent physical characteristics while still maintaining production efficiency. Moreover, established manufacturing facilities and compatibility with existing semiconductor packaging are among the reasons for the popularity of this segment. Consumer electronics, automotive electronics, and industrial semiconductors continue to drive the demand for products from this segment.
The Etching Process Lead Frame segment is experiencing the fastest growth rate as the demand for thin and complex designs becomes higher for semiconductor manufacturers. Chemical etching makes it possible to create complex patterns and pitches without expensive stamping dies. This is becoming increasingly relevant in terms of smaller and denser semiconductor packages. The increased usage of advanced semiconductor packaging technologies, small electronics, automotive electronics, and high-performance integrated circuits is driving demand for lead frames created using etching process.
By Package Type, Quad Flat No-Leads (QFN) Dominates the Semiconductor Lead Frame Market and Grows Fastest
Quad Flat No-Leads is the dominating segment due to the small form factor, high thermal conductivity, low electrical resistance, and good heat dissipation provided by QFN packages. The lead frame based design helps in mass production at affordable costs while allowing smaller footprints of semiconductors in constrained electronics devices. QFN packages have been widely used in smartphones, communications, automotive electronics, power management semiconductors, and other industrial applications. Increased integration of semiconductors and demand for small size packages are driving the popularity of QFN packages.
Quad Flat No-Leads is expected to register fastest growth rate as the electronics industry focuses on miniaturization, high-performance electronics, and better heat dissipation from semiconductor devices. QFN packages provide short electrical paths, minimize parasitic effects, and have exposed thermal pads that enhance the heat dissipation in high-performance semiconductor devices. The suitability of QFN packages for use in power management ICs, RF devices, automotive electronics, connectivity devices, and consumer electronics is driving their adoption.
By Application, Integrated Circuits Dominate the Semiconductor Lead Frame Market and Discrete Devices Grow Fastest
Integrated Circuits segment dominates owing to the fact that lead frames continue to be critical for the provision of electrical connectivity, mechanical support and heat dissipation for various IC package types. High production volumes of microcontrollers, analog ICs, power management ICs, communication ICs, and other semiconductor parts result in high lead frame usage. Increasing demand for lead frames from smartphones, computers, automotive, telecom and industrial automation equipment segments drives the market. Continuous integration of semiconductor devices into electronic systems continues to drive the demand for lead frames used in IC packages.
Discrete Devices segment shows fastest growth owing to the increasing demand for power semiconductors, transistors, diodes, rectifiers, and protection devices in automotive, industrial, renewable energy and power management applications. Trends toward electrification are driving the need for more semiconductors in electric cars, chargers, solar inverters, industrial equipment and energy storage systems. Lead frames offer electrical connectivity, mechanical stability and heat dissipation capabilities required for these components, enabling their increasing use in various power electronics applications.
By End-Use Industry, Consumer Electronics Dominates the Semiconductor Lead Frame Market and Automotive Grows Fastest
The Consumer Electronics segment dominates because smartphones, laptops, televisions, wearables, home appliances, gaming devices, and connected products incorporate large volumes of packaged semiconductor components. Continuous product upgrades and increasing functionality require integrated circuits, sensors, power-management devices, and connectivity chips that frequently use lead-frame-based packaging. High-volume electronics manufacturing, particularly across major Asian production hubs, generates substantial demand for cost-efficient semiconductor packaging components. Continued device miniaturization and increasing semiconductor content further sustain lead-frame consumption within consumer electronics.
Automotive business sector shows the fastest growth as cars will use more and more semiconductor devices to enable various applications such as electrification, connectivity, safety, infotainment, and automated driving. Electric vehicles will need a lot of semiconductor devices in battery management systems, inverters, power control units, chargers, and thermal management systems. Driver-assistive systems and connected cars will create even higher demand for sensors, microcontrollers, and power devices. All this creates an ever-growing need for reliable lead frames designed for automotive environment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Semiconductor Lead Frame Market Insights
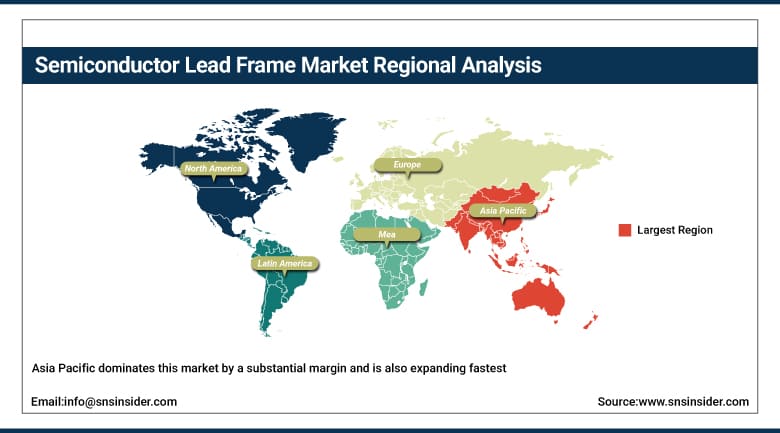
Asia Pacific dominates this market by a substantial margin and is also expanding fastest, anchored by major semiconductor fabrication and assembly hubs across China, Taiwan, Japan, and South Korea that together account for the overwhelming majority of global lead frame production. The region's deep concentration of both semiconductor manufacturing capacity and lead frame production capability continues reinforcing Asia Pacific's position as the undisputed center of this industry.
The growing domestic production of semiconductors in China is further fueling demand in the region, whereas Japan and Taiwan are making major contributions to the production capacity via their lead frame suppliers, which have decades of experience behind them. South Korea is completing the picture of the region’s production capability via its memory and logic semiconductor industry, ensuring the position of Asia-Pacific as the biggest and fastest-growing market.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Semiconductor Lead Frame Market Insights
North America represents a meaningful share of the global semiconductor lead frame market, anchored by the United States' substantial semiconductor design, assembly, and test ecosystem, even as actual lead frame manufacturing remains predominantly concentrated in Asia. The region's growing domestic semiconductor manufacturing investment, including expanding advanced packaging capacity, continues reinforcing demand for reliable lead frame supply chains supporting American chip production and assembly operations.
Canada is contributing incremental regional demand as its own electronics manufacturing sector continues developing. Continued domestic investment in semiconductor supply chain resilience is expected to sustain steady regional growth through the forecast period, even as the region trails Asia Pacific substantially in both absolute manufacturing scale and growth pace.
Europe Semiconductor Lead Frame Market Insights
Europe represents a meaningful share of the global semiconductor lead frame market, anchored by the region's substantial automotive electronics manufacturing base, which continues driving demand for automotive-grade lead frames meeting stringent reliability and certification requirements. Germany's deep automotive and industrial electronics sector continues anchoring regional demand for lead frame technology suited to demanding power and sensor applications.
Regional semiconductor packaging providers, including facilities serving major automotive customers, continue extending lead frame adoption across an expanding range of automotive electronics applications. Continued European investment in domestic semiconductor supply chain capability is expected to support steady regional growth through the forecast period.
MEA & Latin America Semiconductor Lead Frame Market Insights
The Middle East & Africa market remains comparatively small, with limited domestic semiconductor manufacturing capability meaning most lead frame demand flows through imported, finished electronic components rather than direct regional lead frame consumption. Regional electronics assembly activity remains at an early stage of development relative to more established global markets.
Latin America's market remains similarly modest, with Brazil and Mexico contributing incremental demand as regional electronics assembly and automotive manufacturing continue to develop gradually. Genuine lead frame manufacturing capability across the region remains limited, with most demand continuing to flow through imported semiconductor components.
Market Dynamics
Growth Drivers: Consumer Electronics Growth and Electric Vehicle Adoption
Growth of consumer electronics manufacturing represents a primary driver of semiconductor lead frame market growth, as expansion of integrated circuit production and rising demand for reliable semiconductor packaging continue reinforcing sustained lead frame consumption across smartphones, wearables, and home entertainment devices. The cost efficiency of lead frame packaging, combined with early adoption across industrial electronics applications, continues supporting sustained demand across the broader consumer electronics vertical.
Rising electric and autonomous vehicle adoption represents a second major growth driver, as these vehicle platforms continue multiplying demand for reliable power device packaging capable of tolerating significant thermal stress. Surging 5G and IoT deployment requirements, which demand robust interconnects supporting higher frequencies and lower latency, continue reinforcing sustained lead frame demand across an expanding range of connected electronic applications.
Restraints: Raw Material Price Volatility and Trade Policy Uncertainty
Raw material price volatility represents a meaningful restraint on market growth, as copper and nickel prices continue fluctuating in response to broader commodity market conditions, creating cost uncertainty that can complicate long-term pricing agreements between lead frame manufacturers and their semiconductor customers.
Evolving trade policy and tariff conditions represent a further restraint, as shifting international trade arrangements continue introducing genuine cost volatility and supply-chain uncertainty across the heavily globalized semiconductor lead frame value chain. This policy uncertainty continues complicating long-term capacity planning decisions for manufacturers operating across multiple international jurisdictions.
Opportunities: Copper Alloy Innovation and Automotive-Grade Certification Expansion
Continuous development of copper alloy lead frame technology provides a significant opportunity in that manufacturers who are capable of providing a superior thermal dissipation and electrical performance stand to benefit from taking the market share from power-intensive uses that increasingly need such an ability, especially in electric vehicles and industrial power electronics sectors.
The growing ability to manufacture automotive-grade components is another area where growth potential exists because the increasing demand for AEC-Q100 certified zero defect traceability will push the demand towards manufacturers who have the ability to produce automotive-grade components. This creates an opportunity for manufacturers to get market share from automotive manufacturers and their first-tier suppliers who are willing to pay a premium for reliability over price in their automotive electronic applications.
Recent Developments:
-
Mitsui High-tec announced an expansion of its Malaysia plant to boost production capacity by 25%, responding to growing demand for power electronics in electric vehicles.
-
ASMPT enhanced its semiconductor packaging portfolio by introducing high-precision lead frame manufacturing technologies supporting next-generation power and automotive chips.
-
In January 2026, Rapidus announced progress in panel-level packaging using glass substrates for next-generation AI and high-performance computing processors, reflecting the industry's broader shift toward advanced packaging solutions that complement lead frame technology.
Semiconductor Lead Frame Market Key Players
-
Mitsui High-tec, Inc.
-
SHINKO ELECTRIC INDUSTRIES CO., LTD.
-
ASM Pacific Technology Ltd.
-
Chang Wah Technology Co., Ltd.
-
Amkor Technology Inc.
-
HAESUNG DS Co., Ltd.
-
Advanced Assembly Materials International Ltd.
-
Fusheng Electronics
-
Enomoto Co., Ltd.
-
POSSEHL Electronics
-
JIH LIN TECHNOLOGY CO., LTD.
-
Dynacraft Industries
-
QPL Limited
-
Wuxi Huajing Leadframe Co., Ltd.
-
Huayang Electronic Co., Ltd.
-
Dai Nippon Printing Co., Ltd.
-
Xiamen Jsun Precision Technology
-
SDI Group, Inc.
-
Toppan Inc.
-
ASE Technology Holding Co., Ltd.
Semiconductor Lead Frame Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.81 Billion |
| Market Size by 2035 | USD 6.13 Billion |
| CAGR | CAGR of 4.87% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Stamping Process Lead Frame, Etching Process Lead Frame) • By Material (Copper Alloys, Iron-Nickel Alloys, Others) • By Package Type (Dual Inline Pin Package, Small Out-Line Package, Small Outline Transistor, Quad Flat Pack, Quad Flat No-Leads, Others) • By Application (Integrated Circuits, Discrete Devices, Others) • By End-Use Industry (Consumer Electronics, Automotive, Industrial, Telecommunications, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Mitsui High-tec, Inc., SHINKO ELECTRIC INDUSTRIES CO., LTD., ASM Pacific Technology Ltd., Chang Wah Technology Co., Ltd., Amkor Technology Inc., HAESUNG DS Co., Ltd., Advanced Assembly Materials International Ltd., Fusheng Electronics, Enomoto Co., Ltd., POSSEHL Electronics, JIH LIN TECHNOLOGY CO., LTD., Dynacraft Industries, QPL Limited, Wuxi Huajing Leadframe Co., Ltd., Huayang Electronic Co., Ltd., Dai Nippon Printing Co., Ltd., Xiamen Jsun Precision Technology, SDI Group, Inc., Toppan Inc, ASE Technology Holding Co., Ltd |
Frequently Asked Questions
Key players include Mitsui High-tec, Inc., SHINKO ELECTRIC INDUSTRIES CO., LTD., ASM Pacific Technology Ltd., Chang Wah Technology Co., Ltd., and Amkor Technology Inc., among other lead frame manufacturers.
Continued innovation in copper alloy lead frame formulations and continued expansion of automotive-grade certification capability represent the biggest opportunities for manufacturers.
Growth is driven mainly by growth of consumer electronics manufacturing, combined with rising electric and autonomous vehicle adoption requiring reliable power device packaging.
By Industry Vertical, Consumer Electronics held approximately 44.60% share in 2025, powered by sustained handset updates and home entertainment device demand across an enormous global device base.
Asia Pacific led with a substantial share in 2025, anchored by major semiconductor fabrication and assembly hubs across China, Taiwan, Japan, and South Korea.
