
Field Programmable Gate Array (FPGA) Market Report Scope & Overview:
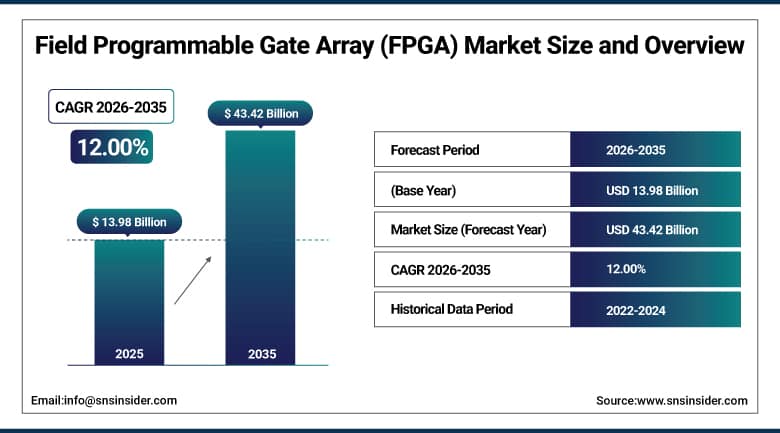
Field Programmable Gate Array (FPGA) Market was valued at USD 13.98 billion in 2025 and is expected to reach USD 43.42 billion by 2035, growing at a CAGR of 12.00% from 2026-2035.
The FPGA market is expanding globally at a rapid pace due to advancements in artificial intelligence, 5G technology, autonomous vehicles, edge computing, and modern data centers. Field-programmable gate arrays (FPGAs) are types of programmable integrated circuits which are designed to undergo programming post-manufacturing. While different from ASICs or microprocessors, FPGAs offer great flexibility, allowing users to develop highly efficient software solutions for various applications including artificial intelligence.
The U.S. CHIPS and Science Act allocates funding specifically supporting advanced semiconductor R&D including reconfigurable computing architectures, directly benefiting the domestic FPGA design and manufacturing ecosystem.
Market Size and Forecast
-
Market Size in 2026E: USD 15.66 Billion
-
Market Size by 2035: USD 43.42 Billion
-
CAGR: 12.00% from 2026 to 2035
-
Fastest Growing Region: North America
- Largest Region: Asia Pacific
To Get More Information On Field Programmable Gate Array (FPGA) Market - Request Free Sample Report
Field Programmable Gate Array (FPGA) Market Trends
-
Rising demand for high-performance, flexible, and reconfigurable computing solutions is driving the Field Programmable Gate Array (FPGA) market.
-
Growing adoption across telecommunications, automotive, aerospace & defense, and data centers is boosting market growth.
-
Expansion of AI, machine learning, and edge computing applications is fueling FPGA deployment.
-
Increasing focus on low-latency processing, parallel computing, and real-time data handling is shaping adoption trends.
-
Advancements in semiconductor fabrication, heterogeneous integration, and power-efficient architectures are enhancing performance.
-
Rising demand for customization and faster time-to-market in electronic system design is supporting market expansion.
-
Collaborations between semiconductor companies, OEMs, and technology developers are accelerating innovation and global adoption.
U.S. Field Programmable Gate Array (FPGA) Market Outlook
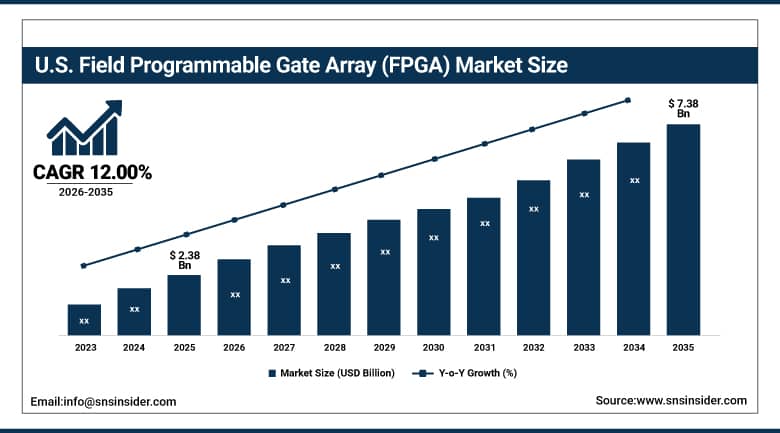
The U.S. Field Programmable Gate Array (FPGA) Market was valued at USD 2.38 billion in 2025 and is expected to reach USD 7.38 billion by 2035, growing at a CAGR of 12.00% from 2026-2035.
The U.S. Air Force Research Laboratory (AFRL) and Space Force have issued multiple procurement contracts for radiation-hardened FPGA components and reprogrammable satellite payloads based on FPGA technology, reflecting the U.S. military's sustained investment in field-programmable hardware as a strategic capability for adaptive electronic systems. DARPA's Intelligent Neural Interface (INI) program and High Assurance Systems (HAS) program incorporate FPGA technology for secure, reconfigurable processing architectures.
Field Programmable Gate Array (FPGA) Market Segment Analysis
-
By Configuration, the Low-End segment dominated the Field Programmable Gate Array (FPGA) Market with approximately 43.38% share in 2025, while the Mid-Range segment is the fastest growing with a CAGR of approximately 13.19%.
By Technology, the SRAM segment dominated the Field Programmable Gate Array (FPGA) Market with approximately 42.47% share in 2025, while the Flash segment is the fastest growing with a CAGR of approximately 13.77%.
By End User, the Telecom segment dominated the Field Programmable Gate Array (FPGA) Market with an estimated 34.62% share in 2025, while the Military & Aerospace segment is the fastest growing with an estimated CAGR of approximately 13.94%.
By Configuration, Low-End segment dominates the FPGA Market, Mid-Range segment expected to grow fastest
Low-End FPGA leads the market because of its wide application in consumer devices, industrial automation, and automotive devices that demand cost-effective programmability. This category includes ECUs, ADAS interface circuits, PLCs, and embedded systems. Competition and adequate supplier presence by vendors such as Lattice, Microchip, and GOWIN keep the costs low and support mass production in different sectors.
Mid-Range FPGAs segment are anticipated to record the fastest growth, since there is increasing need for performance, flexibility, and cost-effective FPGAs. They are common in the 5G infrastructure, vision systems for industries, AI inference at the edge, and automotive ADAS. Higher logic and transceiver options provided by platforms by AMD and Intel enable new use cases beyond those offered by low-end FPGAs.
By Technology, SRAM segment dominates the FPGA Market, Flash segment expected to grow fastest
The SRAM-based FPGA segment dominates the market due to its high-performance capabilities and flexibility, and its use in telecommunications, data centers, and industrial automation. The FPGA SRAM-based architecture allows unlimited programmability and process node development, facilitating updates for new standards. FPGA solutions in this market include those developed by AMD and Intel, namely Virtex UltraScale+, Versal, Stratix, and Agilex.
The Flash-based FPGA segment is forecasted to witness the highest growth rate due to its nonvolatile nature, instant-on operation mode, and energy efficiency. It eliminates the need for additional memory, which increases security and reliability. Therefore, Flash-based FPGAs find extensive use in Internet-of-Things products, space technology, defense, and industry applications. The examples of devices include PolarFire and SmartFusion solutions by Microchip.
By End User, Telecom segment dominates the FPGA Market, Military & Aerospace segment expected to grow fastest
The Telecom segment dominates the FPGA market due to its wide range of applications in 5G base stations, radio units, baseband processing, optical transport, and packet switching systems. Multi-standard capability ensures that there can be an upgrade from 3G, 4G, and 5G network systems with only software changes. Therefore, FPGAs have become increasingly popular in telecom products because of their cost-effectiveness and ability to prolong infrastructure life cycles.
Military & Aerospace segments will show the highest growth rates because of the growing popularity of FPGAs in radar technology, electronic warfare, satellite communications, missile guidance systems, and UAVs. Military & aerospace segments need FPGAs that are radiation-hardened and offer secure performance with high reliability. Additionally, increasing satellite constellations and space missions have contributed to the growing popularity of space-qualified FPGAs.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
45% |
|
North America |
United States |
88% |
|
Europe |
Germany |
26% |
|
Middle East & Africa |
Israel |
42% |
|
Latin America |
Brazil |
48% |
Asia Pacific Field Programmable Gate Array (FPGA) Market Insights
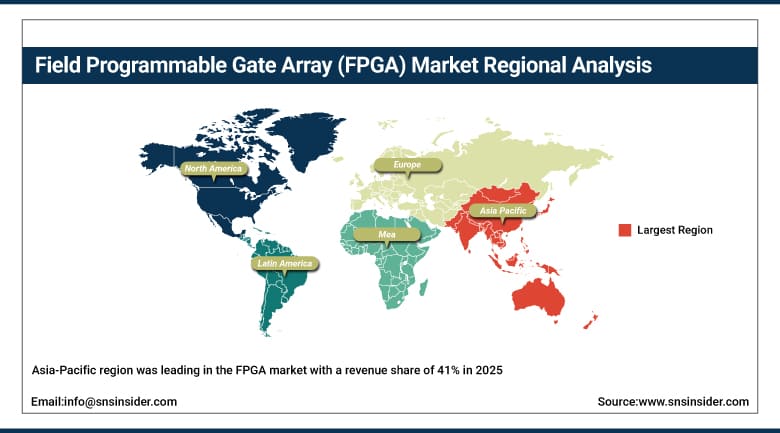
Asia-Pacific region was leading in the FPGA market with a revenue share of 41% in 2025 due to its leading position in the manufacture of electronics, telecom equipment, and consumer electronics. The key markets include China, Japan, South Korea, and India. China's massive consumer electronics manufacture, deployment of 5G technology, and automobile electronics manufacturing account for the region's biggest FPGA consumption.
China's Ministry of Industry and Information Technology has designated FPGA development as a priority area for domestic semiconductor self-sufficiency under national industrial policy, allocating funding through the National Integrated Circuit Industry Investment Fund for Chinese FPGA companies to advance domestic design and manufacturing capabilities, reduce import dependence, and serve China's large domestic telecom, industrial, and consumer electronics markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Field Programmable Gate Array (FPGA) Market Insights
The North American region is experiencing the highest growth rate within the FPGA market, with an expected CAGR of about 10.80% until 2035 due to the exceptional rise in data center AI inference workload applications utilizing FPGA accelerators, increased FPGA investments within the United States defense industry, 5G network densification, and the resurgence of domestic semiconductor investment due to the CHIPS Act. The presence of leading FPGA technologies from AMD (Xilinx) and Intel’s Programmable Solutions Group in the United States is a unique factor in supporting the growth and innovation of FPGAs.
Europe Field Programmable Gate Array (FPGA) Market Insights
Europe held a significant share in the global FPGA Market in 2025, owing to its advanced automobile electronics sector, telecommunications network installation, military and aviation projects, and industrial automation market. The German automobile original equipment manufacturers and tier one suppliers are key customers for FPGAs in applications related to ADAS, infotainment, and body electronics, whereas European telecom companies' 5G implementation projects create demand for FPGA-enabled radio units and baseband processing systems.
The European Defence Agency (EDA) has identified FPGA technology as a strategic microelectronics capability for European defense independence, supporting programs to develop trusted European sources for military-grade FPGA components and reduce dependence on non-European supply chains for critical defense electronics. This strategic designation reinforces sustained European defense-sector FPGA procurement and stimulates domestic European FPGA design activity.
Middle East & Africa and Latin America Field Programmable Gate Array (FPGA) Market Insights
The Middle East & Africa and Latin America regions represent emerging growth markets for FPGAs, due to their growth potential based on FPGA-enabled products, namely telecommunications devices, industrial automation systems, and defense electronics modernization. Israel is an especially important MEA player in terms of FPGA market due to its status as an international center of FPGA-oriented development of defense electronics for Intel, AMD, and other defense primes producing radars, EWs, and intelligence systems. Saudia Arabia and UAE are building local technology industries utilizing FPGA-based products.
Market Dynamics
Growth Drivers: Growing demand for AI, 5G, and data center acceleration drives strong global adoption of high-performance FPGAs.
The convergence of three of the most potent technology investment cycles in the contemporary world artificial intelligence, fifth generation communications technology, and data center innovation is giving rise to an unprecedented demand scenario for high-end FPGAs. FPGAs have been adopted by data centers to enable certain types of computing, such as network packet analysis, data compression, encryption, financial models, genomics computation, and artificial intelligence inferencing, with benefits of lower latency, reduced power consumption, and lower costs than GPU-only systems. The 5G base station equipment industry has emerged as one of the biggest single buyers of large-scale FPGAs due to the deployment of massive MIMO radios that require real-time beamforming calculations beyond the scope of traditional silicon.
The U.S. National Security Agency (NSA) and National Institute of Standards and Technology (NIST) have endorsed hardware-based cryptographic implementations for which FPGAs are ideally suited as part of their post-quantum cryptography migration guidance. The migration of U.S. government and defense systems to quantum-resistant cryptographic algorithms implemented in FPGA hardware is creating a significant and growing procurement program that sustains premium defense-sector FPGA demand through the forecast period.
Restraints: High design complexity and engineering costs limit FPGA adoption for organizations lacking specialized hardware development expertise.
There are large complexities involved in the development of FPGAs that restrict their use only to organizations with the skills to do design at register transfer level and use FPGA tools. Design verification and validation efforts for highly complex FPGA systems could require engineering investments equivalent to ASIC design without having the same automation of verification tools that ASICs have. For companies that are used to designing in software terms, there is a change in paradigms required in moving from software languages to hardware description languages.
Opportunities: AI-assisted tools, high-level synthesis, and IP libraries reduce FPGA development barriers and expand market accessibility significantly.
The process of democratizing the design of FPGAs using HLS techniques that translate programming languages like C/C++ and Python into FPGA hardware has significantly diminished the specialized hardware engineering skills required for tapping into the power of FPGAs. The advent of tools like Vitis HLS by AMD and oneAPI by Intel, coupled with AI-enabled hardware design solutions, is allowing software engineers to build hardware accelerators without any understanding of RTL design, thus increasing the number of developers who can create FPGA applications.
Recent Developments:
-
2025: AMD unveiled the Versal AI Edge Series Gen 2, a next-generation adaptive SoC combining FPGA programmable logic with AI Engine processors on TSMC's 4nm process node, targeting embedded AI inference in automotive, industrial, and defense applications requiring on-device machine learning.
-
2025: Intel's Programmable Solutions Group introduced the Agilex 7 R-Tile FPGA with integrated PCIe Gen 5 and CXL 2.0 interfaces, targeting data center AI acceleration and SmartNIC applications where high-bandwidth chip-to-chip and host-to-accelerator connectivity is critical.
-
2024: Lattice Semiconductor launched the Lattice Avant platform — its first mid-range FPGA family built on Samsung's 16nm FinFET process, targeting industrial automation, communications, and automotive applications requiring balance of performance, power, and mid-range pricing.
-
2024: Microchip Technology expanded its PolarFire FPGA family with new video and imaging-optimized variants for broadcast, medical imaging, and machine vision applications, adding H.264/H.265 codec IP and enhanced ISP pipeline capabilities to its low-power mid-range FPGA portfolio.
-
2023: AMD completed full integration of Xilinx's FPGA and adaptive SoC product lines following the USD 49 billion acquisition close, launching the unified Alveo data center accelerator series combining Versal AI Core and HBM memory for large-scale AI inference deployments.
-
2023: Efinix Inc. raised USD 20 million in Series C funding to accelerate development of its Trion and Titanium FPGA families featuring the proprietary Quantum compute fabric architecture, targeting the growing market for compact, power-efficient FPGAs in edge AI and IoT applications.
-
2022: GOWIN Semiconductor expanded its FPGA portfolio into mid-range devices with the GW5A series on a 22nm process node, advancing China's domestic FPGA capability and targeting domestic telecom, industrial, and consumer electronics applications seeking reduced dependence on foreign FPGA suppliers.
Field Programmable Gate Array (FPGA) Market Key Players
-
Advanced Micro Devices, Inc.
-
Intel Corporation
-
Microchip Technology Inc.
-
Lattice Semiconductor Corporation
-
Achronix Semiconductor Corporation
-
QuickLogic Corporation
-
Efinix, Inc.
-
FlexLogix Technologies, Inc.
-
GOWIN Semiconductor Corporation
-
S2C Inc.
-
Renesas Electronics Corporation
-
Infineon Technologies AG
-
NXP Semiconductors N.V.
-
STMicroelectronics N.V.
-
Teledyne DALSA
-
Xilinx
-
Actel Corporation
-
Tabula Inc.
-
Altera
-
Enpirion
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 13.98 Billion |
| Market Size by 2035 | USD 43.42 Billion |
| CAGR | CAGR: 12.00% from 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Low-End, Mid-Range, High-End) • By Technology (SRAM, EEPROM, Antifuse, Flash, Others) • By Application (Consumer Electronics, Automotive, Industrial, Data Processing, Military & Aerospace, Telecom, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Advanced Micro Devices, Inc. (Formerly Xilinx, Inc.), Intel Corporation, Microchip Technology Inc., Lattice Semiconductor Corporation, Achronix Semiconductor Corporation, QuickLogic Corporation, Efinix, Inc., FlexLogix, GOWIN Semiconductor Corporation, S2C, AGM Micro, Shanghai Anlu Information Technology Co., Ltd., Shenzhen Ziguang Tongchuang Electronics Co., Ltd., Xi'an Zhiduoji Microelectronics Co., Ltd., Renesas Electronics Corporation, LeafLabs, LLC, Aldec, Inc. |
Frequently Asked Questions
Key players include AMD, Intel, Lattice Semiconductor, Microchip Technology, Achronix, and QuickLogic.
Key opportunities include AI acceleration, edge computing, 5G infrastructure, and automotive electronics applications.
Market growth is driven by AI workloads, reconfigurable computing, telecom expansion, and data centers.
Low-end FPGAs dominated the market due to cost efficiency and broad embedded applications.
North America dominated in 2025, supported by strong semiconductor innovation and data center investments.
