
Shoulder Fired Weapons Market Report Scope & Overview:
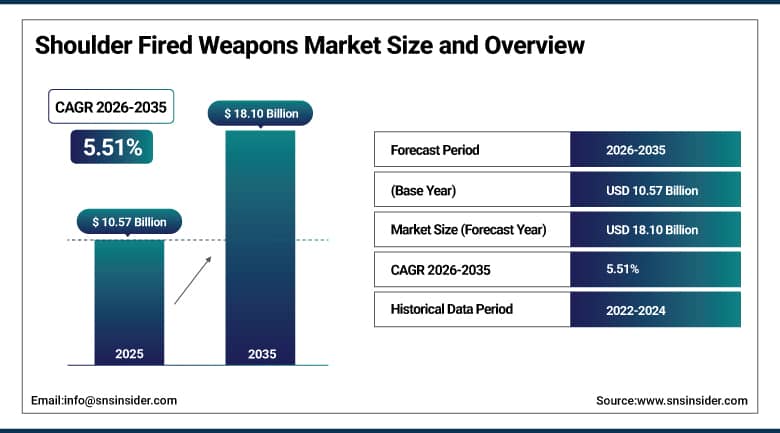
The Shoulder Fired Weapons Market was valued at USD 10.57 Billion in 2025 and is expected to reach USD 18.10 Billion by 2035, growing at a CAGR of 5.51% from 2026 to 2035.
The shoulder fired weapons market is growing at a rapid pace owing to rising geopolitical tensions and border conflicts, increased military modernization programs, and growing demand for portable and lightweight weaponry. Shoulder fired weapons refer to weapons shot while being held in the hands with the butt pressed against a shoulder, encompassing anti-tank guided missile launchers, man-portable air defense systems, recoilless rifles, and rocket-propelled grenades used across infantry, special operations, and homeland security applications. Furthermore, market growth is being reinforced by infantry units increasingly facing heavy armor, drones, and fortified positions inside densely populated areas where portable precision launchers let them respond without waiting for artillery or airpower, surge in asymmetric and urban warfare scenarios, and technological advancements in guidance and targeting systems.
The deployment of the Electronic Warfare Planning and Management Tool by the U.S. Army is raising the strategic status of unguided shoulder-fired weapons in electronic warfare missions, as the tool enhances commanders' control of the electromagnetic spectrum, enabling more sophisticated planning and execution of electronic attacks where unguided munitions provide an inexpensive way to disable or interfere with enemy communications and radar capabilities.
To Get More Information On Shoulder Fired Weapons Market - Request Free Sample Report
Shoulder Fired Weapons Market Trends
- Rising infantry demand for portable precision launchers is supporting rapid response against armor, drones, and fortified positions.
- Growing AI and machine learning integration is improving targeting precision and engagement effectiveness in complex battlefields.
- Increasing lightweight missile adoption is enhancing infantry mobility while reducing the physical burden of weapon systems.
- Expanding countermeasure-resistant guidance development is improving effectiveness against electronic warfare and active protection systems.
- Strategic partnerships are accelerating development of precise, cost-effective, and portable shoulder-fired weapon systems.
The U.S. Shoulder Fired Weapons Market Outlook
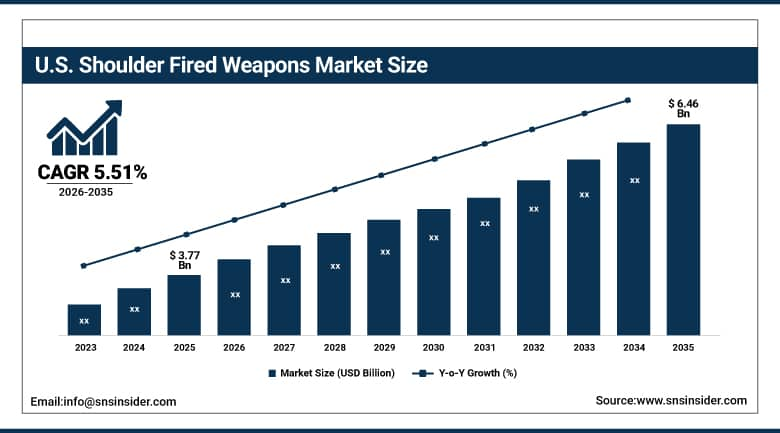
The U.S. shoulder fired weapons market was valued at USD 3.77 Billion in 2025 and is projected to reach USD 6.46 Billion by 2035, growing at a CAGR of 5.51% during 2026–2035.
The main defense departments of the country continue to procure shoulder-fired weapon systems on account of huge defense expenditure, state-of-the-art military technology, and continued innovation in portable weapon systems used to upgrade the infantry units. The increasing defense department expenditure on precision-guided weapon systems and light anti-armor systems, along with the increased use of EW integration technology that increases the effectiveness of unguided weapon systems, ensures that there will be continued domestic demand for shoulder-fired weapon systems whether guided or unguided.
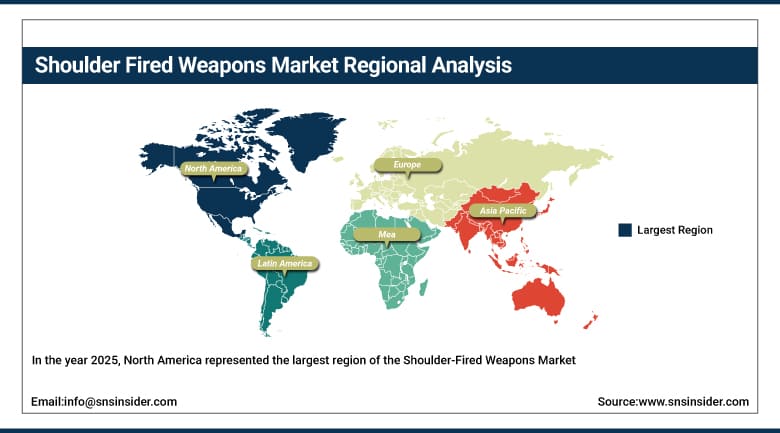
North America represents the largest regional market for shoulder-fired weapons, supported by high defense spending, advanced military technologies, and continuous innovation in portable weapon systems, with the United States accounting for the substantial majority of regional procurement and modernization investment.
Shoulder Fired Weapons Market Segment Analysis
- By Technology, guided dominated the shoulder fired weapons market with a 68.74% share in 2025, while unguided is the fastest-growing technology segment with a CAGR of 7.64% from 2026–2035.
- By Weapon Type, anti-tank guided missile (ATGM) launchers dominated the shoulder fired weapons market with a 35.07% share in 2025, while man-portable air defense systems (MANPADS) is the fastest-growing weapon type segment with a CAGR of 8.41% from 2026–2035.
- By Range, short-range dominated the shoulder fired weapons market with a 40.31% share in 2025, while long-range is the fastest-growing range segment with a CAGR of 7.58% from 2026–2035.
- By Projectile Component, launcher/tube dominated the shoulder fired weapons market with a 53.57% share in 2025, while fire-control & sighting systems is the fastest-growing projectile component segment with a CAGR of 8.83% from 2026–2035.
- By End-User, army dominated the shoulder fired weapons market with a 54.88% share in 2025, while special operations forces is the fastest-growing end-user segment with a CAGR of 8.60% from 2026–2035.
By Technology, guided dominated the shoulder fired weapons market, while unguided is the fastest-growing segment.
By technology, guided systems held 68.74% of the shoulder fired weapons market share in 2025. Guided technology remains the dominant category owing to its advanced targeting capabilities, allowing military forces to engage targets with substantially higher precision and reduced collateral damage risk, making guided systems the preferred choice across the majority of modern infantry anti-armor and air defense procurement programs worldwide.
Unguided systems will post the fastest segment CAGR at 7.64% through the forecast period. The deployment of electronic warfare planning tools is raising the strategic status of unguided shoulder-fired weapons in electronic warfare missions, providing an inexpensive way to disable or interfere with enemy communications and radar capabilities, driving renewed procurement interest in cost-effective unguided munitions for specific tactical applications.
By Weapon Type, anti-tank guided missile (ATGM) launchers dominated the shoulder fired weapons market, while man-portable air defense systems (MANPADS) is the fastest-growing segment.
By weapon type, anti-tank guided missile launchers commanded 35.07% of the shoulder fired weapons market size in 2025. ATGM launchers remain the dominant weapon type category owing to the widespread adoption of man-portable anti-tank systems providing infantry forces the ability to engage armored vehicles without being overly concerned about strike accuracy or weapon weight, reflecting sustained global demand for effective, portable anti-armor capability.
MANPADS are forecast to grow at an 8.41% CAGR through the forecast period. Rising asymmetric warfare threats and growing concerns over adversary aerial capabilities, including drones and low-flying aircraft, are driving strong demand for man-portable air defense systems, as militaries increasingly prioritize distributed, infantry-level air defense capability across contested airspace environments.
By Range, short-range dominated the shoulder fired weapons market, while long-range is the fastest-growing segment.
Short Range systems had an account of 40.31% in the shoulder fired weapons market Share in 2025, by range. Short Range systems hold dominance due to their extensive use in close urban warfare, as well as typical infantry engagements, constituting the largest range system used for both conventional and asymmetric warfare settings.
The long-range segment is expected to grow at a rate of 7.58% CAGR during 2026 to 2035, covering the entire forecast period. Increasing demand for weapons systems offering long-range engagement capabilities enabling the infantry troops to attack enemies from far-off distances to minimize their exposure to counterattacks from enemies is anticipated to fuel the growth of the segment.
By Projectile Component, launcher/tube dominated the shoulder fired weapons market, while fire-control & sighting systems is the fastest-growing segment.
By projectile component, launchers and tubes led with 53.57% revenue share in 2025. Launched systems will continue to be the major component segment since it is the most basic part of the weapon system as it provides the initial firing capability of all shoulder-fired weapons and forms the biggest component segment within both guided and unguided weapon system segments globally.
The fire control and sighting systems are expected to grow at a CAGR of 8.83% during the forecast period. Increased use of advanced target acquisition, night vision, and thermal imaging in the fire control systems is leading to the fast-paced growth of this segment, due to the need for achieving first-round kill rate and target acquisition.
By End-User, army dominated the shoulder fired weapons market, while special operations forces is the fastest-growing segment.
By end-user, armies accounted for 54.88% of the shoulder fired weapons market in 2025. Armies remain the dominant end-user category owing to the sheer scale of global ground force personnel requiring standard infantry anti-armor and air defense capability, representing the foundational and most substantial procurement channel for shoulder-fired weapon systems worldwide.
The Special Operations Forces segment is expected to register the fastest CAGR of 8.60% during the forecast period 2026-2035. Growing global investment in elite, rapid-deployment military units requiring the most advanced, lightweight, and precise portable weapon systems is driving strong segment growth, as special operations forces increasingly prioritize compact, high-performance weapon systems suited to unconventional mission profiles.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
France |
27.60% |
|
Asia Pacific |
India |
44.60% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
37.70% |
North America Shoulder Fired Weapons Market Insights
In the year 2025, North America represented the largest region of the Shoulder-Fired Weapons Market on account of increased defense expenditure, military technological advancements, and innovations in portable weaponry systems to maintain and modernize its significant defense industry.
In the North America Shoulder-Fired Weapons Market in the year 2025, the US accounted for the top position on account of continued Department of Defense investments in guided missiles and light weight anti-armor systems. Canada has made its contribution towards growth in the region in the form of investments in defense modernization.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Shoulder Fired Weapons Market Insights
The Europe shoulder fired weapons market was a major contributor in 2025. This is attributed to the region's substantial defense modernization investment, strong presence of leading shoulder-fired weapon manufacturers, and growing NATO-aligned procurement cooperation across member states.
France is one of the major markets in Europe owing to its strong defense industrial base and presence of leading manufacturers such as MBDA and Thales Group. Other countries such as Sweden, home to Saab AB, and Germany are also contributing to market growth through expanding defense modernization investment and growing portable weapon system export activity.
Asia Pacific Shoulder Fired Weapons Market Insights
Asia-Pacific is the fastest growing region in the shoulder fired weapons market. The market growth is driven by expanding domestic defense manufacturing capability, rising regional territorial tensions, and growing government investment in infantry modernization programs across the region's major and emerging economies.
India is one of the main growth drivers in the Asia Pacific shoulder fired weapons market, owing to its expanding domestic defense manufacturing capability through companies such as Bharat Dynamics Limited and rising infantry modernization investment. China and South Korea are also contributing to regional growth through expanding domestic weapon system production and growing regional territorial tension-driven procurement.
Middle East & Africa and Latin America Shoulder Fired Weapons Market Insights
Middle East & Africa and Latin American regions are gradually expanding shoulder-fired weapons adoption as defense modernization investment grows across both regions, supported by increasing regional conflict-driven procurement and border security investment.
Brazil is set to be a prominent Latin American market fueled by growing domestic defense modernization investment and border security procurement. The Middle East & Africa region has UAE and Saudi Arabia investing heavily in advanced portable weapon systems as part of broader defense modernization strategies supporting the region's expanding infantry and homeland security procurement programs.
Market Dynamics
Growth Drivers: Rising geopolitical tensions and military modernization driving market growth
The escalation of international geopolitical tensions and ongoing border conflicts is playing a major role in fueling the need for shoulder fired weapons, with militaries favoring deployable and affordable force multipliers. Rising instances of armed conflicts, violence, and terrorism, along with the increasing integration of artificial intelligence and machine learning with shoulder-fired weapons that help military personnel deal with combatants while minimizing collateral damage, are primarily driving market growth.
Increased military modernization programs, growing demand for portable and lightweight weaponry, and surge in asymmetric and urban warfare scenarios continue to support sustained demand across global defense procurement programs. Technological advancements in guidance and targeting systems, increasing military spending to enhance defense capabilities, and expanding use of advanced armored machinery in conflicts necessitating deployment of sophisticated shoulder-fired weapons are further supporting demand across the forecast period.
Restraints: High lifecycle costs and stringent export controls limiting market expansion
One of the key constraints to growth in the market is the relatively higher lifecycle and maintenance costs of state-of-the-art guided weapon systems, which may limit procurement volumes in light of competition from other modernization needs in defense budgets among various weapon system categories.
Moreover, rigorous export control and regulatory barriers with regard to international shipment of guided weapon systems and sensitive targeting technology pose problems to sales across borders and access to markets by producers aiming at supplying to allied nations' militaries. Research and development efforts are needed in developing countermeasure-resistant guidance systems to defeat more complex electronic warfare systems.
Opportunities: Expansion of countermeasure-resistant guidance and special operations procurement creating new growth avenues
The development of advanced countermeasure-resistant guidance systems represents a significant market opportunity, as manufacturers investing in technology capable of overcoming increasingly sophisticated electronic warfare and active protection countermeasures are positioned to capture growing defense procurement across contested threat environments.
There is a considerable growth opportunity in the continued development of lightweight, special operations-focused weapon systems suited to rapid-deployment mission profiles. The expansion of defense modernization investment and domestic weapon system manufacturing capability in emerging markets across Asia Pacific and the Middle East is likely to unlock substantial new demand throughout the forecast period.
Recent Developments:
- 2025: Saab AB expanded its Carl-Gustaf M4 recoilless rifle production capacity, strengthening its ability to supply lightweight, versatile anti-armor systems to allied military customers worldwide.
- 2025: RTX Corporation launched an updated variant of its FGM-148 Javelin anti-tank guided missile, offering enhanced targeting capability and reduced launch signature for infantry customers.
- 2026: Nammo AS expanded its shoulder-launched munitions production capacity, strengthening its ability to supply NATO-aligned militaries with advanced portable anti-armor and support weapon systems.
- 2026: Rafael Advanced Defense Systems launched an updated variant within its SPIKE family of guided missile systems, offering extended range and improved countermeasure resistance for infantry and special operations customers.
Shoulder Fired Weapons Market key players are:
- Saab AB
- Thales Group
- Lockheed Martin Corporation
- RTX Corporation (Raytheon Technologies)
- MBDA
- Rafael Advanced Defense Systems Ltd.
- General Dynamics Corporation
- Rheinmetall AG
- FN Herstal S.A.
- Nammo AS
- Israel Aerospace Industries Ltd.
- Denel Dynamics (Denel SOC Ltd.)
- Roketsan A.S.
- China North Industries Group Corporation (Norinco)
- Kalashnikov Concern JSC
- KBP Instrument Design Bureau
- Aselsan A.S.
- Diehl Defence GmbH & Co. KG
- Elbit Systems Ltd.
- Bharat Dynamics Limited
Shoulder Fired Weapons Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 10.57 Billion |
| Market Size by 2035 | USD 18.10 Billion |
| CAGR | CAGR of 5.51% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Technology (Guided, Unguided) • By Weapon Type (Anti-Tank Guided Missile (ATGM) Launchers, Man-Portable Air Defense Systems (MANPADS), Recoilless Rifles, Rocket-Propelled Grenades) • By Range (Short, Medium, Long) • By Projectile Component (Launcher/Tube, Projectile/Missile, Fire-Control & Sighting Systems) • By End-User (Army, Navy, Air Force, Special Operations Forces, Homeland Security) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Saab AB, Thales Group, Lockheed Martin Corporation, RTX Corporation (Raytheon Technologies), MBDA, Rafael Advanced Defense Systems Ltd., General Dynamics Corporation, Rheinmetall AG, FN Herstal S.A., Nammo AS, Israel Aerospace Industries Ltd., Denel Dynamics (Denel SOC Ltd.), Roketsan A.S., China North Industries Group Corporation (Norinco), Kalashnikov Concern JSC, KBP Instrument Design Bureau, Aselsan A.S., Diehl Defence GmbH & Co. KG, Elbit Systems Ltd., Bharat Dynamics Limited. |
Frequently Asked Questions
The Shoulder Fired Weapons Market is expected to grow at a CAGR of 5.51% from 2026 to 2035.
The Shoulder Fired Weapons Market was valued at USD 10.57 Billion in 2025.
The market is driven by rising geopolitical tensions and border conflicts, increased military modernization programs, and growing demand for portable and lightweight weaponry.
The Guided segment dominated the Shoulder Fired Weapons Market in 2025, accounting for approximately 68.74% market share.
The North America region dominated the Shoulder Fired Weapons Market in 2025, supported by high defense spending and advanced military technologies.
