
Industrial Degreaser Market Report Scope & Overview:
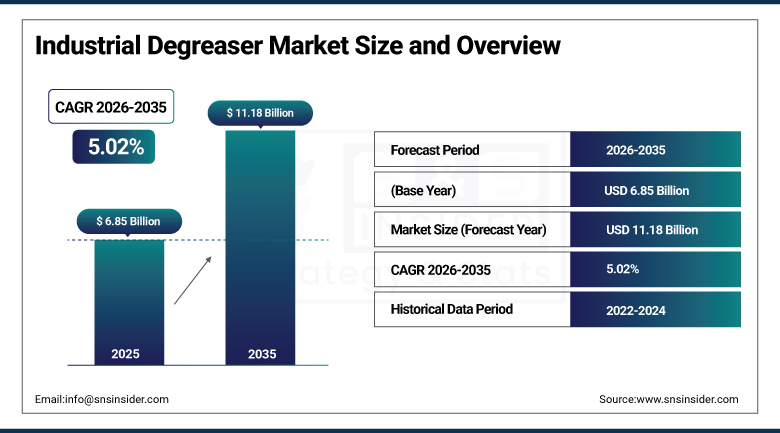
The Industrial Degreaser Market was valued at USD 6.85 Billion in 2025 and is expected to reach USD 11.18 Billion by 2035, growing at a CAGR of 5.02% from 2026 to 2035.
The Industrial Degreaser market is growing steadily due to increased adoption of effective degreasers by various sectors such as manufacturing, automotive, aerospace, and metal forming industries for cleaning their machines, tools, and components before coating, assembling, welding, and inspecting them. The increasing automation and complexity of the precision components used in the production process of automotive, electronic, and aerospace manufacturing industries are encouraging operators of facilities to use degreasers that can provide efficient performance in terms of fast cycle times and compatible substrates. Increased stringent regulations for occupational safety and VOC emissions in North America, Europe, and some regions of Asia Pacific are changing the formulation trend towards eco-friendly solutions.
⮞Zep Inc. and CRC Industries both expanded their water-based, low-VOC degreaser portfolios in 2026 to help automotive, metal-fabrication, and food-processing facilities meet tightening workplace-safety and environmental-discharge regulations while maintaining industrial-grade cleaning performance.
To Get more information On Industrial Degreaser Market - Request Free Sample Report
Industrial Degreaser Market Trends
-
Rising shift toward water-based and bio-based degreaser formulations is reshaping product development priorities.
-
Growing adoption of aerosol and precision-dispensing formats is expanding spot-cleaning and MRO applications.
-
Increasing electric-vehicle and battery-component manufacturing is driving demand for ultra-clean surface-preparation degreasers.
-
Tightening VOC and workplace-safety regulations are accelerating the phase-out of chlorinated solvent chemistries.
-
Growing preference for concentrated, dilutable degreaser products is reducing packaging and logistics costs for industrial buyers.
U.S. Industrial Degreaser Market Outlook
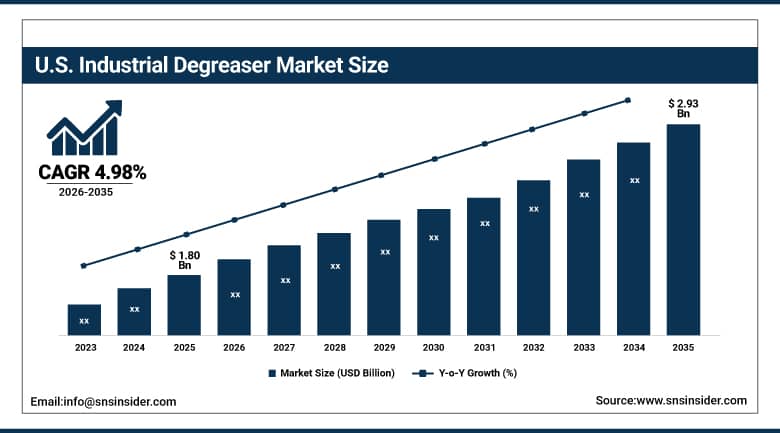
The U.S. Industrial Degreaser Market was valued at USD 1.80 Billion in 2025 and is projected to reach USD 2.93 Billion by 2035, growing at a CAGR of 4.98% during 2026–2035.
The domestic manufacturers and MRO service providers in U.S. are still shifting towards water and biological based degreasers owing to the toughening up of EPA regulations regarding the emission of volatile organic compounds and hazardous air pollutants under state-level air quality programs in California and elsewhere that impose strict limits on solvents use. High levels of manufacturing of automobiles, airplanes, and heavy machinery along with the increasing investments in electric cars and semiconductor manufacturing are ensuring a sustained demand for degreasers. Increasing preference for safer, OSHA compliant and low toxicity products from facility managers coupled with increased outsourcing of industrial maintenance activities is also driving the demand for degreasers.
⮞CRC Industries expanded its U.S. manufacturing capacity in 2026 to scale production of its HD Green water-based degreaser line, strengthening its ability to supply automotive, marine, and general-maintenance customers seeking VOC-compliant cleaning solutions nationwide.
Industrial Degreaser Market Segment Analysis
-
By Product Type, Solvent-Based dominated the Industrial Degreaser Market with a 47.60% share in 2025, while Water-Based is the fastest-growing product segment with a CAGR of 6.30% from 2026–2035.
-
By Form, Liquid dominated the Industrial Degreaser Market with a 61.40% share in 2025, while Aerosol is the fastest-growing form segment with a CAGR of 6.00% from 2026–2035.
-
By Application, Metal Fabrication & Machinery dominated the Industrial Degreaser Market with a 33.90% share in 2025, while Automotive & Transportation is the fastest-growing application segment with a CAGR of 6.20% from 2026–2035.
-
By End-Use Industry, Automotive dominated the Industrial Degreaser Market with a 29.40% share in 2025, while Aerospace is the fastest-growing end-use segment with a CAGR of 6.50% from 2026–2035.
By Product Type, Solvent-Based led the market, while Water-Based is the fastest-growing segment.
The Solvent-Based segment led the Industrial Degreaser Market with a 47.60% revenue share in 2025. Solvent-based degreasers prevail owing to their superior ability to dissolve grease, fast evaporation properties, and effectiveness as proven in numerous cases of heavy-duty industrial cleaning, rendering them an ideal solution for high-volume metal fabrication, machinery refurbishment, and maintenance of old machinery.
The Water-Based segment is expected to register the fastest CAGR of 6.30% during the forecast period 2026-2035. Increasing regulation demanding the minimization of VOC emissions and workplace exposure risks has led to a rapid uptake of water-based products in automotive, food-processing, and general industry maintenance, as companies opt for non-flammable and low-smelling degreasers meeting tougher workplace safety and wastewater discharge requirements.
⮞In February 2026, Henkel launched BONDERITE C-AD 20202, a low-temperature surfactant for industrial dip degreasing that operates at 35–40°C rather than conventional 60–65°C, reducing process energy requirements while maintaining cleaning performance for complex industrial components.
By Form, Liquid led the market, while Aerosol is the fastest-growing segment.
The Liquid segment held a market share of 61.40% of the Industrial Degreaser Market in 2025. Degreasers in liquid form are the most common cleaning agents used for bulk applications such as washing machines, dip tanks, and so on because of their economic value, easy dilutability, and use in automatic dispensers and recyclers.
The Aerosol segment is anticipated to grow at the fastest rate during the forecast period 2026-2035, at a CAGR of 6.00%. Increasing popularity of portable and pre-packaged cleaning solvents for applications in electronics assembly, field repair, and machinery servicing is leading to rapid adoption of aerosol systems because technicians prefer easy use to the hassle of using bulk liquid containers.
⮞Development: In May 2025, CRC Industries introduced Chlor-Free Universal Degreaser, a non-chlorinated industrial aerosol featuring a PowerJet spray nozzle, rapid evaporation and residue-free cleaning for industrial equipment, helping maintenance technicians remove grease and oil while meeting requirements across all 50 U.S. states.
By Application, Metal Fabrication & Machinery led the market, while Automotive & Transportation is the fastest-growing segment.
The Metal Fabrication & Machinery segment dominated the Industrial Degreaser Market with a revenue share of 33.90% in 2025. A high level of degreaser consumption for activities such as pre-welding, pre-coating, and machine tools maintenance at heavy manufacturers will support demand because, for example, fabricators need clean surfaces for the coatings to adhere and for good welds to be made.
The Automotive & Transportation segment is expected to register the fastest CAGR of 6.20% during the forecast period 2026-2035. Expanding electric-vehicle and battery-component manufacturing, combined with growing aftermarket maintenance and refurbishment activity, is driving above-average growth as automakers and service centers increasingly specify low-residue, fast-drying degreasers suited to sensitive electronic and battery-pack assemblies.
⮞In March 2025, Hyundai Motor Group announced a USD 21 billion U.S. investment for 2025–2028, including USD 9 billion to expand automobile production capacity to 1.2 million vehicles annually, strengthening the manufacturing base for automotive parts cleaning and industrial surface preparation.
By End-Use Industry, Automotive led the market, while Aerospace is the fastest-growing segment.
The Automotive segment dominated the Industrial Degreaser Market with a revenue share of 29.40% in 2025. The steady vehicle production globally, growth in remanufacturing components, and extensive application of degreasers in cleaning engines, transmissions, and body shops have become some of the factors which have remained integral in driving the demand.
The Aerospace segment is expected to register the fastest CAGR of 6.50% during the forecast period 2026-2035. Rising aircraft production rates, growing MRO activity across commercial and defense fleets, and stringent surface-cleanliness specifications required for composite and precision-machined aerospace components are driving accelerated adoption of specialty, low-residue degreaser formulations across the aerospace supply chain.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.30% |
|
Europe |
Germany |
23.40% |
|
Asia Pacific |
China |
39.20% |
|
Middle East & Africa |
UAE |
22.60% |
|
Latin America |
Brazil |
33.10% |
North America Industrial Degreaser Market Insights
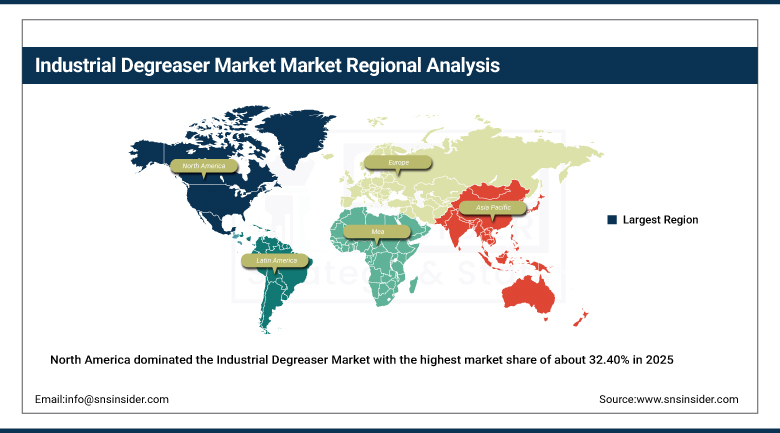
North America dominated the Industrial Degreaser Market with the highest market share of about 32.40% in 2025, backed by the region’s advanced manufacturing capabilities, substantial automotive and aerospace manufacturing facilities, and the regulatory focus on occupational safety and VOC emissions reduction through regulations like those of the EPA regarding air quality and OSHA hazard communication, which favors the use of low-toxicity, water-based degreasing chemicals. Consistent industrial maintenance expenditures, investments in electric vehicle and semiconductor manufacturing, and the presence of an extensive base of degreaser formulators and distributors keep degreaser use strong in the region.
The US was the leading country within the North America Industrial Degreaser Market in 2025 with a market share of 81.30% of the regional market, motivated by an abundance of domestic manufacturing capacity, increased automotive and aerospace maintenance requirements, and a movement towards low VOC content degreasers at the facility level. Canada is helping spur regional growth via its own automotive parts and heavy machinery manufacturing industry.
⮞In February 2025, Jelmar introduced CLR PRO MAX Industrial Degreaser, a concentrated industrial cleaning product formulated to penetrate heavy grease, oil and grime on machinery, equipment, appliances and industrial surfaces, expanding the company's professional cleaning portfolio for maintenance and manufacturing customers.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Industrial Degreaser Market Insights
Europe region was a major contributor to the Industrial Degreaser Market in 2025, expected to register comparatively higher growth for eco-certified, biodegradable degreaser formulations during the forecast period. This is attributed to the region's stringent REACH chemical-registration requirements, well-established automotive and industrial manufacturing base, and growing enterprise preference for sustainable cleaning chemistries across member states pursuing broader decarbonization and workplace-safety objectives.
Germany is one of the major markets in Europe owing to its strong automotive and precision-engineering manufacturing base and presence of leading specialty-chemical formulators serving both domestic and international industrial customers. Other countries such as France, Italy, and the United Kingdom, home to extensive automotive and aerospace supply chains, are also contributing to market growth through sustained maintenance and production activity.
⮞In January 2025, Germany's Federal Institute for Risk Assessment confirmed that the Unique Formula Identifier requirement would extend to previously marketed hazardous consumer and commercial chemical mixtures from January 1, 2025. Purely industrial-use products are exempt, limiting the measure's direct relevance to industrial degreasers.
Asia Pacific Industrial Degreaser Market Insights
Asia Pacific Industrial Degreaser Market is expected to witness the fastest growth rate 6.55% during the forecast period 2026-2035. Market growth is driven by rapidly expanding automotive, electronics, and heavy-machinery manufacturing activity, large-scale domestic chemical production capacity, and increasing adoption of compliant cleaning chemistries across the region's major and emerging manufacturing economies pursuing rapid industrialization.
China is one of the main growth drivers in the Asia Pacific Industrial Degreaser Market, owing to its massive domestic manufacturing ecosystem and rapidly expanding electric-vehicle and electronics production base supporting both local and export-oriented degreaser demand. India and Southeast Asian countries, both witnessing strong industrial and automotive manufacturing growth, are also contributing to regional growth through expanding production capacity and rising adoption of specialty degreasing chemistries.
⮞In December 2025, China's Ministry of Ecology and Environment announced that the use of hydrochlorofluorocarbons (HCFCs), including HCFC-containing mixtures, as industrial cleaning agents would be prohibited from July 1, 2026, accelerating the transition away from these legacy cleaning solvents.
Middle East & Africa and Latin America Industrial Degreaser Market Insights
Middle East & Africa and Latin American regions are gradually expanding industrial degreaser adoption as manufacturing and infrastructure investment grows across both regions, supported by increasing automotive, oil & gas, and heavy-equipment maintenance activity and growing government focus on workplace-safety and environmental-compliance standards.
Brazil is set to be a prominent Latin American market fueled by its substantial automotive and heavy-equipment manufacturing industry requiring consistent, high-performance degreasing solutions across production and maintenance operations. The Middle East & Africa region has the UAE and Saudi Arabia investing in expanding oil & gas, petrochemical, and industrial infrastructure that is gradually increasing demand for specialty industrial degreaser formulations across their diversifying economies.
⮞In May 2025, Emirates Development Bank announced plans to mobilize more than AED 60 billion in industrial capital expenditure, including over AED 20 billion in greenfield investment, to expand manufacturing capacity and strengthen industrial supply chains across the United Arab Emirates.
Market Dynamics
Growth Drivers: Rising industrial automation and regulatory compliance driving market growth
The rising pace of industrial automation and manufacturing output across developed and emerging economies, combined with tightening workplace-safety and environmental regulations that favor low-toxicity, compliant chemistries, are among the primary drivers of the Industrial Degreaser Market. Industrial degreasers provide essential surface-preparation and maintenance functions across automotive, aerospace, metal fabrication, and electronics manufacturing, ensuring coating adhesion, equipment reliability and product quality across virtually every major industrial application, from high-volume automotive assembly through precision aerospace-component cleaning.
Technological advancements in surfactant chemistry and biodegradable formulation engineering have significantly increased degreaser performance, with recent innovations improving grease-cutting efficiency and drying speed across commercial cleaning processes. Rising adoption of water-based and bio-based chemistries as regulators tighten VOC and hazardous air pollutant limits, growing electric-vehicle and battery-component manufacturing requiring ultra-clean surface preparation, and continued investment in concentrated, dilutable product formats are further supporting demand across the forecast period, as compliant chemistries continue displacing legacy chlorinated solvent systems across an increasingly broad range of industrial applications.
⮞In April 2025, South Africa's ACTOM opened a new industrial fan manufacturing facility in Germiston following a R32 million investment, expanding domestic industrial production and reinforcing demand potential for equipment maintenance and industrial cleaning products across manufacturing operations.
Restraints: Raw material price volatility and regulatory compliance costs limiting market expansion
One of the most critical obstacles to market growth comes in the form of volatile petrochemical feedstock and surfactant pricing tied to global commodity and energy markets, which directly affects degreaser manufacturing economics and creates pricing uncertainty for both formulators and industrial buyers negotiating long-term supply contracts.
Moreover, the substantial compliance costs associated with reformulating legacy solvent-based products to meet evolving VOC, hazardous-air-pollutant, and wastewater-discharge regulations continue to strain smaller formulators competing against larger, well-capitalized chemical manufacturers. Besides the high technical requirements involved in engineering water-based and bio-based degreasers that match solvent-based cleaning performance across varying industrial substrates require considerable ongoing research and development investment from producers.
Opportunities: Expansion of bio-based chemistries and precision-cleaning formats creating new growth avenues
The growth in environmental and safety norms, increase in demand for aerosols and dispensing products, and increased focus on innovation through development of surfactants will offer ample opportunity for growth in the Industrial Degreaser Market. The demand for environmentally friendly products will continue to fuel growth as environment-related laws become more stringent around the world.
There is immense potential for growth in the development of ultra-clean, low-residue degreaser formulations tailored to electric-vehicle battery and semiconductor manufacturing, offering formulators new value-added product differentiation opportunities. The increase in automotive, electronics, and heavy-machinery manufacturing activity across emerging economies of Asia Pacific and Latin America, along with government efforts toward workplace-safety compliance, will drive growth in demand for advanced industrial degreaser products.
Recent Developments
-
2025: WD-40 Company expanded its WD-40 Specialist Industrial-Strength Degreaser line with a fast-evaporating, non-chlorinated formula for electronics and precision-machinery maintenance applications.
-
2026: Quaker Houghton launched a new aqueous parts-washing degreaser under its Coral brand, designed for high-throughput automotive component cleaning lines across North America and Europe.
Industrial Degreaser Companies are:
-
Ecolab Inc.
-
WD-40 Company
-
CRC Industries, Inc.
-
Zep Inc.
-
Illinois Tool Works Inc. (ITW Sprayon)
-
Quaker Houghton
-
Chem-Trend L.P.
-
Diversey Holdings, Ltd.
-
Stoner Inc.
-
Simple Green (Sunshine Makers, Inc.)
-
Kyzen Corporation
-
Safety-Kleen Systems, Inc. (Clean Harbors)
-
BASF SE
-
Solvay SA
-
Sasol Limited
-
National Chemical Laboratories, Inc.
-
Cortec Corporation
-
Enviro Tech International, Inc.
Industrial Degreaser Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 6.85 Billion |
| Market Size by 2035 | USD 11.18 Billion |
| CAGR | CAGR of 5.02% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Solvent-Based, Water-Based & Bio-Based/Green) • By Form (Liquid, Aerosol, Powder & Gel) • By Application (Metal Fabrication & Machinery, Automotive & Transportation, Electronics, Food Processing & Others) • By End-Use Industry (Automotive, Manufacturing, Aerospace, Marine & Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ecolab Inc., WD-40 Company, CRC Industries, Inc., Zep Inc., 3M Company, Illinois Tool Works Inc. (ITW Sprayon), Quaker Houghton, Chem-Trend L.P., Diversey Holdings, Ltd., Stoner Inc., Simple Green (Sunshine Makers, Inc.), Kyzen Corporation, Safety-Kleen Systems, Inc. (Clean Harbors), BASF SE, Solvay SA, Dow Inc., Sasol Limited, National Chemical Laboratories, Inc., Cortec Corporation, Enviro Tech International, Inc. |
Frequently Asked Questions
