
Semiconductor Bonding Market Scope and Overview
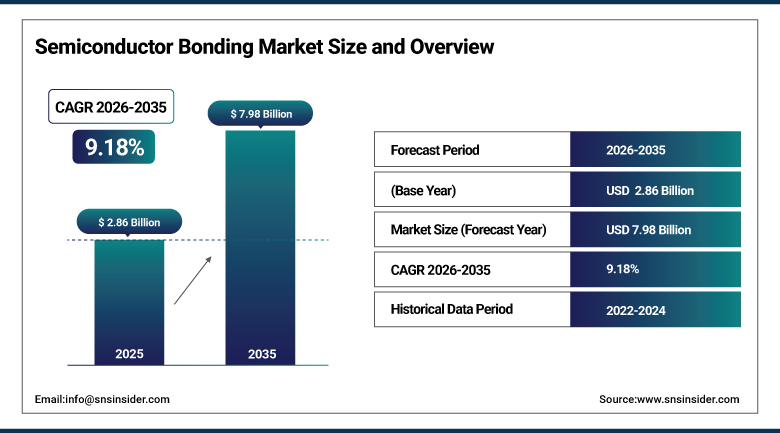
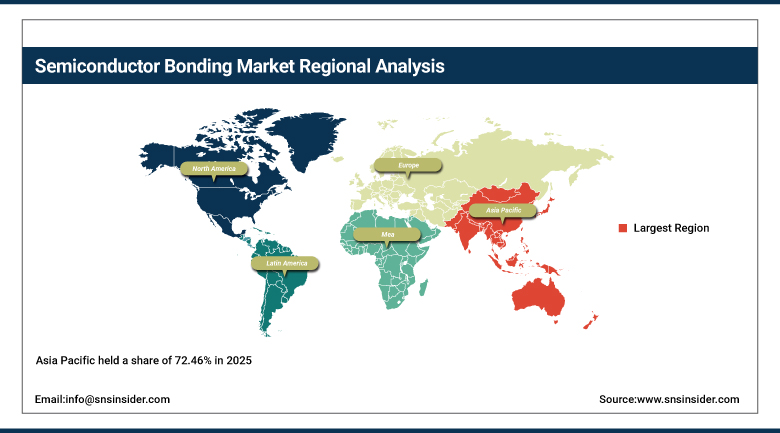
The Semiconductor Bonding Market was valued at USD 2.86 Billion in 2025 and is estimated at USD 3.62 Billion in 2026. The market is forecast to reach USD 7.98 Billion by 2035, registering a CAGR of 9.18% from 2026 to 2035. Growth reflects the build-out of high-bandwidth memory and advanced packaging for artificial intelligence, the move from thermocompression toward hybrid bonding, and new back-end capacity in several countries. Asia Pacific led the market with a share of 72.46% in 2025, while North America held 12.73% and Europe held 10.39%. Demand is expected to remain strong across the forecast period.
To Get more information Semiconductor Bonding Market - Request Free Sample Report
Key Market Trends & Insights
-
By equipment type: Die Bonders held the largest market share of 34.27% in 2025.
-
By application: Logic and Memory ICs held the largest market share of 52.34% in 2025.
-
By end user: OSATs held the largest market share of 54.18% in 2025.
-
By region: Asia Pacific held the largest regional share of 72.46% in 2025, followed by North America at 12.73% and Europe at 10.39%.
-
Asia Pacific is projected to register the fastest regional CAGR of 9.87% from 2026 to 2035.
-
The U.S. is the leading country market in North America, supported by new advanced packaging capacity in Arizona and federal packaging programs.
Growth Outlook
SEMI reported on 16 December 2025 that assembly and packaging equipment sales reached USD 6.00 Billion in 2025, a rise of 19.60%, and forecast further growth of 9.20% in 2026 and 6.90% in 2027, with China, Taiwan, and South Korea the top destinations and Korea driven by high-bandwidth memory. Bonding tools sit at the center of that growth, since stacked memory and chiplet packages need more die attach, thermocompression, and hybrid bonding steps per device than conventional packages, and tool makers reported record order levels through the third quarter of 2026.
Public programs add capacity outside the leading hubs. India approved Semicon 2.0 on 15 July 2026 with an outlay of INR 1.275 lakh crore, including support for assembly, test, and packaging units and for equipment makers, while the Korean National Assembly passed a special act for the semiconductor industry on 29 January 2026 covering packaging, materials, and equipment. These measures widen the customer base for wire, die, and thermocompression bonders beyond the traditional customers in Taiwan, Korea, and China. Local equipment purchasing follows.
Market Dynamics
Driver: AI Memory Stacking, Hybrid Bonding Adoption, and Strong Equipment Order Books Lift Demand
Artificial intelligence accelerators depend on stacked high-bandwidth memory and large chiplet packages, and each generation raises the number of bonding steps. ASMPT reported third quarter 2026 revenue of HKD 5.25 Billion, up 48.70%, with bookings of HKD 8.85 Billion and a book-to-bill ratio of 1.69, the highest since the first quarter of 2021. Besi reported third quarter 2026 orders of EUR 342.60 Million, up 96.00% from a year earlier, and said hybrid bonding orders this year had more than doubled the total for all of 2025. Foundries are also placing orders for chip-on-wafer tools for their own packaging lines. Orders are rising quickly.
Memory makers are also placing large thermocompression bonder orders. Press reports on 9 June 2026 said SK hynix ordered thermocompression bonders worth KRW 44.20 Billion from Hanmi Semiconductor for its fourth generation HBM ramp, and Hanwha Semitech won two contracts from the same customer in March 2025. Kulicke and Soffa reported fiscal third quarter 2026 revenue of USD 330.40 Million against USD 148.40 Million a year earlier, and said demand was improving across all end markets, which shows that recovery extends to wire and die bonding. Power module makers serving electric vehicles add further orders for die bonders and sintering tools, so growth is not limited to memory customers alone.
Restraint: Order Lumpiness, Customer Concentration, and Export Controls Add Risk to Equipment Spending
Bonding equipment demand is lumpy and concentrated in a few customers. Besi guided fourth quarter 2026 revenue flat at about EUR 283.00 Million, below consensus, and said some customers asked to move deliveries to match first half 2027 production. ASMPT cited one-off large orders and longer lead times in its October 2026 results, and investors questioned whether memory makers will adopt hybrid bonding for HBM soon, which could delay the largest growth opportunity for the most advanced tools. Tool makers therefore face swings in revenue from quarter to quarter, and planning capacity or inventory becomes harder when a single customer controls a large part of the order book.
Supply and trade constraints also limit growth. SUSS MicroTec cut its 2026 sales guidance to EUR 405.00 Million to EUR 425.00 Million on component supply constraints and the relocation of production from Garching to Taiwan and Sternenfels, and SEMI expects China equipment sales to decline gradually from 2026. The U.S. Bureau of Industry and Security extended on 9 April 2026 the deadline for approved IC designers to 31 December 2026, which keeps rules on advanced logic exports to OSATs and foundries under review. Equipment suppliers also face higher compliance costs when shipping advanced tools across borders, and some customers may qualify local alternatives over time.
Opportunity: Hybrid Bonding, New Back-End Hubs, and Power Device Packaging Create Fresh Demand
Hybrid bonding offers the largest long-term opening. EV Group and imec reported on 28 May 2026 wafer-to-wafer hybrid bonding at 200 nanometer interconnect pitch with record overlay accuracy, and Besi counted 21 hybrid bonding customers by the second quarter of 2026, including a new hyperscaler, up from 15 at the end of 2025. ASMPT also announced on 5 February 2026 an order for two ultrafine-pitch thermocompression tools for chip-to-wafer bonding, which shows that chip-to-wafer processes are moving toward production at several suppliers. Equipment makers that offer both thermocompression and hybrid tools can serve customers through the transition without losing the account.
New back-end hubs and power devices add further room. TSMC and Amkor agreed on 17 June 2026 on a ten-year Arizona advanced packaging partnership, Malaysia tabled Budget 2027 on 9 October 2026 with measures for advanced packaging, and Yamaha Motor launched a hybrid placer and die bonder for 12-inch wafers on 1 March 2026 citing rising electric vehicle power module demand. Each of these developments creates orders from customers that previously bought few advanced bonding tools. Government funding in India, Japan, Korea, and Malaysia also reduces the capital cost for local OSATs and widens the buyer base for mid-range bonders.
Market Characteristics & Concentration
The Semiconductor Bonding Market is Moderately Consolidated. ASMPT, Besi, Kulicke and Soffa, Hanmi Semiconductor, EV Group, and SUSS MicroTec supply most advanced tools, while Hanwha Semitech, Tokyo Electron, Yamaha Motor, and several Japanese and European makers serve specific bonding techniques. Wire bonding is led by a few established suppliers, while hybrid and thermocompression bonding are led by even fewer. Regional suppliers in Japan, Korea, and China compete on price in lower accuracy tools.
Technology leadership decides share. Customers qualify a bonder for a specific package type, and switching requires months of process work, so installed base and application know-how matter. Prices for advanced tools are high, and suppliers with accuracy of a few hundred nanometers for placement hold clear pricing power in hybrid bonding. Service networks, spare parts, and process engineers at the customer site also support loyalty, since a bonder runs for many years once it is qualified.
Ownership and alliances are shifting. Applied Materials took about a 9.00% stake in Besi in April 2025, Hanwha Semitech entered the thermocompression bonder market in March 2025 and is now in patent mediation with Hanmi, and TSMC is working with OSATs on Arizona capacity. Government support is also becoming part of competition. Memory makers and foundries now co-develop tools with suppliers, which makes joint roadmaps an important source of competitive advantage.
Analyst Perspective
The semiconductor bonding market is changing from a steady equipment business into a cyclical growth segment tied to artificial intelligence packaging. Die Bonders will keep the largest share because every package needs die attach, while Hybrid Bonders will grow fastest as stacked memory and logic move toward direct copper connections. Logic and Memory ICs will remain the largest application, and OSATs will remain the largest buyers, but foundries will grow fastest as they bring packaging in-house. Asia Pacific will remain dominant. Suppliers with hybrid and thermocompression capability will gain the most. An SNS Insider Analyst, Santosh Bhul, commented, "Bonding has moved to the center of chip performance, and suppliers that can deliver hybrid and thermocompression tools at volume will set the pace for the next decade."
Segment Analysis
Equipment Type Insights
Die Bonders accounted for the largest share of 34.27% in 2025. Die attach is required in nearly every package, from power modules and sensors to logic devices, and high-accuracy placement tools are used for flip chip, multichip, and chiplet assembly. Suppliers such as Besi, ASMPT, Yamaha Motor, and Fasford sell large installed bases to OSATs and device makers, and replacement and capacity additions follow unit demand for consumer, automotive, and data center products. Their broad use across package types gives them steady order volume through the cycle. They also benefit from steady replacement cycles.
Hybrid Bonders are projected to grow at the fastest CAGR of 21.38% from 2026 to 2035. Direct copper-to-copper bonding removes solder bumps, allows finer interconnect pitch, and improves bandwidth and heat flow, which suits high-bandwidth memory, image sensors, and logic stacking. Besi counted 21 hybrid customers by mid-2026, and EV Group and imec showed wafer-to-wafer bonding at 200 nanometer pitch. The installed base is small today, so each new customer and process qualification adds large order growth. Suppliers are scaling up service teams to support early customers and shorten qualification time.
Application Insights
Logic and Memory ICs accounted for the largest share of 52.34% in 2025. Processors, accelerators, and stacked memory use the most advanced and highest value bonders, including thermocompression tools for high-bandwidth memory and flip chip tools for large processors. Artificial intelligence servers, smartphones, and personal computers all require high volumes of packaged logic and memory, and capital spending by memory makers and foundries is concentrated in this application. Orders for such tools therefore represent the largest portion of equipment revenue in most reporting periods. Capacity additions in memory also raise tool counts.
Photonics and LED are projected to grow at the fastest CAGR of 11.26% from 2026 to 2035. Optical transceivers, co-packaged optics, lidar, and micro LED displays need accurate placement of lasers, photodiodes, and light emitting dies on silicon and glass substrates. Data center networks are moving to higher optical speeds, and device makers are investing in high-accuracy bonding lines to reduce alignment loss. The base is smaller than logic and memory, so rising adoption of optical interconnects delivers faster growth for specialized bonders. Optical module makers are also placing early orders for dedicated lines.
End User Insights
OSATs accounted for the largest share of 54.18% in 2025. Outsourced assembly and test providers in Taiwan, China, Malaysia, South Korea, and Southeast Asia buy most wire, die, and flip chip bonders and are adding thermocompression capacity for advanced packages. Fabless chip designers rely on them for packaging, and customers such as TSMC are signing long-term agreements, as shown by the Amkor partnership in Arizona. New OSAT plants in India, Malaysia, and the United States add further capacity and purchase equipment in large batches during build-outs. They also buy service contracts and spares in large volumes.
Foundries are projected to grow at the fastest CAGR of 12.04% from 2026 to 2035. Leading foundries are bringing advanced packaging in-house, using chip-on-wafer and wafer-on-wafer stacking for accelerators, and they are installing hybrid and thermocompression bonders in their own packaging plants. TSMC plans its own Arizona advanced packaging facility, and Rapidus operates a back-end prototype line in Japan. Control over packaging allows foundries to tune performance and yield, and capital budgets are large enough to place early orders for new tools. Packaging outsourcing is therefore becoming less common at the leading edge.
Regional Insights
North America held a share of 12.73% of the market in 2025. The region has smaller back-end capacity than Asia, but demand is growing as TSMC, Amkor, Micron, and others build advanced packaging and memory facilities in Arizona, Idaho, and New York. The region is also home to Applied Materials, a major strategic investor in Besi, and Kulicke and Soffa serves wire and advanced bonding customers across several continents. Federal incentives and onshoring plans are lifting orders for bonding tools.
U.S. Semiconductor Bonding Market
The U.S. Semiconductor Bonding Market was valued at USD 322.06 Million in 2025 and is projected to expand at a CAGR of 7.94% from 2026 to 2035. NIST finalized USD 300.00 Million under the first notice of funding for the National Advanced Packaging Manufacturing Program, with awardees including Absolics, Applied Materials, and Arizona State University. TSMC and Amkor agreed on 17 June 2026 on a ten-year Arizona packaging partnership, with the Amkor campus on 104 acres and production planned for 2028. Federal programs support further packaging growth. Packaging tools remain imported.
The Bureau of Industry and Security published a final rule on 9 April 2026 that extends to 31 December 2026 the deadline to apply as an approved IC designer, which affects how advanced logic chips are routed through U.S. and foreign OSATs. SEMI forecast on 16 December 2025 that global assembly and packaging equipment would rise 9.20% in 2026. Local bonder demand therefore depends on new Arizona facilities, memory expansion, and compliance with export rules. Further orders will come from new memory plants. Compliance planning remains important for buyers. Memory expansion remains central.
Europe Semiconductor Bonding Market
Europe accounted for 10.39% of the market in 2025, supported by Infineon, STMicroelectronics, NXP, Bosch, and ASML in the supply chain and by leading equipment makers Besi and SUSS MicroTec. The European Commission published its Chips Act 2.0 proposal on 3 June 2026 to strengthen mainstream chips, build capacity in advanced technologies, and reduce dependencies. Power, automotive, and sensor packaging dominate local demand for die and wire bonders. Local suppliers also serve customers in Asia and North America with high-accuracy bonders for advanced packages.
SUSS MicroTec reported on 5 November 2026 nine-month order intake of EUR 633.50 Million and an order book of EUR 600.60 Million, while moving production from Garching to Taiwan and Sternenfels. Besi reported on 22 October 2026 third quarter orders of EUR 342.60 Million. Europe is therefore both an equipment supplier and a modest buyer, with demand tied to power devices. Germany, the Netherlands, and Austria lead equipment innovation, while Infineon, STMicroelectronics, and Bosch plants in Germany, Italy, and France buy die and wire bonders for power devices and automotive sensors.
Asia Pacific Semiconductor Bonding Market
Asia Pacific held a share of 72.46% in 2025 and is projected to register the fastest regional CAGR of 9.87% from 2026 to 2035, led by Taiwan, South Korea, China, Japan, Malaysia, and India. Most OSATs, memory makers, and foundries operate in the region. SEMI reported on 16 December 2025 that China, Taiwan, and Korea were the top equipment destinations, with Korea driven by high-bandwidth memory. Japan approved on 11 April 2026 an additional JPY 631.50 Billion for Rapidus.
South Korea passed its semiconductor special act on 29 January 2026, India approved Semicon 2.0 on 15 July 2026 with INR 1.275 lakh crore, and Malaysia tabled Budget 2027 on 9 October 2026 with a RM100.00 Million strategic fund. Hanmi Semiconductor reported 2025 revenue of KRW 576.70 Billion, and ASMPT reported record bookings in October 2026. Demand is anchored by memory stacking and AI packaging. Taiwan remains the largest buyer through TSMC and large OSATs.
Get Customized Report as per Your Business Requirement - Enquiry Now
Latin America Semiconductor Bonding Market
Latin America accounted for 2.67% of the market in 2025, led by Mexico, Brazil, and Costa Rica. Demand comes from small assembly and test operations, automotive electronics, and electronics manufacturing, and most bonding equipment is imported. SEMI reported on 16 December 2025 that equipment spending is concentrated in China, Taiwan, and Korea, which leaves Latin America as a small buyer. Growth depends on nearshoring of electronics assembly and on any new packaging plants in Mexico and Brazil.
Middle East & Africa Semiconductor Bonding Market
The Middle East and Africa held 1.75% of the market in 2025, led by Israel, Saudi Arabia, the United Arab Emirates, and Oman. Demand is limited to small packaging lines, research facilities, and defense electronics. Invest Oman has invited international OSAT companies to build an assembly facility estimated at USD 130.00 Million to USD 140.00 Million, with tax exemptions and utility subsidies. SEMI data of 16 December 2025 show equipment spending concentrated in Asia. Growth depends on a few new projects.
Key Semiconductor Bonding Market Company Insights
Companies in the semiconductor bonding market are focusing on hybrid and thermocompression bonding for AI memory and logic stacking, capacity additions in Asia and Europe, and customer qualification with leading memory makers and foundries. Order books are strong, but delivery timing, supply constraints, and customer concentration shape quarterly results. Alliances with front-end toolmakers are also growing.
Key Semiconductor Bonding Companies:
-
ASMPT
-
BE Semiconductor Industries (Besi)
-
Kulicke and Soffa Industries
-
Hanmi Semiconductor
-
Hanwha Semitech
-
EV Group
-
SUSS MicroTec
-
Tokyo Electron
Recent Developments
-
In November 2026, SUSS MicroTec reported nine-month order intake of EUR 633.50 Million and an order book of EUR 600.60 Million, and revised 2026 sales guidance to EUR 405.00 Million to EUR 425.00 Million.
-
In October 2026, ASMPT reported third quarter revenue of HKD 5.25 Billion, bookings of HKD 8.85 Billion, and a book-to-bill ratio of 1.69, and guided fourth quarter revenue of USD 670.00 Million to USD 730.00 Million.
-
In October 2026, Besi reported third quarter orders of EUR 342.60 Million and revenue of EUR 283.40 Million, and announced a new EUR 100.00 Million share buyback from 27 October 2026.
-
In August 2026, Kulicke and Soffa reported fiscal third quarter revenue of USD 330.40 Million and guided fiscal fourth quarter revenue of about USD 375.00 Million.
-
In June 2026, Hanmi Semiconductor received a KRW 44.20 Billion thermocompression bonder order from SK hynix for HBM4, as reported by the press.
-
In May 2026, EV Group and imec reported wafer-to-wafer hybrid bonding at 200 nanometer interconnect pitch with record overlay accuracy.
-
In February 2026, ASMPT announced an order for two ultrafine-pitch thermocompression chip-to-wafer bonders.
-
In April 2025, Applied Materials announced a stake of about 9.00% in Besi as a strategic long-term investment.
Scope and Research Methodology
The study defines the Semiconductor Bonding Market as new back-end bonding equipment sold to chip makers and assembly providers, covering die bonders, flip chip and thermocompression bonders, hybrid bonders, wire bonders, and permanent wafer bonders. Temporary bonding and debonding tools are shown as an adjacent line. Wire bonding materials, die attach materials, spares, and services are excluded. Revenue is measured at equipment maker selling prices, the forecast period runs from 2026 to 2035, and all values are expressed in USD. Services, software, and contract bonding fees are not counted in the value of the market, and equipment bought as refurbished is shown separately. Temporary bonding tools are reported separately.
The research program combines secondary and primary research. Secondary research draws on company results and order disclosures, SEMI equipment data, regulator and government notices, conference papers, and trade press. Primary research consists of structured interviews and surveys with equipment makers, OSATs, memory makers, foundries, and process engineers. These inputs inform tool shipments, selling prices, order timing, and technology adoption by package type. Company disclosures are cross-checked with public filings and trade data where available, and conflicting inputs are settled through follow-up calls with respondents.
Market engineering follows a bottom-up build from equipment maker bonding revenue and tool shipments by class, cross-checked top-down against SEMI assembly and packaging equipment data. Segment shares are estimated from reported order mix and customer capacity plans, and regional values are aligned to the location of installed tools so that all regions add up to the global total. Published estimates for this market differ widely because of scope, so this study states its boundaries and each estimate passes through analyst review. Currency conversion uses yearly mean rates for historical years and constant rates for forecast years, and scenario testing is applied to memory capital spending, export rules, and hybrid bonding adoption assumptions.
Semiconductor Bonding Market Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.86 Billion |
| Market Size by 2035 | USD 7.98 Billion |
| CAGR | CAGR of 9.18% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Equipment Type (Die Bonders, Wire Bonders, Flip Chip and Thermocompression Bonders, Wafer Bonders, and Hybrid Bonders) • By Application (Logic and Memory ICs, Power and RF Devices, MEMS and Sensors, and Photonics and LED) • By End User (OSATs, IDMs, and Foundries) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ASMPT, BE Semiconductor Industries (Besi), Kulicke and Soffa Industries, Hanmi Semiconductor, Hanwha Semitech, EV Group, SUSS MicroTec, Tokyo Electron |

Frequently Asked Questions
The market was valued at USD 2.86 Billion in 2025 and is projected to reach USD 7.98 Billion by 2035.
The market is expected to register a CAGR of 9.18% from 2026 to 2035.
Asia Pacific led the market with a 72.46% share in 2025, ahead of North America at 12.73% and Europe at 10.39%.
Asia Pacific is expected to grow the fastest, at a CAGR of 9.87% from 2026 to 2035.
Die Bonders led the equipment type segment with a 34.27% share in 2025, and Logic and Memory ICs led the application segment.
Key players include ASMPT, Besi, Kulicke and Soffa, Hanmi Semiconductor, EV Group, and SUSS MicroTec.
