
Ultra Capacitors Market Report Scope & Overview:
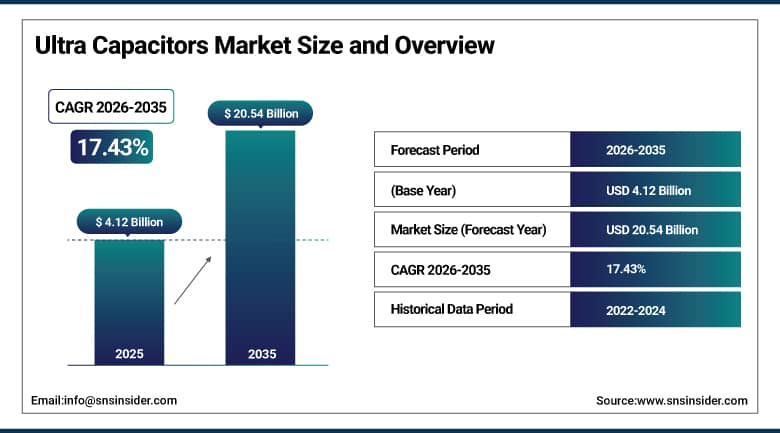
The Ultra Capacitors Market size was valued at USD 4.12 Billion in 2025 and is expected to reach USD 4.84 Billion in 2026, rising to USD 20.54 Billion by 2035. The market is forecast to expand at a CAGR of 17.43% during 2026–2035. Ultra capacitors store energy in an electric field instead of a chemical reaction, so they release and absorb power within seconds and endure hundreds of thousands of cycles. Demand is moving from memory backup toward electrified transport, grid support and the sharp power swings of data centers.
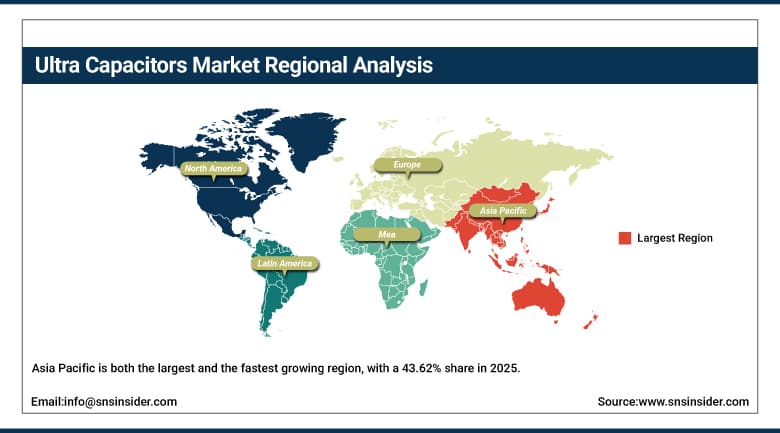
Asia Pacific accounted for the largest share of the market, at 43.62% in 2025, because it hosts the main cell producers, the biggest electric bus and rail programs and a deep electronics supply chain. North America follows, helped by data center construction and commercial vehicle electrification. Asia Pacific is also the fastest growing region, as China, Japan, South Korea and India add grid storage, rail and industrial automation capacity that favors fast-cycling storage. Latin America and Middle East & Africa are smaller regions, where wind farms, mining and new data center campuses create steady demand.
To Get More Information On Ultra Capacitors Market - Request Free Sample Report
Key Report Takeaways:
-
By type, electric double layer capacitors held 63.42% in 2025, while hybrid capacitors are the fastest growing.
-
By electrode material, activated carbon held 71.35% in 2025, while graphene is the fastest growing.
-
By module type, modules held 57.18% in 2025 and are also the fastest growing.
-
By application, automotive and transportation held 36.52% in 2025, while data centers and telecom are the fastest growing.
-
By capacitance, the 100 F to 1,000 F range held 41.67% in 2025, while cells above 1,000 F are the fastest growing.
-
By region, Asia Pacific held 43.62% in 2025 and is also the fastest growing.
Market Trends and Insights:
Cell makers are replacing activated carbon with graphene and carbon nanotube electrodes to raise energy density. Lithium-ion capacitor hybrids extend this path, storing several times more energy than a standard cell while keeping fast charge and long life.
Suppliers are shifting from single cells to engineered modules with balancing, thermal management and monitoring software, because rail, data center and heavy equipment buyers want a pack that fits a defined duty cycle.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Electrification of transport and heavy equipment |
+7.46% |
Asia Pacific |
Medium term (2 to 4 years) |
|
Power fluctuation management in data centers |
+5.38% |
North America |
Short term (2 years or less) |
|
Grid stabilization and renewable integration |
+4.21% |
Global |
Long term (4 years or more) |
|
Advances in graphene and hybrid electrodes |
+3.12% |
Global |
Long term (4 years or more) |
|
Backup power in electronics and industry |
+2.31% |
Global |
Short term (2 years or less) |
Electrification of Buses, Trucks, Rail and Heavy Equipment
Operators of fleets with frequent stops and short routes want storage that charges in seconds and does not wear out. Ultra capacitors capture braking energy in trams, metro trains, port cranes and mining machines, and they supply the burst power for starting engines and powering auxiliary loads. Transit agencies in China, Europe and India are extending electric bus and rail networks, and each program creates repeat orders for modules. Cells last for the life of a vehicle, which lowers replacement cost.
Power Fluctuation Management in Data Centers
Training large artificial intelligence models produces sudden swings in electrical load that stress grid connections and backup batteries. The International Energy Agency said in April 2025 that data center electricity consumption is on course to roughly double to around 945 TWh by 2030. Ultra capacitor trays and super-batteries placed at the rack or the power shelf absorb these spikes within milliseconds, protect batteries from deep cycling and reduce the need for oversized grid connections,. Fast response also protects upstream equipment.
Grid Stabilization and Renewable Integration
Wind and solar output changes within seconds, and grid operators need devices that can respond at the same speed. Ultra capacitors provide frequency regulation, voltage support and ride-through at substations, microgrids and industrial plants, and they work alongside batteries so that the batteries face fewer harsh cycles. Wind turbine makers also use them in pitch control systems to feather blades during outages. As renewable capacity grows, utilities add short-duration storage that complements longer-duration assets. Utilities value this fast and reliable response.
Advances in Graphene and Hybrid Electrode Materials
The main weakness of ultra capacitors has been low energy content compared with batteries. New electrode materials narrow that gap. Graphene and carbon nanotube structures offer more usable surface area, while lithium-ion capacitor designs combine a capacitive electrode with a battery-type electrode to lift energy density. Higher energy per kilogram opens applications such as portable power tools, drones and hybrid vehicle starts, and improved manufacturing yields help bring costs down over the decade. This widens the range of products that capacitors can serve.
Demand for Backup Power in Electronics and Industrial Systems
Meters, controllers, medical devices, point-of-sale terminals and industrial drives need a short burst of energy to save data or complete a safe shutdown when mains power drops. Small coin and cylindrical cells fit this need without the maintenance or transport limits of lithium batteries, and they tolerate wide temperature ranges. The spread of connected meters, sensors and smart factory equipment keeps adding sockets for these parts, which supports steady unit volumes. Replacement cycles for such devices are long, which supports repeat orders.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Low energy density compared with batteries |
-2.05% |
Global |
Long term (4 years or more) |
|
High cost per unit of stored energy |
-1.62% |
Global |
Medium term (2 to 4 years) |
|
Competition from advanced batteries |
-0.93% |
Global |
Medium term (2 to 4 years) |
|
Supply chain and electrolyte constraints |
-0.45% |
Europe |
Short term (2 years or less) |
Low Energy Density Compared with Batteries
A typical ultra capacitor holds only a small fraction of the energy that a lithium-ion cell of the same weight can store. Designers who need hours of run time must pair capacitors with a battery, which adds complexity and cost. For this reason the technology is confined to short-duration tasks such as peak shaving, braking recovery and backup bridging. Until hybrid designs raise energy content substantially, the addressable market remains bounded. Hybrid products are closing part of this gap. Research continues steadily.
High Cost per Unit of Stored Energy
When measured per kilowatt-hour of storage, ultra capacitors cost far more than batteries, and price is the first question for fleet buyers. Activated carbon, high-purity electrolytes and tight quality control raise cell costs, and modest volumes prevent the scale benefits seen in batteries. Buyers must justify the purchase on lifetime and power performance instead of capacity, and smaller operators often delay projects until total ownership calculations are favorable. Cost parity is unlikely before the end of the decade. Scale should help over time.
Competition from Lithium-Ion and Solid-State Batteries
Battery makers are improving power density and fast charging, and they sell at much larger scale. High-power lithium-ion cells with titanate or silicon anodes now cover some of the duty cycles that once belonged to capacitors, and solid-state designs promise further gains. Where a battery can meet a specification at lower cost, system designers choose it, so capacitor vendors must show clear advantages in cycle life, temperature range and safety. Their advantage is strongest in extreme heat, cold and very high cycle counts.
Supply Chain and Electrolyte Handling Constraints
Cells depend on specialty carbons, separators and organic electrolytes such as acetonitrile, which require careful handling and have limited qualified sources. Disruptions in carbon supply or shipping rules for chemicals can delay deliveries. New producers must build clean-room capacity and pass automotive and rail qualification, a process that takes years. These constraints slow the entry of new suppliers and keep lead times long during demand surges. Producers are qualifying second sources and holding larger carbon stocks to reduce this risk over time.
Ultra Capacitors Market Segment Analysis:
By Module Type, Modules Dominate Ultra Capacitors Market and Are Also Set to Register Fastest Growth.
Modules lead with a 57.18% share in 2025, since high-value programs in transport, grid and data centers buy complete assemblies instead of single cells. A module integrates series strings, balancing circuits, cooling and communications in a certified housing. This removes design risk for equipment makers, who can specify voltage, current and lifetime from a datasheet. Customers also gain a single source for warranty support across the length of a contract. Stocked ratings across suppliers also shorten buyer lead times.
Modules are forecast to register a CAGR of 18.64% during 2026–2035, ahead of the market. Rail, bus and crane builders favor standard voltage classes, and data center suppliers are launching rack-ready trays that plug into existing power shelves. Remote monitoring of temperature and state of health is becoming standard, which lets operators plan maintenance and supports service contracts that raise the recurring revenue of module vendors. Large buyers sign multi-year supply agreements that stabilize production planning for module makers.
By Type, Electric Double Layer Capacitors Dominate Ultra Capacitors Market; Hybrid Capacitors to Register Fastest Growth.
Electric double layer capacitors account for 63.42% of the market in 2025 because they are the established, standardized product with the widest range of voltages and capacitances. Producers in Asia, Europe and North America offer qualified cells for automotive, rail and industrial designs, and supply chains for activated carbon are mature. Long cycle life above one million cycles, wide temperature tolerance and simple balancing make them the default choice for most buyers. Standard dimensions also ease second sourcing.
Hybrid capacitors are projected to grow at a CAGR of 21.86% during 2026–2035. By pairing a battery-type electrode with a capacitive one, they store several times more energy than a standard cell and still charge quickly. This makes them suitable for energy harvesting nodes, backup units, mobile equipment and data center racks, where designers want more run time without moving to a full battery. Rising output in Japan and Korea should lower unit prices over time as new lines open.
By Electrode Material, Activated Carbon Dominates Ultra Capacitors Market; Graphene to Register Fastest Growth.
Activated carbon holds a 71.35% share in 2025 because it is inexpensive, available in large quantities and well understood by cell makers. Coconut shell and synthetic precursors are processed into high surface area powders that suit slurry coating on aluminum foil. Mature process know-how supports stable quality, and customers in automotive and industrial markets prefer proven material systems with long field records and predictable aging. Suppliers also qualify the carbon against purity limits, which protects cell life in harsh conditions.
Graphene is expected to expand at a CAGR of 24.31% from 2026 to 2035. Its high conductivity and accessible surface area allow higher energy and power in the same volume, which attracts developers of compact modules. Several producers have moved from pilot to commercial output of graphene-based electrodes. As yields improve and coating methods mature, price premiums should narrow, which brings the material into mainstream automotive and data center products. Public funding for advanced materials also supports pilot lines.
By Application, Automotive and Transportation Dominate Ultra Capacitors Market; Data Centers and Telecom to Register Fastest Growth.
Automotive and transportation account for 36.52% of the market in 2025. Electric buses, trams, metro trains, start-stop systems and port equipment all use ultra capacitors to capture braking energy and deliver peak power. Rail operators have run them in service for many years and report fuel and energy savings, and automotive suppliers now offer qualified cells for stop-start functions and safety backup circuits in modern vehicles. Improved software also forecasts cell aging, which supports performance guarantees in long contracts.
Data centers and telecom are projected to grow at a CAGR of 26.74% over 2026–2035. Rack power for accelerators changes quickly, and operators want storage that responds in milliseconds without wearing out. Capacitor trays and super-batteries cushion these changes and reduce stress on upstream equipment. Telecom sites also use them for brief ride-through and for supporting remote radio units during outages and load transitions. Hyperscale operators now run pilots in several regions, which encourages other buyers to evaluate comparable equipment.
By Capacitance, 100 F to 1,000 F Dominates Ultra Capacitors Market; Above 1,000 F to Register Fastest Growth.
Cells between 100 F and 1,000 F hold a 41.67% share in 2025 because they match the voltage and energy needs of industrial drives, wind turbine pitch systems, automotive modules and uninterruptible power supplies. They are produced in cylindrical formats by many suppliers, which keeps prices competitive. Engineers can build strings of these cells to reach the required voltage, and their familiar footprints speed qualification and second-source decisions. Suppliers are also qualifying these cells for vibration and temperature extremes.
Cells above 1,000 F are expected to grow at a CAGR of 22.58% during 2026–2035. Rail, heavy vehicles, grid support and data centers need large energy buffers from compact assemblies, and big-format cells reduce the number of connections and balancing circuits. Manufacturers are investing in automated lines for large cells, and advances in electrode coating help them deliver uniform performance at higher capacitance. Rail and heavy vehicle programs also specify them for regenerative braking, which sets a steady order base.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.37% |
|
Europe |
Germany |
24.18% |
|
Asia Pacific |
China |
52.04% |
|
Middle East & Africa |
Saudi Arabia |
31.45% |
|
Latin America |
Brazil |
46.12% |
Asia Pacific Ultra Capacitors Market
Asia Pacific is both the largest and the fastest growing region, with a 43.62% share in 2025 and a projected CAGR of 19.17% over 2026–2035. China leads the region, supported by large cell producers, extensive electric bus and tram deployment and strong demand from wind power, port automation and heavy industry. Local manufacturers supply competitive modules at scale and increasingly export them to other regions. Government subsidies for electric public transport and industrial upgrades have created steady tenders favoring locally built modules.
Japan brings advanced hybrid capacitor and module technology, with suppliers serving rail, data center and industrial customers. South Korea has established producers and growing data center demand, while India is expanding metro lines and renewable capacity. Government programs for electric mobility and grid modernization across the region keep the project pipeline active and should keep regional growth above the global rate. Southeast Asian countries such as Vietnam, Thailand and Malaysia are adding electronics assembly and data center capacity, and Australia is investing in grid storage projects that support renewable power.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Ultra Capacitors Market
North America held 23.48% of the market in 2025, led by the United States. The U.S. market was valued at USD 787.15 Million in 2025 and is expected to register a CAGR of 16.05% during 2026–2035. Hyperscale data center construction, commercial vehicle programs and utility storage projects drive orders, and several suppliers have announced plans to expand manufacturing capacity in the country. Federal funding for grid resilience and transit electrification, together with private investment in local cell production, supports this outlook.
Canada contributes through transit electrification, mining equipment and wind power, where cold weather performance matters. The region has a strong base of power electronics firms, integrators and research laboratories, and these groups help move new cell designs into commercial products. Defense and aerospace programs add demand for rugged storage that works across extreme temperatures and tolerates shock and vibration. Universities and national laboratories supply researchers and early test sites, and startups are commercializing new electrode chemistries for vehicles and grids.
Europe Ultra Capacitors Market
Europe accounted for 19.07% of the market in 2025, with Germany as the leading country. Rail, tram and bus operators have long used ultra capacitors for energy recovery, and engineering groups in the region build modules for industrial drives, wind turbines and automotive suppliers. Stringent emission rules and energy efficiency targets encourage operators to adopt technologies that cut losses in daily operation. Strict carbon rules for transport and industry give buyers a strong reason to evaluate capacitor-based energy recovery in new equipment.
France, the United Kingdom, Spain and the Nordic countries are important markets, with transit agencies buying trams and trains equipped with onboard storage. Finland and Estonia host leading cell and module producers, and new plants are being commissioned for data center products. Regional policy support for battery and storage supply chains gives local producers funding and a base of nearby customers. Nordic data center campuses, which benefit from cool climates and renewable power, are well placed to test rack-level capacitor storage at commercial scale.
Latin America Ultra Capacitors Market
Latin America accounted for 7.21% of the market in 2025, with Brazil as the leading country. Wind farms in the northeast, mining operations and electric bus pilots in major cities create demand for ultra capacitors in pitch control, equipment starting and energy recovery. Industrial users also buy them for power quality and backup in plants that face unstable grid supply. Local operators value the long life and low maintenance of these parts at remote wind sites, where technician visits are costly.
Mexico is the second major market, supported by automotive manufacturing and industrial automation tied to regional trade. Chile and Colombia are adding electric buses, and Argentina has wind and solar projects that require grid support. Import dependence, currency swings and limited local technical support slow wider adoption, but distributors are building stock and training to reach buyers in major cities. Transit programs in São Paulo and other large cities could adopt electric buses with onboard energy recovery, which would widen demand over the forecast period.
Middle East & Africa Ultra Capacitors Market
Middle East & Africa held 6.62% of the market in 2025. Saudi Arabia and the United Arab Emirates lead regional demand, where large solar parks, new data center campuses and smart city transit projects require storage that tolerates heat. Gulf governments are funding renewable and digital infrastructure, and these programs create tenders that include fast-response storage components. Extreme heat places heavy stress on batteries, so designers of solar plants and telecom shelters look for storage that keeps working at high temperatures, which favors capacitor-based solutions.
In Africa, South Africa and Morocco are the more active markets, with wind and solar capacity and growing mining activity. Remote telecom sites and off-grid industrial systems use ultra capacitors for backup and for supporting batteries in hot climates. Limited local manufacturing means imports dominate, but international suppliers are opening service partnerships and regional stocking points. Rising investment in data centers in the Gulf and in East Africa, together with rail and metro projects, should widen the customer base for suppliers.
Competitive Landscape:
The Ultra Capacitors Market is moderately concentrated. Specialist cell makers, electronics component groups and module integrators compete on energy density, cycle life, qualification records and complete system delivery. Asian producers hold large volumes in standard cells, while European and North American firms focus on modules.
Vendors pursue capacity expansion, automotive and rail qualification, partnerships with power electronics companies and new hybrid and graphene products, while data center demand draws in battery and power supply companies.
Ultra Capacitors Market Industry Leaders:
1. Skeleton Technologies: Estonian maker of graphene-based ultra capacitors.
2. Eaton: U.S. power management group with supercapacitor modules.
3. KYOCERA AVX: Component maker with SCC and SCM supercapacitors.
4. Vinatech: South Korean supplier of data center ultra capacitors.
5. Musashi Energy Solutions: Japanese developer of lithium-ion capacitors.
Companies Covered in this Report:
-
Skeleton Technologies
-
Eaton
-
KYOCERA AVX
-
Vinatech
-
Musashi Energy Solutions
-
CAP-XX
-
Panasonic Industry
Recent Industry Developments:
-
November 2025: Skeleton Technologies opened a plant in Varkaus, Finland, to produce super-batteries.
-
March 2026: Musashi Energy Solutions announced a collaboration with DG Matrix to pair its ESS400 storage system with a solid-state transformer.
-
August 2026: CAP-XX launched an oversubscribed retail offer alongside a placing and subscription of new shares.
-
August 2026: Eaton issued updated technical data for its HVH supercapacitor cells.
-
October 2026: Siemens led a strategic investment in Skeleton Technologies to expand U.S. manufacturing.
-
October 2026: Vinatech reported data center supercapacitor contracts signed since late June, led by an order from AcBel Polytech.
Scope and Research Methodology
This study estimates the Ultra Capacitors Market for 2025 as the base year and forecasts it through 2035. The scope covers electric double layer capacitors, pseudocapacitors and hybrid capacitors, supplied as cells and as modules, for transport, energy, industrial, electronics and data center uses. Values are reported in USD at the point of sale by manufacturers to equipment makers and system integrators. Conventional aluminum electrolytic and film capacitors, and lithium-ion batteries, are outside the scope. Segmentation covers type, electrode material, module type, application, capacitance and region, and both original equipment and replacement demand are included. All values are rounded to two decimals.
Secondary research included company annual reports, investor presentations and filings, regulator and government databases, trade association data, product documentation, and peer-reviewed and industry publications. Primary research consisted of structured interviews and surveys with executives, product and business heads, procurement teams and engineers across the value chain. These inputs were used to validate shipment volumes, pricing and the share of cells and modules. Interviews covered cell developers, module integrators, distributors, transit and utility engineers and data center power planners, which allowed assumptions on specifications, qualification timelines and pricing to be tested against practice.
Market size was built from the bottom up using vendor revenue, shipment and capacity data, and was cross-checked from the top down against vehicle, rail, data center and renewable energy build-out. Triangulation across these views fixed the base year value. Forecasts consider technology cost, electrification policy, power demand growth and macroeconomic conditions, and segment and regional shares were assigned from adoption patterns in each setting. An analyst quality review checked consistency before release. The forecast was run under conservative, base and optimistic adoption cases, and growth rates for each segment were set so that the parts remain consistent with the whole. Estimates are reviewed periodically as new data becomes available.
Ultra Capacitors Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.12 Billion |
| Market Size by 2035 | USD 20.54 Billion |
| CAGR | CAGR of 17.43% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Electric Double Layer Capacitors, Hybrid Capacitors, and Pseudocapacitors) • By Electrode Material (Activated Carbon, Graphene, Carbon Nanotubes, and Metal Oxides and Conductive Polymers) • By Module Type (Cells and Modules) • By Application (Automotive and Transportation, Energy and Utilities, Industrial, Consumer Electronics, and Data Centers and Telecom) • By Capacitance (Below 100 F, 100 F to 1,000 F, and Above 1,000 F) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Skeleton Technologies, Eaton, KYOCERA AVX, Vinatech, Musashi Energy Solutions, CAP-XX, Panasonic Industry |

Frequently Asked Questions
The market was valued at USD 4.12 Billion in 2025 and is projected to reach USD 20.54 Billion by 2035, at a CAGR of 17.43%.
The Electric Double-layered Capacitors is leading in the market revenue share in 2023.
Asia Pacific leads with a 43.62% share in 2025 and is also the fastest growing, at a CAGR of 19.17%.
Data centers and telecom are expected to grow fastest, at a CAGR of 26.74% during 2026–2035.
Skeleton Technologies, Eaton, KYOCERA AVX, Vinatech and Musashi Energy Solutions lead, along with CAP-XX and Panasonic Industry.
Electric double layer capacitors, activated carbon, modules, automotive and transportation, and 100 F to 1,000 F cells lead, while hybrid capacitors, graphene, data centers and cells above 1,000 F grow fastest.
Low energy density, high cost per unit of energy, battery competition and supply chain constraints restrain faster adoption.
