
Hi-Fi System Market Report Scope & Overview:
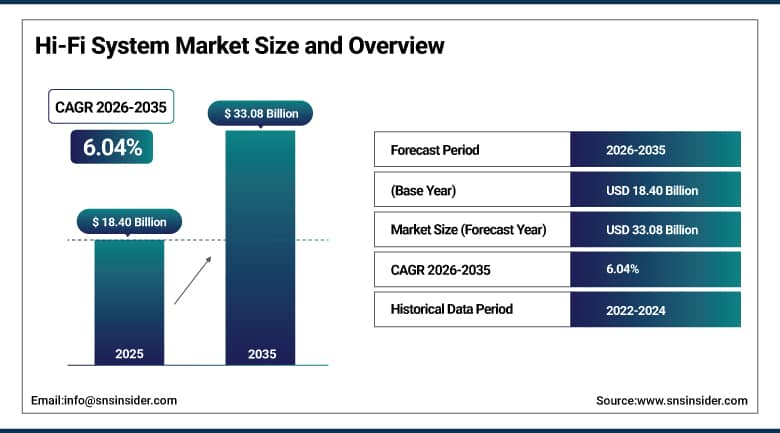
The Hi-Fi System Market was valued at USD 18.40 Billion in 2025 and is expected to reach USD 33.08 Billion by 2035, growing at a CAGR of 6.04% from 2026-2035.
The Hi-Fi System Market covers high-fidelity audio equipment such as speakers, amplifiers, receivers, streamers, digital-to-analog converters, turntables and complete wireless music systems designed for accurate sound reproduction. Demand is shaped by the mainstreaming of lossless and hi-res streaming, a strong revival in vinyl records and the rising popularity of home entertainment spaces. Manufacturers are combining traditional audio craftsmanship with networked features, room correction and voice control. Premiumization is evident as buyers trade up for better sound quality in living rooms, studios and vehicles. Wireless and all-in-one designs are widening the audience beyond traditional enthusiasts. Competition among heritage names and newer entrants continues to shape pricing, design and distribution choices.
⮞On 18 March 2026, the International Federation of the Phonographic Industry reported that global recorded music revenues reached USD 31.7 billion in 2025, up 6.4%, with physical formats up 8.0% and vinyl up 13.7%. Growth in both streaming and vinyl supports demand for quality playback equipment.
To Get More Information On Hi-Fi System Market - Request Free Sample Report
Hi-Fi System Market Trends:
-
Powered speakers and streaming amplifiers with built-in networking are replacing separate component stacks in many homes.
-
Vinyl revival is lifting demand for turntables, phono stages and integrated amplifiers with analog inputs.
-
Lossless and hi-res streaming from mainstream services is raising expectations for sound quality from everyday listeners.
-
Room correction, Dolby Atmos and HDMI eARC are becoming standard features in premium audio systems.
-
Brand consolidation and cross-brand partnerships are reshaping the competitive landscape among audio groups.
U.S. Hi-Fi System Market Outlook:
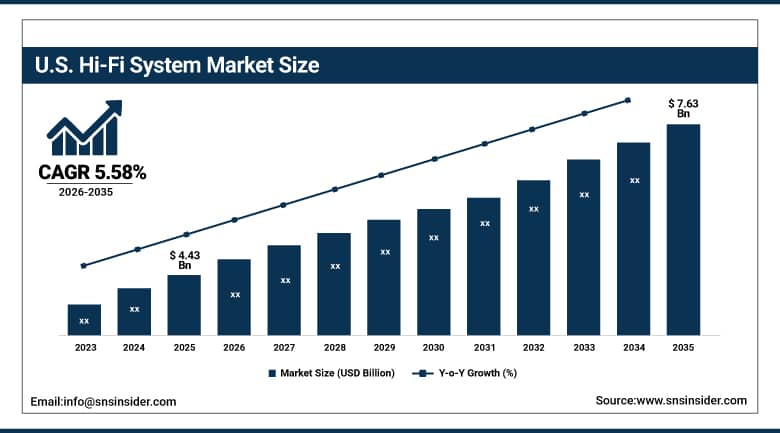
The U.S. Hi-Fi System Market was valued at USD 4.43 Billion in 2025 and is expected to reach USD 7.63 Billion by 2035, growing at a CAGR of 5.58% from 2026-2035.
The U.S. Hi-Fi System Market is the largest national market in North America, supported by high household incomes, a strong culture of home entertainment and an active community of audio enthusiasts. Sales flow through specialty dealers, big-box retailers and direct online channels. Vinyl has reached its highest revenue level in decades, which benefits turntable and amplifier makers. Premium streaming subscriptions are also mainstream, creating a base of listeners willing to upgrade playback. Home theater and multi-room audio add system sales. Tariffs and cost pressures are shaping pricing. These factors sustain steady growth in the U.S. through 2035. Partnerships with streaming services, retailers and installers extend reach and speed up adoption.
⮞In March 2026, the Recording Industry Association of America reported that U.S. recorded music revenue reached a record USD 11.5 billion in 2025, with vinyl crossing USD 1 billion, up 9.3%. The strength of physical formats supports hi-fi hardware sales.
Hi-Fi System Market Segment Analysis:
-
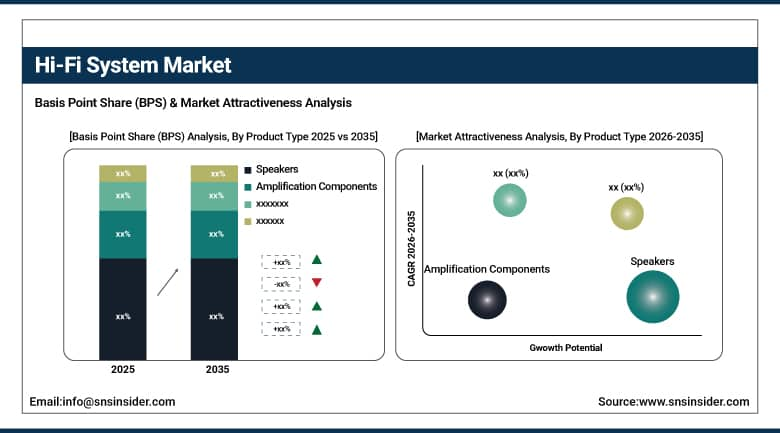
By Product Type, the Speakers segment dominated the Hi-Fi System Market with approximately 40.50% share in 2025, while the Amplification Components segment is the fastest growing with a CAGR of approximately 6.82%.
-
By Connectivity, the Wireless segment dominated the Hi-Fi System Market with approximately 61.87% share in 2025 and is also the fastest growing with a CAGR of approximately 7.26%.
-
By Distribution Channel, the Offline segment dominated the Hi-Fi System Market with approximately 57.13% share in 2025, while the Online segment is the fastest growing with a CAGR of approximately 7.84%.
-
By End User, the Residential segment dominated the Hi-Fi System Market with approximately 54.38% share in 2025, while the Commercial segment is the fastest growing with a CAGR of approximately 7.05%.
By Product Type, Speakers Dominates the Hi-Fi System Market and Amplification Components Grows Fastest
Speakers lead because they are the most visible and most frequently replaced part of any hi-fi setup, and they determine how the system sounds. The category spans floor-standing towers, bookshelf models, powered speakers, soundbars and all-in-one wireless units. Buyers often upgrade speakers first before changing other components. Brands compete on driver technology, cabinet design and finish, which supports a wide price ladder. Active speakers with built-in amplifiers are gaining ground by simplifying setup. Suppliers also invest in listening rooms, dealer training and after-sales support to build lasting loyalty with buyers.
Amplification components are growing fastest as streaming amplifiers, integrated amplifiers and receivers add network audio, digital inputs, phono stages and room correction in one chassis. Class D designs improve efficiency and reduce size, while HDMI eARC links the products to televisions. Vinyl revival is also lifting demand for amplifiers with analog inputs. Manufacturers launching new streaming amps at trade shows show strong investment in the segment. Replacement of aging receivers adds further volume. Product refresh cycles are measured in years, so brands that update their ranges with new features keep their lead.
⮞In January 2026, Luminate reported that U.S. vinyl album sales reached 47.9 million units in 2025, up 8.6%. The growth in records sustains demand for turntables, phono stages and amplifiers.
By Connectivity, Wireless Dominates the Hi-Fi System Market and Also Grows Fastest
Wireless products are the front-runners due to consumer demand for great audio with minimal wiring. The use of Wi-Fi, Bluetooth and specialized multi-room networks enables consumers to stream audio from phones and online music services to speakers and amplifiers. Additional functions such as smart home compatibility, voice assistance and apps increase user convenience. Lossless encoding along with advancements in wireless technology have reduced the audio quality difference from traditional wired technologies. New generations of consumers who enter the high-end audio category are more concerned about easy installation and flexibility in placement.
Wireless is also the fastest growing connectivity type as brands expand multi-room ecosystems and add support for new audio standards. Portable and indoor-outdoor models broaden the use cases for high-quality sound. Manufacturers are combining Wi-Fi streaming with HDMI and analog inputs so that wireless products can also serve as the center of a home theater. Software updates add features over time, which extends product life. Wired systems remain important for purists who prioritize reference-grade sound. Rising interest in music quality keeps enthusiasm for better equipment high from year to year.
⮞On 29 July 2026, Sonos reported that revenue for its fiscal third quarter ended 27 June 2026 was USD 375.3 million, up 9%. The result points to continued strength in wireless home audio.
By Distribution Channel, Offline Dominates the Hi-Fi System Market and Online Grows Fastest
Offline channels lead because hi-fi buyers want to listen before they buy and value expert advice. Specialty audio dealers offer demonstration rooms, system matching and installation services that cannot be replicated online. Electronics chains and department stores add reach for mainstream products. Brand-owned showrooms and flagship stores strengthen premium positioning. Trade shows and dealer events also drive sales of high-end components. The tactile and auditory nature of the product keeps physical retail central. Manufacturers continue to refine drivers, amplifier circuits and digital processing to raise sound quality.
The highest growth rates for sales come from online transactions as consumers are gaining trust in buying audio equipment due to reviews, video and liberal returns. Brands that sell their goods directly to consumers do not have dealers' profit share and therefore are able to offer competitive pricing. The variety of audio equipment is found on marketplaces and at the websites of manufacturers and specialists' stores provide additional consultation via live chat. Streaming and forums help people get acquainted with the better quality audio equipment. Dealers adapt to this tendency by creating hybrid models combining web and in-store options.
⮞On 10 September 2025 , Spotify launched Lossless streaming for Premium subscribers in 24-bit/44.1 kHz FLAC, rolling out to more than 50 markets. The move increases online interest in better playback equipment.
By End User, Residential Dominates the Hi-Fi System Market and Commercial Grows Fastest
Residential buyers lead because the majority of hi-fi equipment is bought for living rooms, dedicated listening rooms and home offices. Enthusiasts invest in component systems, while mainstream households choose all-in-one speakers and soundbars. Rising spending on home entertainment, remote work and personalized spaces supports demand. Older buyers with higher disposable income remain a core group, and younger listeners are joining through vinyl and streaming. Interior design trends push brands to offer attractive finishes. Industrial design and finish options have become important for buyers who place systems in living spaces.
Commercial use is growing fastest as restaurants, hotels, retail stores, fitness studios and offices invest in high-quality background and zoned audio to improve customer experience. Premium brands now offer installation-ready speakers and networked amplifiers that integrate with building systems. Luxury hospitality and flagship retail use sound as a brand element. Professional audio providers are cooperating with consumer brands on hybrid lines. Automotive audio partnerships add a related stream of demand for premium sound systems. Bundled accessories such as cables, stands and cartridges raise the value of each system sale.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
38.14% |
|
North America |
United States |
84.12% |
|
Europe |
Germany |
26.78% |
|
Latin America |
Brazil |
44.63% |
|
Middle East & Africa |
Saudi Arabia |
31.46% |
Asia Pacific Hi-Fi System Market Insights
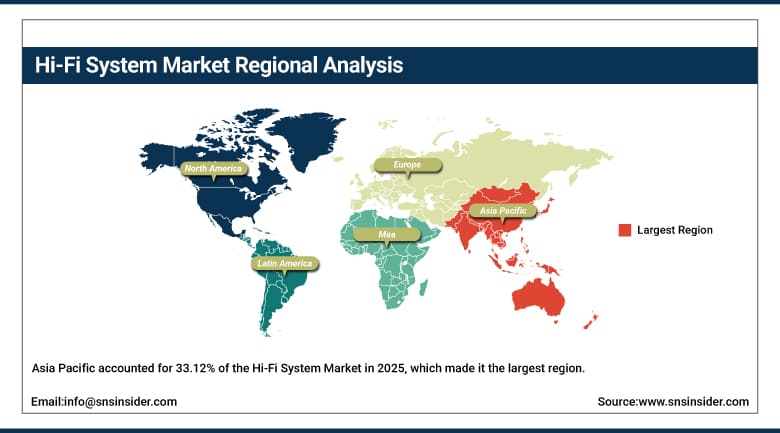
Asia Pacific accounted for 33.12% of the Hi-Fi System Market in 2025, which made it the largest region, and it is also the fastest growing at a CAGR of 7.12% during 2026-2035. China is the biggest consumer and a major manufacturing base for speakers and electronics. Japan has a long audiophile tradition and hosts leading brands such as Yamaha, Sony, Onkyo and Technics. South Korea, Taiwan and India add rising demand for premium audio. Australia contributes a mature vinyl and streaming culture. Customer reviews and listening tests at shows strongly influence which models buyers trust.
Growing middle-class incomes and interest in home entertainment lift purchases of speakers, amplifiers and wireless systems. Local brands compete on price in China and India, while global names focus on flagship and mid-range ranges. Vinyl and high-resolution streaming are gaining followers among younger listeners. Dedicated hi-fi stores and department store counters remain important. E-commerce festivals drive large online volumes. Contract manufacturing in the region supplies many global brands. Improved supply chains for components are shortening lead times for new designs. Sustainability claims, such as repairability and longer product life, are gaining weight in purchase decisions.
⮞On 4 August 2026, Yamaha reported that its Audio Equipment segment generated revenue of JPY 35.0 billion in April to June 2026, up 5.9%. The growth reflects steady demand in Asia and other markets.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Hi-Fi System Market Insights
North America holds the second-largest share, led by the United States, with Canada contributing a smaller but affluent base of buyers. The region is home to major brands including Sonos, Bose, Klipsch, McIntosh and Harman labels. Consumers have a strong tradition of home theater and music listening, and specialty dealers remain important. Vinyl sales have reached record levels, and premium streaming services are mainstream. Custom installers support whole-home audio projects in new housing. Trade shows and dealer events help brands launch products and collect early feedback.
The wireless multi-room devices, soundbars, and speakers have been capturing the majority of the volume while the component systems have been appealing to enthusiasts. The tariffs have been putting pressure on prices and margins, and brands have been adjusting their supply chain. E-commerce sales through big retailers as well as branded websites are growing. Gaming and TV upgrades are among the factors behind the adoption of the soundbars and subwoofers. Automotive collaborations bring additional premium sales. Growth remains moderate as the category is mature and upgrade-driven by new functionalities.
⮞In January 2026, the Consumer Technology Association forecast that U.S. consumer technology revenue would reach USD 565 billion in 2026 despite tariffs and economic headwinds. The outlook indicates solid spending on home electronics.
Europe Hi-Fi System Market Insights
Europe holds a substantial share and is the spiritual home of many high-end brands, including Bang & Olufsen, Naim, KEF, Focal, Cambridge Audio and Linn. Germany, the United Kingdom and France lead consumption, and Scandinavia has a strong design-driven premium market. High End in Munich and other shows keep the enthusiast community active. Vinyl is thriving in the UK and Germany. European buyers value craftsmanship, sustainability and industrial design. Product refresh cycles are measured in years, so brands that update their ranges with new features keep their lead.
Specialist dealers and stand-alone hi-fi stores are still an important sales route with high levels of brand loyalty. Active loudspeakers and streaming amps are becoming increasingly popular at the expense of separate components. Energy efficiency and environmentally-friendly design regulations affect the products’ development. Fluctuations in currency values and increasing costs of living have made discretionary spending more difficult in certain markets. The brands are now diversifying into Asia and North America to compensate for the saturated domestic market.
⮞On 2 July 2026, Bang & Olufsen reported that revenue for its 2025/26 financial year was DKK 2,468 million, down 3.3%, while gross margin rose 3.2 percentage points to 58.2%. The result shows both pressure on volumes and strength in premium positioning.
MEA & Latin America Hi-Fi System Market Insights
Latin America is led by Brazil and Mexico, where growing music streaming, concerts and home entertainment support demand for speakers, soundbars and wireless systems. Premium component systems are a small segment but are expanding among affluent buyers in major cities. Physical formats such as vinyl are rising from a small base. Imports dominate supply, so exchange rates and duties shape prices. Online marketplaces and electronics chains are the main channels. Suppliers also invest in listening rooms, dealer training and after-sales support to build lasting loyalty with buyers.
There is growth in the Middle East and Africa markets due to investments by the affluent Gulf states in luxurious housing developments and hotels featuring expensive audio systems. The leading countries include Saudi Arabia and the United Arab Emirates, as well as South Africa with an existing retail chain. Home theatres and smart villas constitute major purchasers of these systems. There are no dedicated distributors; rather, there are specialists in imports and installation. The markets are small but have future prospects due to increasing incomes and subscription services. Refreshment cycles for these products take years.
⮞In March 2026, Pro-Musica Brasil reported that Brazil's recorded music revenue reached about BRL 4 billion in 2025, up 14%, with physical media up 25.6%. The growth supports interest in playback equipment across the region.
Market Dynamics:
Growth Drivers: Lossless Streaming and Vinyl Revival Drive Growth in the Hi-Fi System Market
Better music sources are the strongest driver. Premium streaming services now offer lossless and hi-res tiers, and listeners who hear the difference seek equipment that can reproduce it. Services focused on audiophile quality are growing quickly, and mainstream platforms have followed. Network-capable amplifiers, streamers and powered speakers are designed to take advantage of these sources. Higher music revenue signals a healthy base of paying listeners who care about sound. Partnerships with streaming services, retailers and installers extend reach and speed up adoption. Rising interest in music quality keeps enthusiasm for better equipment high from year to year.
Vinyl and physical formats provide a second driver. Record sales have climbed for years, and turntables, phono stages and matching amplifiers are selling well. Younger buyers see records as an engaging way to listen and often begin with entry-level systems before upgrading. Home entertainment spending and interest in dedicated listening rooms add further demand. Brands that offer attractive design and simple setup are attracting first-time hi-fi buyers. Manufacturers continue to refine drivers, amplifier circuits and digital processing to raise sound quality. Buyers increasingly weigh software support, warranty terms and upgrade paths before purchase.
Restraints: Price Sensitivity and Weak Hardware Volumes Restrain Growth in the Hi-Fi System Market
Hi-fi equipment is a considered, high-priced purchase, and buyers delay decisions when household budgets tighten. Inflation, higher interest rates and tariffs have raised retail prices in several regions. Smartphone speakers, soundbars and earbuds provide acceptable sound for many consumers at much lower cost, which limits the size of the enthusiast base. Specialty retail footprints are shrinking in some countries, reducing opportunities for demonstration. Differences in room size, income and retail structure also guide product choice and pricing. Industrial design and finish options have become important for buyers who place systems in living spaces.
Component categories such as stereo systems, system audio and speaker sets face structural decline in some markets as households shift to all-in-one wireless and portable products. Shipments of traditional categories can fall sharply from one year to the next. Supply chain disruptions and component costs add pressure. Product cycles are long for premium equipment, so replacement sales are slow. Counterfeit and low-cost copies also weigh on brand value in some regions. Bundled accessories such as cables, stands and cartridges raise the value of each system sale.
⮞The Japan Electronics and Information Technology Industries Association reported July 2026 shipments in Japan of speaker systems at 33 thousand units, 65.6% of the prior year, and system audio at 33 thousand units, 77.4% of the prior year. The decline shows pressure on traditional categories.
Opportunities: Premium Vinyl and Hi-Res Ecosystems Create Opportunities in the Hi-Fi System Market
Premium vinyl ecosystems offer clear growth for suppliers of turntables, cartridges, phono stages and record-care accessories. Younger buyers who start with records tend to move up to better equipment over time. New pressing plants and record store growth in Asia Pacific, Latin America and Europe are expanding the base. Bundled systems that combine a turntable, amplifier and speakers can lower the entry barrier and capture customers early. Customer reviews and listening tests at shows strongly influence which models buyers trust. Improved supply chains for components are shortening lead times for new designs.
Ecosystems for high-resolution streaming provide an additional business opportunity as well. Brands can collaborate with streaming services and labels on device certification, bundling subscriptions and producing unique content. Integration into smart homes, room calibration, and software subscriptions are the sources of recurring income. The developing countries, with increasing middle classes, and the projects of hospitality and retail are the opportunities of brand expansion. Brands, which unite the traditional design of products with modern connectivity, have all chances to attract new clients. The claims of sustainability, such as repairability and long-lasting products, become more influential in purchasing decisions.
⮞In March 2026 , ARIA reported that Australian recorded music revenue reached AUD 727 million in 2025, with vinyl album revenue up 4.1% to AUD 46.3 million on more than 1.2 million units. The strength of vinyl creates a base for audio hardware.
Recent Developments:
-
2025: Harman, a Samsung company, completed the acquisition of Sound United from Masimo for USD 350 million in cash. The deal brings the Bowers & Wilkins, Denon, Marantz and Definitive Technology brands into Harman's portfolio and creates one of the largest premium audio groups.
-
2026: Klipsch introduced the Fives II, Sevens II and Nines II active speakers at CES 2026. The speakers use an Onkyo electronics package with Dirac Live room correction and support Dolby Atmos and DTS:X, targeting buyers who want powered systems with streaming and HDMI connectivity.
-
2026: Bose revealed the Lifestyle Ultra collection, which includes a speaker at USD 299, a soundbar at USD 1,099 and a subwoofer at USD 899. The range extends the company's home audio line with premium all-in-one components.
-
2026: Naim announced the Mu-so Utopia all-in-one system combining Naim amplification with Focal Utopia-derived drivers, hi-res streaming and HDMI eARC. NAD also introduced the C 359S streaming amplifier at GBP 1,099 with Bluesound BluOS and the C 569 CD player at GBP 749.
Hi-Fi System Market Key Players are:
-
Yamaha Corporation
-
Sonos
-
Bose Corporation
-
Harman International
-
Bowers & Wilkins
-
Denon
-
Marantz
-
Klipsch Audio
-
Onkyo
-
Cambridge Audio
-
Naim Audio
-
NAD Electronics
-
Focal
-
Audio-Technica
-
Bang & Olufsen
-
McIntosh Laboratory
-
Rotel
-
Technics
Hi-Fi System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.40 Billion |
| Market Size by 2035 | USD 33.08 Billion |
| CAGR | CAGR of 6.04% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Speakers, Amplification Components, and Source Components) • By Connectivity (Wireless and Wired) • By Distribution Channel (Offline and Online) • By End User (Residential, Commercial, and Automotive) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Yamaha Corporation, Sonos, Bose Corporation, Harman International, Bowers & Wilkins, Denon, Marantz, Klipsch Audio, Onkyo, Cambridge Audio, Naim Audio, NAD Electronics, Focal, Audio-Technica, Bang & Olufsen, McIntosh Laboratory, Rotel, Technics |

Frequently Asked Questions
The key players in the Hi-Fi System Market include Yamaha Corporation, Sonos, Bose Corporation, Harman International, Bowers & Wilkins, among others.
Key opportunities include premium vinyl ecosystems, partnerships with hi-res streaming services, and commercial installations in hospitality and retail.
The major growth factor is the mainstreaming of lossless streaming together with the revival of vinyl, which raises demand for equipment that can reproduce high-quality sound.
The Speakers segment dominated the Hi-Fi System Market with approximately 40.50% share in 2025, because speakers determine sound quality and are replaced frequently.
Asia Pacific dominated the Hi-Fi System Market with a 33.12% share in 2025, driven by large consumer bases, manufacturing strength and growing premium demand in China, Japan and India.
